Stock Analysis · Hikma Pharmaceuticals PLC (HKMPF)
Overview
Hikma Pharmaceuticals PLC is a global drugmaker focused on generic medicines, injectable treatments, and branded products sold mainly in the Middle East and North Africa. The company operates across North America, Europe, and the MENA region, with a business model built around supplying hospitals, pharmacies, and healthcare systems with a broad portfolio of lower-cost medicines. Its main strength is not breakthrough drug discovery in the style of large biotech companies, but scaled manufacturing, regulatory know-how, and the ability to run different pharmaceutical niches at the same time.
Revenue is spread across three main divisions. Based on the company’s latest annual reporting, the mix is approximately:
- Injectables: about 41% of revenue. This includes sterile injectable medicines used in hospitals, such as anti-infectives, oncology products, and other acute-care treatments.
- Generics: about 31% of revenue. This is primarily oral and other non-injectable generic medicines, with the U.S. being the core market.
- Branded: about 28% of revenue. This segment mainly covers marketed branded pharmaceuticals sold across the Middle East and North Africa, often in chronic and acute therapy areas.
This mix matters because it gives Hikma more diversification than many generic drug companies that depend heavily on one market or one product type. It also means the business can benefit from both hospital demand and everyday prescription volumes. Over the last several years, total revenue has climbed from roughly $2.6 billion in 2021 to about $3.3 billion in 2025, while profitability recovered after a weak 2022 period. Gross profit has stayed broadly stable in absolute dollars, so recent growth has been driven more by higher sales volume than by expanding gross margin.
The long-term pattern shows a business that has increased sales steadily, while operating income has remained resilient even as manufacturing costs rose. Net income appears more volatile than revenue, which is common in pharmaceuticals because legal, regulatory, tax, and financing items can move sharply from year to year.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Drug Manufacturers - Specialty & Generic | |
| Market Cap ⓘ | $4.36B | |
| Beta ⓘ | 0.65 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 11.97 | 24.79 |
| P/B Ratio ⓘ | 1.84 | 3.08 |
| FCF Yield ⓘ | 11.72% | 3.15% |
| Dividend Yield ⓘ | 4.08% | 1.94% |
| EBIT / EV ⓘ | 20.30% | 0.57% |
| PEG ⓘ | 2.35 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 4.20% | 7.45% |
| RPS Growth (5Y CAGR) ⓘ | 8.24% | 8.61% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -17.81% |
| BVPS Growth (5Y CAGR) ⓘ | 2.46% | 3.72% |
| Margin Growth (5Y Trend) ⓘ | -4.64% | -0.62% |
| FCF Growth (5Y CAGR) ⓘ | -20.23% | 1.04% |
| DPS Growth (5Y CAGR) ⓘ | 13.32% | 6.77% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 24.15% | 3.24% |
| ROA (Latest) ⓘ | 13.80% | 3.01% |
| ROIC (5Y Median) ⓘ | 12.68% | 4.60% |
| ROA (5Y Median) ⓘ | 7.32% | 1.89% |
| Net Debt / EBIT (Latest) ⓘ | 1.36 | 1.34 |
| Net Debt / EBIT (5Y Median) ⓘ | 1.84 | 1.84 |
| Net Debt / EBITDA (Latest) ⓘ | 1.01 | 1.00 |
| Net Debt / Assets ⓘ | 29.06% | 5.45% |
| EBITDA / Interest ⓘ | N/A | 9.64 |
| Operating Margin (Latest) ⓘ | 18.74% | 9.27% |
| Operating Margin (5Y Median) ⓘ | 19.79% | 7.38% |
| Debt to Equity (Latest) ⓘ | 77.57% | 28.58% |
| Profit Margin (Latest) ⓘ | 11.32% | 3.59% |
| Free Cash Flow (Latest) ⓘ | $511.00M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | -7.45% | +42.80% |
| 12M Return (excl. last month) ⓘ | +3.45% | +18.50% |
| 6M Return ⓘ | +19.05% | +7.57% |
| Price vs. 200-Day MA ⓘ | -2.15% | +5.12% |
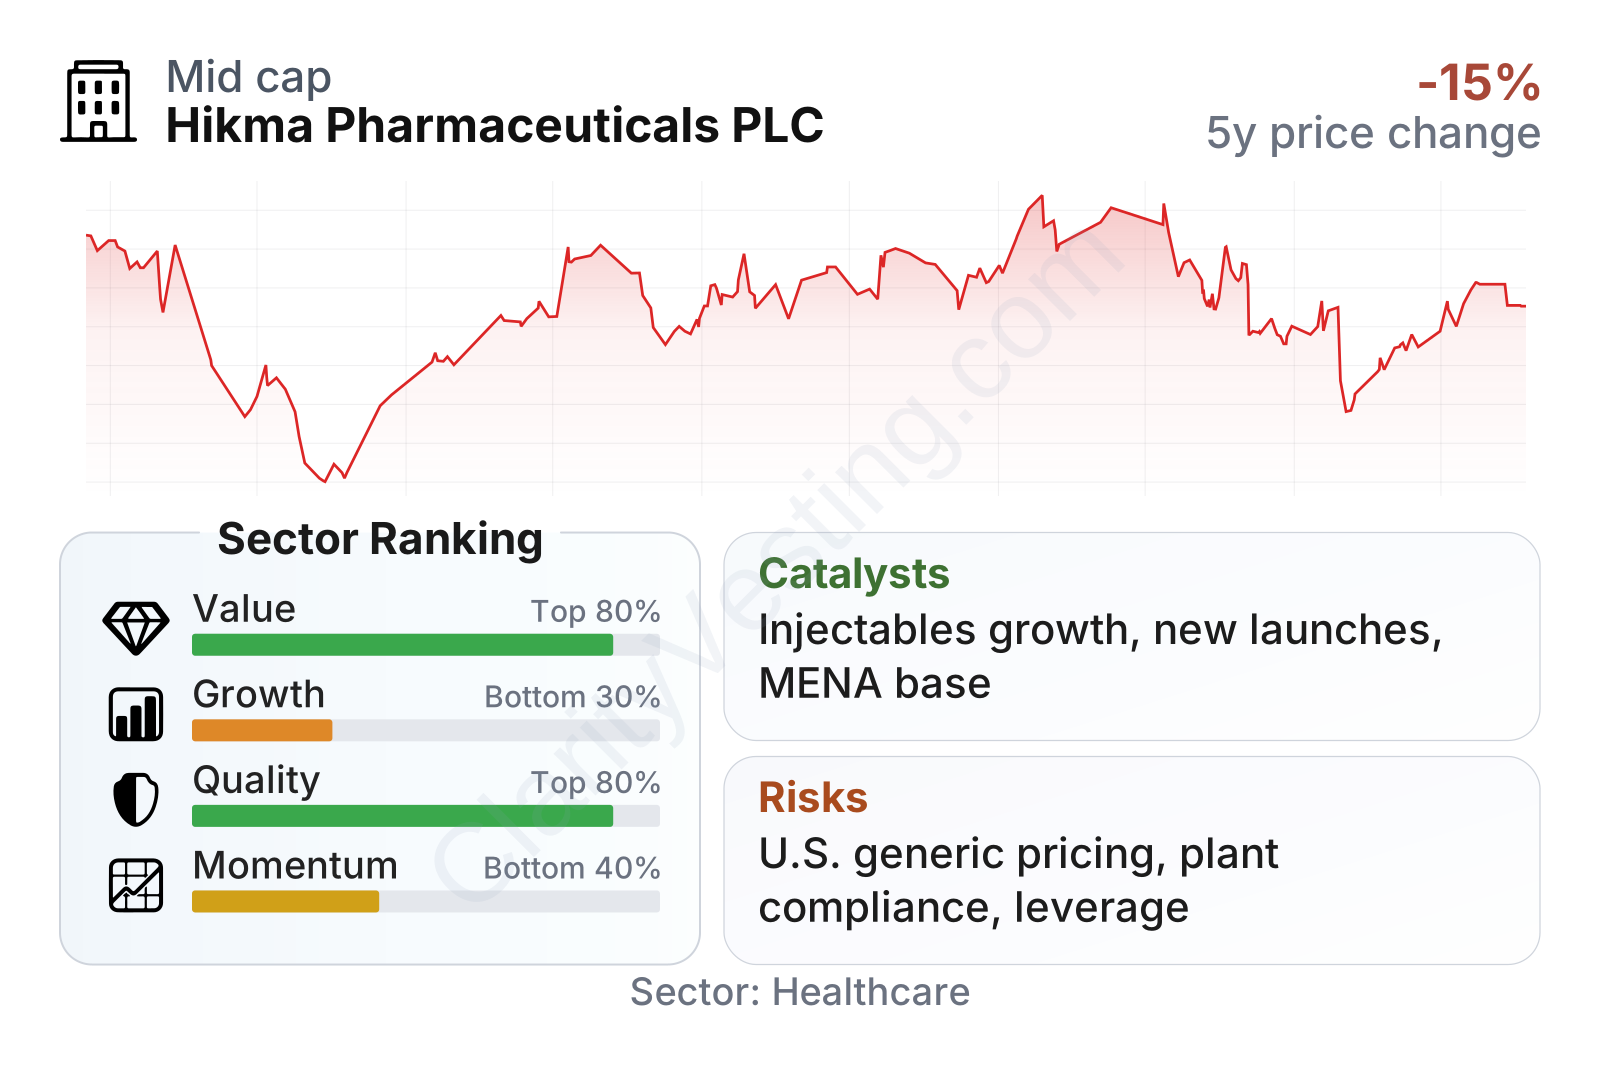
Hikma sits in the larger mid-cap range and has shown lower share-price volatility than the broader market, as reflected by a beta well below 1. On valuation and cash generation, the company ranks strongly versus much of the healthcare sector: its earnings multiple and book multiple are below sector medians, while free cash flow yield, operating profitability, and returns on capital are notably stronger. Dividend yield is also above the sector median.
The weaker area is growth. Recent revenue growth has been positive but slower than the sector median, and five-year free cash flow growth has been uneven. Margin trends over five years also show some pressure, even though current operating margin remains comfortably above the sector norm. Price performance has lagged over three years, but the shorter-term move has improved, suggesting sentiment has started to recover after a softer period.
Growth
Hikma operates in a sector with durable long-term demand. Aging populations, rising chronic disease, pressure on healthcare budgets, and the need for reliable medicine supply all support generic and hospital-drug demand. That is especially relevant for injectables, where manufacturing is complex and supply disruptions are common. In this part of the market, scale, regulatory compliance, and production quality can matter more than marketing power.
The company’s strategy is coherent for that environment. Injectables are attractive because they tend to have higher barriers to entry than standard oral generics. Sterile manufacturing is difficult, capacity is limited, and customers value dependable supply. Hikma has continued to invest in this business, which helps support its position in U.S. hospitals and other institutional channels. The branded division adds another layer of stability through established regional franchises in MENA, where healthcare spending and access to medicines have been expanding over time.
Another growth driver is product launches and pipeline depth. In generics and injectables, growth often comes from a constant flow of approvals rather than one blockbuster drug. Hikma has regularly highlighted new product introductions, manufacturing expansion, and a focus on more complex formulations where competition is usually less intense. That approach makes strategic sense because simple generics often face rapid price erosion, while more specialized products can retain better economics.
Recent company updates have also pointed to continued confidence in the injectables business and ongoing product development activity across the portfolio. The broad opportunity is not tied to a single event; it is tied to Hikma’s ability to keep winning approvals, supplying customers consistently, and capturing share in shortage-prone categories where reliability has real value.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


