Stock Analysis · HydroGraph Clean Power Inc (HGRAF)
Overview
HydroGraph Clean Power Inc is a very small specialty materials company focused on graphene, a carbon-based material known for conductivity, strength, and light weight. The company says its manufacturing process produces “pristine” graphene through detonation synthesis, and its commercial goal is to sell graphene powders and dispersions that can improve products in areas such as batteries, supercapacitors, concrete, coatings, lubricants, and other industrial applications.
At this stage, HydroGraph is still much closer to an early commercialization company than to a mature chemicals business. Public filings show that revenue remains very low compared with operating expenses, which means the investment case depends much more on whether its graphene technology can scale into meaningful commercial demand than on current earnings power.
The company’s public filings do not provide a detailed segment breakdown with stable recurring categories large enough to support a precise revenue mix. Based on management disclosures, revenue appears to come mainly from the following sources:
- Graphene product sales: commercial sales of graphene materials for customer testing, product development, and limited production use. This appears to represent the large majority of revenue.
- Technical development and evaluation work: smaller amounts tied to customer qualification, trials, and collaborative work connected to future commercial programs.
- Other minor revenue: limited miscellaneous amounts that have not been separately disclosed in enough detail to assign a reliable percentage.
The financial profile visible in recent years is clear: revenue has started to rise from a very small base, but costs still greatly exceed sales. In other words, the business is trying to prove that its material can move from promising lab and pilot use cases into regular industrial purchasing.
The income flow highlights the central issue: sales have improved from extremely low levels, but they remain tiny relative to overhead and commercialization spending. Selling, general, and administrative costs have been the biggest expense line, while research spending is meaningful but much smaller. That pattern is common in young materials companies trying to build demand before production reaches efficient scale.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Specialty Chemicals | |
| Market Cap ⓘ | $968.73M | |
| Beta ⓘ | 2.11 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 16.90 |
| P/B Ratio ⓘ | 21.12 | 1.65 |
| FCF Yield ⓘ | -1.17% | 5.76% |
| Dividend Yield ⓘ | N/A | 2.13% |
| EBIT / EV ⓘ | -1.38% | 6.30% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 140.70% | 11.10% |
| RPS Growth (5Y CAGR) ⓘ | 18.70% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -13.47% |
| BVPS Growth (5Y CAGR) ⓘ | 14.38% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | N/A | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.08% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | -38.64% | 9.26% |
| ROA (Latest) ⓘ | -52.02% | 4.91% |
| ROIC (5Y Median) ⓘ | N/A | 7.70% |
| ROA (5Y Median) ⓘ | -71.77% | 3.86% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 0.95 |
| Net Debt / Assets ⓘ | N/A | 13.69% |
| EBITDA / Interest ⓘ | N/A | 12.34 |
| Operating Margin (Latest) ⓘ | -13433.24% | 13.20% |
| Operating Margin (5Y Median) ⓘ | -62349.39% | 11.80% |
| Debt to Equity (Latest) ⓘ | N/A | 40.56% |
| Profit Margin (Latest) ⓘ | N/A | 6.43% |
| Free Cash Flow (Latest) ⓘ | -$11.32M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +4560.87% | +68.89% |
| 12M Return (excl. last month) ⓘ | +166.87% | +30.21% |
| 6M Return ⓘ | -46.53% | -4.16% |
| Price vs. 200-Day MA ⓘ | -34.58% | -1.27% |
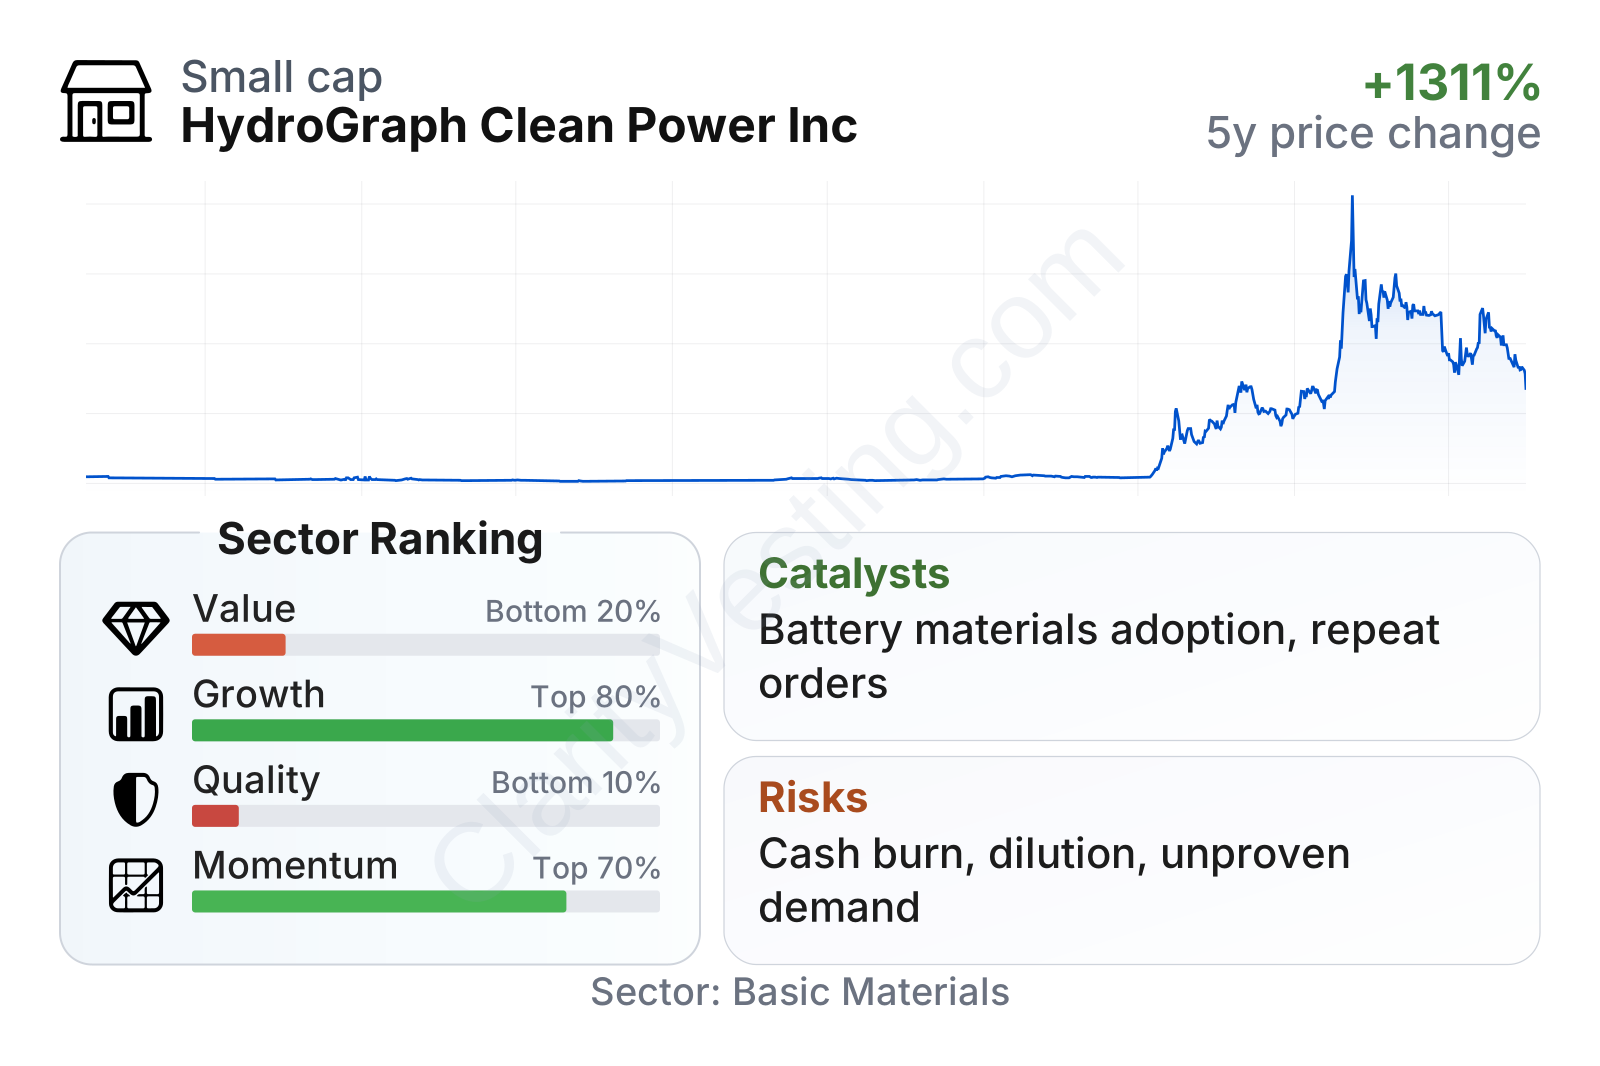
HydroGraph is now valued by the market like a high-expectation emerging technology company rather than a conventional chemicals producer. The company ranks strongly on growth versus its sector, but weakly on quality and value. That combination usually means the market is focusing on future potential instead of present profitability.
The stock’s historical path also shows how speculative the name has become. After trading at penny-stock levels for a long period, the shares surged sharply in 2025 and 2026. Even after some pullback, the business remains small in absolute size, while its trading volatility is very high, with a beta above 2. That matters because a long-term thesis here is likely to be driven by future contract wins, technology validation, and sentiment swings rather than by steady quarterly fundamentals.
Growth
HydroGraph operates in a sector that has genuine long-term tailwinds. Advanced carbon materials, battery additives, conductive materials, and performance enhancers for concrete and industrial products all sit within larger trends such as electrification, lighter materials, energy efficiency, and lower-emission manufacturing. Graphene has attracted attention for years because it can improve conductivity, strength, and durability, but the challenge across the industry has always been commercial scale, consistent quality, and cost-effective adoption.
HydroGraph’s strategy makes sense on paper. Instead of targeting a single end market, it is pursuing several application areas where a small amount of graphene can potentially improve a much larger product system. That can be attractive because even limited customer adoption may create high-value niche demand. The company has also emphasized production methods intended to produce cleaner and more uniform material, which could matter if customers need repeatable performance for batteries, composites, or construction materials.
Recent revenue growth has been extremely strong on a year-over-year basis, including growth well above the sector median. However, the base remains very small, so these percentages should be read carefully. A company can post triple-digit growth and still remain far from commercial scale. The more important question is whether the recent acceleration reflects repeat purchasing and broader customer adoption rather than one-off trial orders.
Cash generation remains the weak point. Free cash flow has stayed negative and has moved further below zero over time, showing that the company is still funding growth rather than harvesting it. For a business at this stage, the key catalyst is not just higher revenue, but a shift toward revenue that grows faster than operating costs.
A meaningful catalyst has emerged from the market’s broader interest in advanced materials linked to battery performance, data center power needs, and industrial efficiency. Recent company announcements have centered on commercial partnerships, product qualification efforts, and application development, especially in energy storage and construction-related uses. If those programs convert into recurring volumes, HydroGraph could move from proof-of-concept status toward a more credible specialty materials platform. That is the main growth argument.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


