Stock Analysis · Hochschild Mining PLC (HCHDF)
Overview
Hochschild Mining PLC is a precious-metals producer focused mainly on gold and silver. The group has deep roots in Latin America and has historically operated underground mines in Peru and Argentina, while also expanding through newer assets in Brazil and development-stage projects in Chile and Peru. Its business is relatively easy to understand: it extracts ore, processes it, and sells the resulting precious metals into global commodity markets.
The company’s revenue is driven mostly by metal sales rather than by long-term fixed-price contracts, which means results are strongly influenced by production volumes, ore grades, operating costs, and especially gold and silver prices. In recent years, Hochschild has become more gold-weighted than many people might expect from a company often associated with silver.
Based on recent company reporting, the main sources of revenue are approximately:
- Gold sales: about 70% to 80% of revenue. This includes ounces produced mainly from operations such as Inmaculada, San Jose, and Mara Rosa.
- Silver sales: about 20% to 30% of revenue. Silver remains strategically important, particularly from long-established underground assets.
- Other revenue: very limited. This can include by-product metals or other minor operating items, but it is not a major earnings driver.
At the asset level, revenue is concentrated in a relatively small number of mines. That concentration can be powerful when operations run well, because strong grades and higher metal prices can quickly lift profits. It also means one permitting issue, operational setback, or country-level disruption can materially affect the whole group.
The operating picture has improved sharply after a weak 2023. Revenue, gross profit, and operating income rebounded strongly in 2024 and then strengthened further in 2025, helped by better production and a much more favorable pricing environment. That recovery is important for long-term analysis because it shows the business still has meaningful operating leverage when mines perform and commodity prices cooperate.
The financial flow over the last several years shows a cyclical business with a pronounced rebound. After pressure in 2022 and an operating loss in 2023, margins recovered strongly in 2024 and expanded again in 2025, with revenue rising above $1.1 billion and net income moving back above $200 million. That pattern underlines how sensitive Hochschild is to both mine performance and precious-metals prices.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Other Precious Metals & Mining | |
| Market Cap ⓘ | $3.55B | |
| Beta ⓘ | 1.02 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 12.32 | 16.92 |
| P/B Ratio ⓘ | 4.25 | 1.66 |
| FCF Yield ⓘ | N/A | 5.83% |
| Dividend Yield ⓘ | 1.35% | 2.07% |
| EBIT / EV ⓘ | 0.79% | 6.38% |
| PEG ⓘ | 0.80 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 62.40% | 11.25% |
| RPS Growth (5Y CAGR) ⓘ | 9.83% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | 7.35% | -15.24% |
| BVPS Growth (5Y CAGR) ⓘ | -7.11% | 5.49% |
| Margin Growth (5Y Trend) ⓘ | 10.31% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | 11.67% | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | -4.66% | 5.91% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 9.59% |
| ROA (Latest) ⓘ | N/A | 4.92% |
| ROIC (5Y Median) ⓘ | 10.03% | 7.91% |
| ROA (5Y Median) ⓘ | 5.45% | 3.92% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.36 |
| Net Debt / EBIT (5Y Median) ⓘ | 1.08 | 1.69 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 0.93 |
| Net Debt / Assets ⓘ | N/A | 13.69% |
| EBITDA / Interest ⓘ | N/A | 12.38 |
| Operating Margin (Latest) ⓘ | N/A | 13.24% |
| Operating Margin (5Y Median) ⓘ | 20.99% | 11.82% |
| Debt to Equity (Latest) ⓘ | N/A | 40.30% |
| Profit Margin (Latest) ⓘ | 19.96% | 6.38% |
| Free Cash Flow (Latest) ⓘ | N/A | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +525.41% | +73.47% |
| 12M Return (excl. last month) ⓘ | +96.90% | +27.59% |
| 6M Return ⓘ | -21.96% | -4.02% |
| Price vs. 200-Day MA ⓘ | -14.54% | -0.65% |
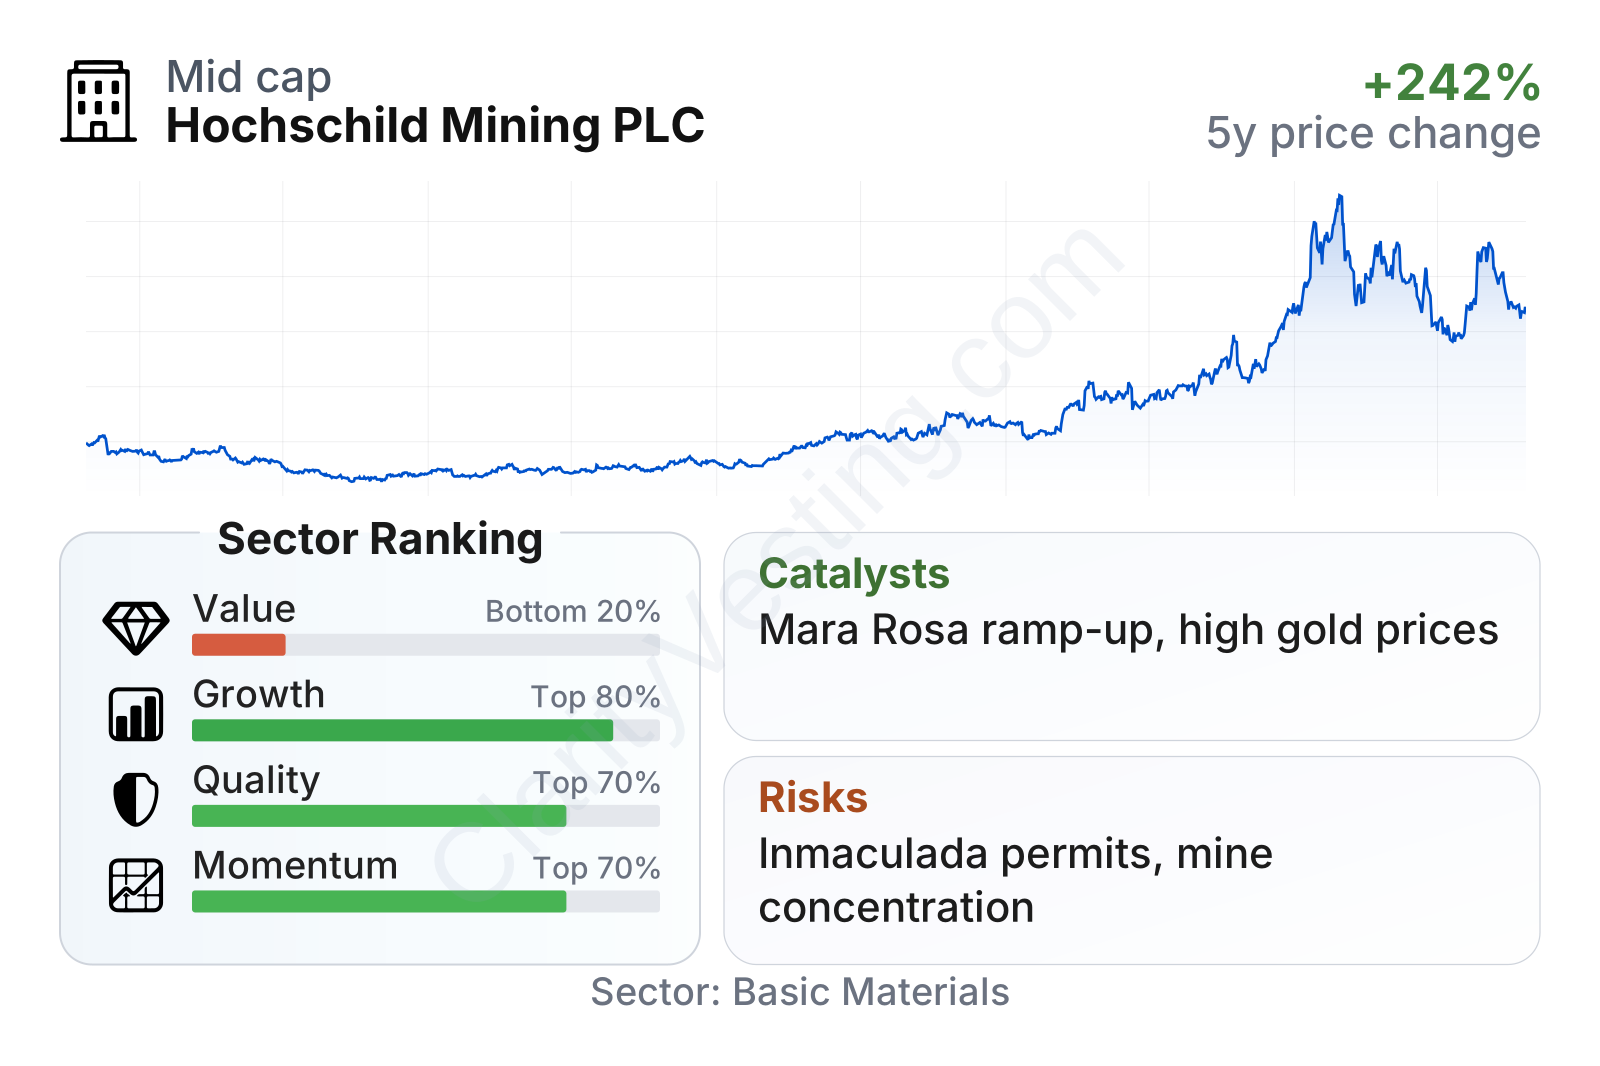
Hochschild sits in the mid-sized range for listed mining companies, with a market value around $3.5 billion and a share-price volatility profile close to the broader market. The stock’s longer-term performance has been exceptionally strong, with a multi-year return far ahead of the sector median, although the shorter-term picture is less smooth after a recent pullback from very elevated levels.
The overall financial profile is mixed in a way that is typical for cyclical miners emerging from a strong upswing. Growth metrics are clearly favorable: revenue growth, free-cash-flow growth, earnings growth, and margin improvement all compare well with much of the sector. Quality indicators also look solid, especially profitability and leverage discipline over a multi-year period, with profit margin materially above the sector median and debt metrics appearing manageable.
Valuation signals are less straightforward. The earnings multiple is below the sector median, which can make the shares look inexpensive on a plain P/E basis. However, the price-to-book ratio is much higher than the sector median, and the EBIT-to-enterprise-value measure points to a richer valuation than a simple earnings multiple suggests. In practical terms, the market seems to be assigning a premium to the company’s recent turnaround and exposure to higher precious-metals prices, even if not every valuation measure looks stretched.
Growth
Hochschild operates in a sector with durable long-term relevance. Gold remains important as a store of value, a reserve asset for central banks, and a hedge during periods of inflation, currency stress, or geopolitical uncertainty. Silver has additional industrial demand linked to electronics, solar applications, and electrification. That combination gives the company exposure to both defensive and industrial precious-metals themes.
The company’s strategy broadly makes sense for growth, but it is not a simple volume story. The key objective is to improve mine performance at its producing assets while extending mine life through exploration and bringing newer operations into the portfolio. This matters because mature underground mines need continuous reinvestment, drilling, and operational discipline to sustain output. Hochschild has long experience in this type of mining, which is an advantage in a specialized part of the sector.
A major growth catalyst has been the contribution from Mara Rosa in Brazil, which adds geographic diversification and increases the company’s gold exposure. That is strategically important because it reduces sole dependence on legacy assets in Peru and Argentina. At the same time, Inmaculada remains central to the investment case because it is one of the group’s most important mines and a major cash-generation engine when operating conditions are stable.
Another catalyst is the precious-metals price backdrop. Hochschild’s earnings are highly leveraged to stronger gold and silver prices. Because many operating costs do not move as fast as metal prices, price strength can expand margins quickly. The sharp earnings improvement seen from 2024 into 2025 illustrates this operating leverage.
Recent company updates have also pointed to continued progress in production and development activity, which supports the view that 2023 was a weak point rather than a permanent impairment. If the company keeps executing at current operations, extends reserves through drilling, and advances its development pipeline, it can continue growing cash generation even without a dramatic surge in production volumes.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


