Stock Analysis · Warrior Met Coal Inc (HCC)
Overview
Warrior Met Coal is a U.S. mining company focused on steelmaking coal, also called metallurgical or coking coal. This is not the same product as thermal coal used mainly for power generation. Warrior’s coal is sold to steel producers that use blast furnaces, making the company tied more closely to global steel demand than to electricity markets. Its core mining operations are in Alabama, and the company also operates related handling, preparation, and transportation assets needed to process and ship coal to customers around the world.
The business is relatively straightforward: mine high-quality steelmaking coal, process it, move it through rail and port infrastructure, and sell it under contract or into export markets. The company has historically emphasized premium low-volatility hard coking coal, a product category valued by blast furnace steelmakers because it helps improve coke strength and furnace efficiency.
Revenue is heavily concentrated in one main activity. Based on company disclosures, the mix is approximately:
- Steelmaking coal sales: about 95% to 99% of revenue. This includes premium hard coking coal shipped primarily to export steel customers, especially in Europe, Asia, and South America.
- Other mining-related revenue: about 1% to 5%. This can include transportation and handling-related items, ancillary sales, and smaller non-core revenue lines.
Geographically, Warrior is primarily an export-oriented producer rather than a domestic utility supplier. That gives it access to global pricing, but it also means results can swing with seaborne coal markets, steel production cycles, and trade flows.
The long-term attraction is easy to understand: a focused producer of a specialized coal product that remains important in conventional steelmaking, with a relatively small number of mines but a meaningful presence in the seaborne metallurgical coal market.
The long-term pattern shows a business that can generate very large profits when coal prices are favorable, but with margins that can compress quickly when pricing weakens or costs rise. Revenue remained above pre-2022 levels, yet earnings power has been far more volatile than sales, which is typical for commodity producers.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Coking Coal | |
| Market Cap ⓘ | $4.44B | |
| Beta ⓘ | 0.74 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 20.22 | 16.92 |
| P/B Ratio ⓘ | 1.94 | 1.66 |
| FCF Yield ⓘ | 0.14% | 5.83% |
| Dividend Yield ⓘ | 0.38% | 2.07% |
| EBIT / EV ⓘ | 5.14% | 6.38% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 71.30% | 11.25% |
| RPS Growth (5Y CAGR) ⓘ | 4.87% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | -32.03% | -15.24% |
| BVPS Growth (5Y CAGR) ⓘ | 24.49% | 5.49% |
| Margin Growth (5Y Trend) ⓘ | -17.43% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | 13.63% | 5.91% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 9.94% | 9.59% |
| ROA (Latest) ⓘ | 7.86% | 4.92% |
| ROIC (5Y Median) ⓘ | 15.40% | 7.91% |
| ROA (5Y Median) ⓘ | 10.56% | 3.92% |
| Net Debt / EBIT (Latest) ⓘ | -0.27 | 1.36 |
| Net Debt / EBIT (5Y Median) ⓘ | -0.61 | 1.69 |
| Net Debt / EBITDA (Latest) ⓘ | -0.15 | 0.93 |
| Net Debt / Assets ⓘ | -2.29% | 13.69% |
| EBITDA / Interest ⓘ | 33.68 | 12.38 |
| Operating Margin (Latest) ⓘ | 14.41% | 13.24% |
| Operating Margin (5Y Median) ⓘ | 22.33% | 11.82% |
| Debt to Equity (Latest) ⓘ | 10.30% | 40.30% |
| Profit Margin (Latest) ⓘ | 13.04% | 6.38% |
| Free Cash Flow (Latest) ⓘ | $6.13M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +84.74% | +73.47% |
| 12M Return (excl. last month) ⓘ | +41.19% | +27.59% |
| 6M Return ⓘ | -6.88% | -4.02% |
| Price vs. 200-Day MA ⓘ | -6.85% | -0.65% |
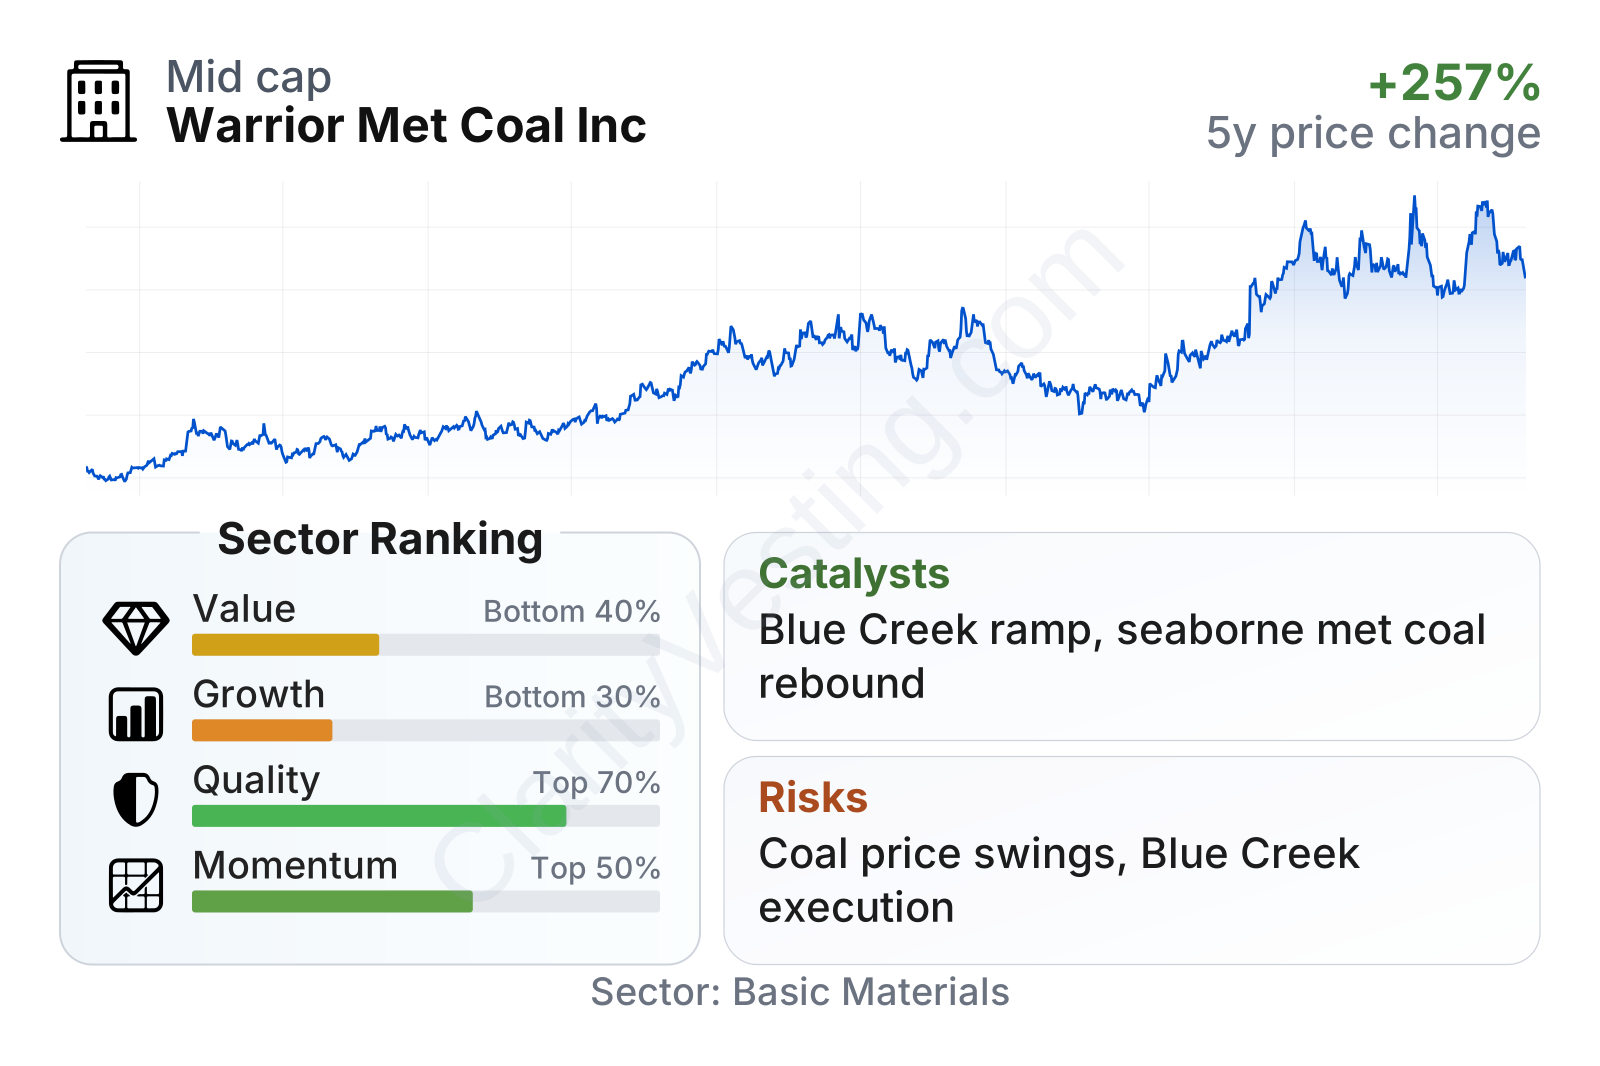
Warrior Met Coal is a mid-sized materials company with a stock that has been volatile but has delivered a strong multi-year price gain. In the current factor snapshot, quality looks stronger than value and growth. Returns on capital and assets remain above the sector median, and the balance sheet is notably cleaner than many peers. On the other hand, the valuation is not especially cheap on current earnings and cash flow, while the growth profile is mixed because recent recovery has followed a weaker earnings period.
Another important point is the company’s financial structure. Leverage is low, interest coverage is very strong, and net debt metrics are better than sector norms. That gives Warrior more flexibility than many commodity producers when markets soften.
Growth
Warrior operates in a sector with a mixed long-term outlook. On one side, steelmaking coal still plays an important role in blast furnace steel production, and many regions of the world continue to depend on that route. On the other side, long-term decarbonization trends create uncertainty because the steel industry is gradually exploring lower-emission production methods. That means Warrior is not in a classic secular growth industry, but it can still grow through production expansion, stronger realized pricing, and improved market share in premium seaborne coal.
A central part of that growth case is Blue Creek, Warrior’s major development project in Alabama. The company has described Blue Creek as a high-quality, low-volatility steelmaking coal mine designed to expand output and improve product mix over time. If executed well, this project could materially increase production capacity and extend mine life, which is especially important for a company that is otherwise concentrated in a small asset base.
Recent revenue growth has turned sharply upward again after a weak stretch in 2024 and 2025. That rebound suggests improving shipment volume, pricing, or both. Still, the earlier declines are a reminder that growth in this industry is rarely smooth. A single strong year does not erase the cyclical nature of the business.
Cash generation has been much less stable than revenue. Warrior produced very strong free cash flow earlier in the cycle, then slipped into negative territory as market conditions softened and capital spending increased. That pattern makes sense given the Blue Creek buildout: expansion projects often pressure cash flow before new production arrives. For long-term analysis, this means near-term cash numbers need to be read alongside the company’s construction timeline rather than in isolation.
One recent opportunity worth watching is the combination of recovering steelmaking coal pricing and Warrior’s ramp toward future production growth. If seaborne demand remains firm while Blue Creek progresses on schedule, Warrior could emerge from this investment phase with more capacity and a stronger earnings base than it had before the downturn.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


