Stock Analysis · Hudbay Minerals Inc (HBM)
Overview
Hudbay Minerals is a mining company focused mainly on copper, with meaningful exposure to gold and smaller contributions from zinc, silver, and molybdenum. Its operating base spans the Americas, with producing assets in Peru, Canada, and the United States, plus development projects intended to extend mine life and increase future output. In simple terms, Hudbay digs ore from its mines, processes it, and sells the resulting metals to industrial customers and traders.
For long-term analysis, the most important point is that Hudbay is not a broadly diversified mining giant. It is a mid-sized producer with a portfolio centered on copper and supported by by-product metals that can improve economics when prices are favorable. Copper matters most because it is used in power grids, electric vehicles, construction, and industrial equipment, while gold can help offset part of the cost base during weaker copper periods.
Based on recent company reporting, revenue is mainly generated from the following metal streams:
- Copper: approximately 55% to 65% of revenue. This is the core business and comes largely from copper concentrate and related sales from operations including Constancia in Peru and Snow Lake in Canada.
- Gold: approximately 25% to 35% of revenue. Gold is an important secondary contributor, especially because some Hudbay mines produce it alongside copper.
- Zinc: approximately 5% to 10% of revenue. Zinc exposure is smaller but still relevant, particularly from Canadian operations.
- Silver and molybdenum: generally a low-single-digit share each when disclosed, depending on production mix and realized prices.
What stands out in Hudbay’s business model is the improvement in operating scale over the last several years. Revenue has moved from roughly $1.5 billion in 2021 to more than $2.2 billion in 2025, while operating income and net income have improved much more sharply than sales. That suggests the company has benefited not only from stronger metal prices and volume mix, but also from better operating leverage.
The long-term pattern shows a business that has become materially more profitable: sales have risen steadily, gross profit has expanded, and operating income has improved from losses in 2021 to a very strong level by 2025. Interest expense has stayed relatively contained while earnings have grown, which has helped strengthen the financial profile.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Copper | |
| Market Cap ⓘ | $10.51B | |
| Beta ⓘ | 2.33 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 13.84 | 16.92 |
| P/B Ratio ⓘ | 2.23 | 1.66 |
| FCF Yield ⓘ | 2.35% | 5.83% |
| Dividend Yield ⓘ | 0.09% | 2.07% |
| EBIT / EV ⓘ | 9.91% | 6.38% |
| PEG ⓘ | 2.09 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 17.70% | 11.25% |
| RPS Growth (5Y CAGR) ⓘ | -0.75% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | 66.77% | -15.24% |
| BVPS Growth (5Y CAGR) ⓘ | 9.54% | 5.49% |
| Margin Growth (5Y Trend) ⓘ | 50.98% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | 135.97% | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | -2.44% | 5.91% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 15.41% | 9.59% |
| ROA (Latest) ⓘ | 9.66% | 4.92% |
| ROIC (5Y Median) ⓘ | 3.84% | 7.91% |
| ROA (5Y Median) ⓘ | 1.42% | 3.92% |
| Net Debt / EBIT (Latest) ⓘ | -0.02 | 1.36 |
| Net Debt / EBIT (5Y Median) ⓘ | 3.10 | 1.69 |
| Net Debt / EBITDA (Latest) ⓘ | -0.02 | 0.93 |
| Net Debt / Assets ⓘ | -0.34% | 13.69% |
| EBITDA / Interest ⓘ | 23.91 | 12.38 |
| Operating Margin (Latest) ⓘ | 49.35% | 13.24% |
| Operating Margin (5Y Median) ⓘ | 15.25% | 11.82% |
| Debt to Equity (Latest) ⓘ | 19.04% | 40.30% |
| Profit Margin (Latest) ⓘ | 27.48% | 6.38% |
| Free Cash Flow (Latest) ⓘ | $246.42M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +452.74% | +73.47% |
| 12M Return (excl. last month) ⓘ | +92.16% | +27.59% |
| 6M Return ⓘ | +0.64% | -4.02% |
| Price vs. 200-Day MA ⓘ | -3.31% | -0.65% |
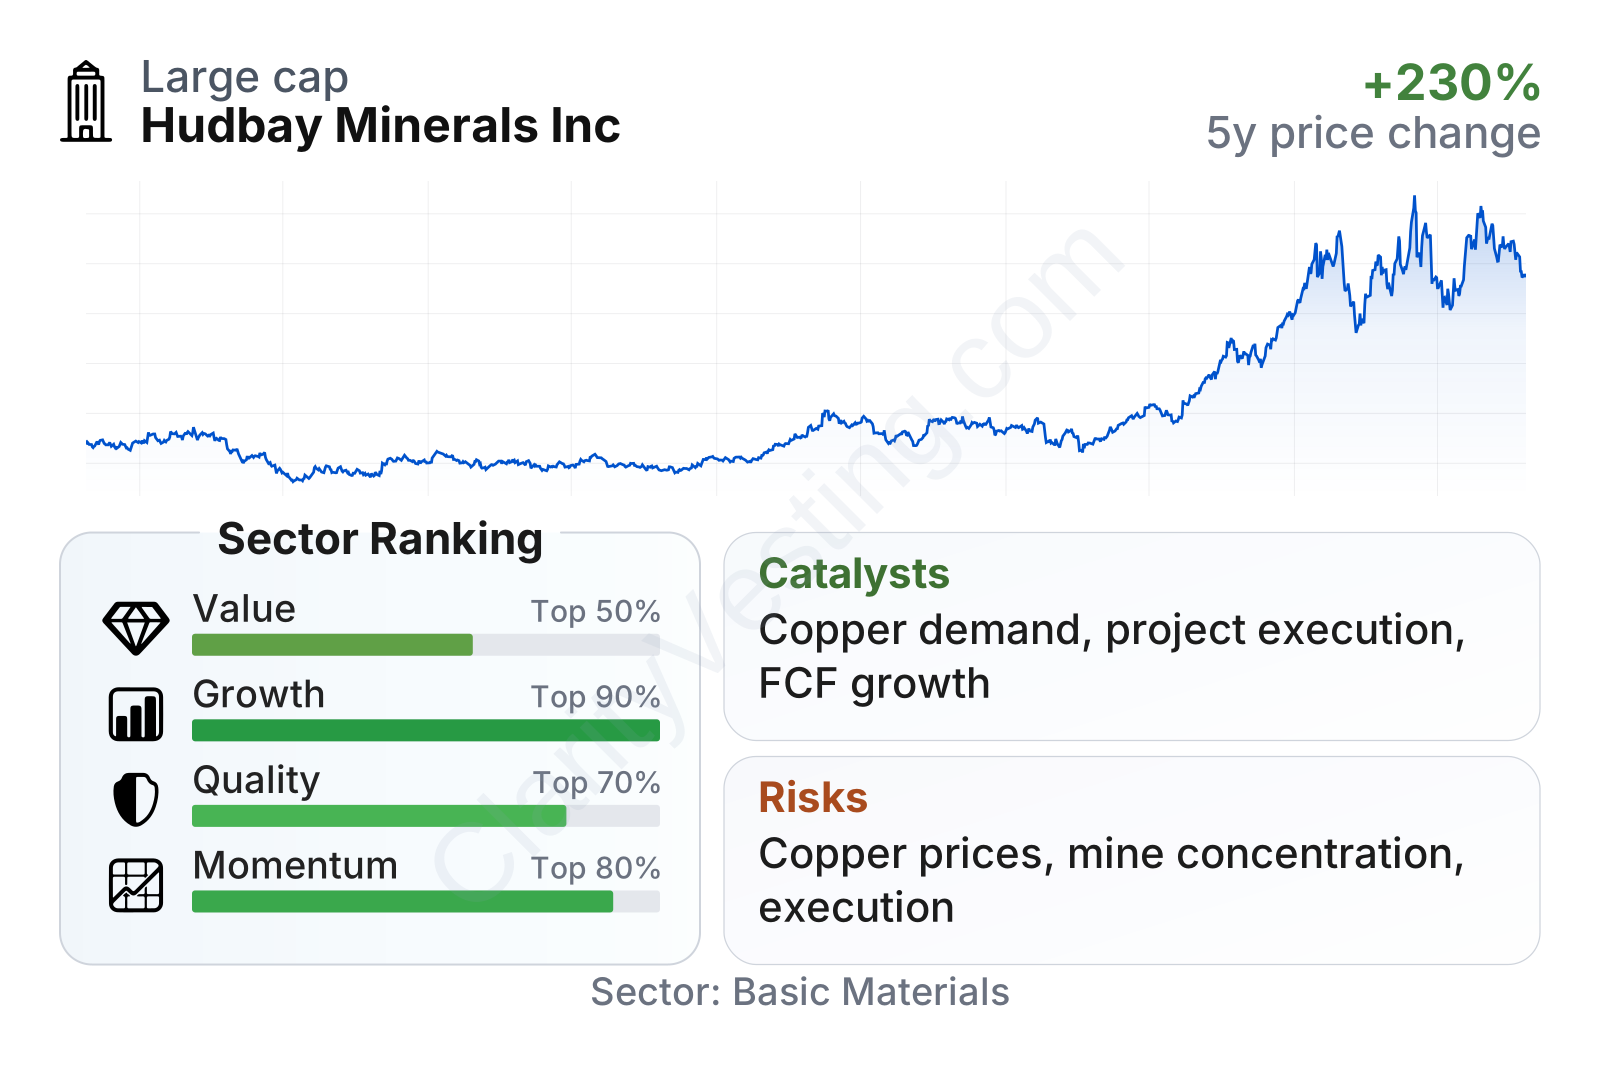
Hudbay is now a large mid-cap mining company with a market value around the low tens of billions of dollars, but its stock remains volatile, reflected by a beta above 2. The share price performance has been exceptionally strong over the last three years and over the last twelve months, placing it near the top of its sector on momentum. Growth metrics are also strong versus peers, while quality looks solid thanks to high recent returns on capital, strong interest coverage, and very low net debt. Value is more mixed: earnings-based valuation is not far from the sector median, but free cash flow yield and book value multiples suggest the market is already assigning a premium to the recent improvement.
Growth
Hudbay operates in a sector with attractive long-term demand support. Copper is one of the most important materials for electrification because it is essential for transmission lines, renewable energy systems, electric vehicles, motors, and charging infrastructure. That does not guarantee smooth results year to year, but it does provide a structural backdrop that is stronger than for many traditional bulk commodities.
The company’s strategy also makes sense on paper. Hudbay is trying to grow from a base of existing operations while extending mine life and developing new projects rather than relying only on large acquisitions. For a miner of this size, that is often a more disciplined path because it can limit integration risk and preserve balance sheet flexibility. Its portfolio gives it current production plus future optionality, especially if copper prices remain supportive.
Recent revenue trends have been uneven quarter to quarter, which is normal in mining because production timing, grades, shipments, and metal prices can all swing results. Still, the broader direction remains favorable: the latest year-over-year revenue growth is above 20%, clearly ahead of the sector median, and the company ranks near the top of its peer group on growth factors overall. That supports the view that Hudbay is currently in a stronger operating phase rather than merely benefiting from a one-off uplift.
Cash generation is another constructive point. Free cash flow has climbed from roughly $50 million in early 2022 to around $275 million more recently. That matters because miners need real cash, not just accounting profits, to fund expansion, manage debt, and absorb commodity downturns. Hudbay’s free cash flow trajectory suggests the business has become more self-funded.
As for catalysts, one of the clearest is project execution. If Hudbay continues to advance mine expansion and development plans on schedule and within budget, it can translate the favorable copper backdrop into higher production or longer reserve life. Another catalyst is simple but powerful: stronger copper and gold prices can have an outsized effect on earnings because many mining costs are relatively fixed once operations are running.
Recent company updates have also reinforced the growth case by highlighting ongoing development progress across its asset base and continued focus on expanding copper exposure. For a company already showing strong margin improvement, successful execution on those plans could keep the business in a favorable earnings phase.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


