Stock Analysis · Haitian International Holdings Limited (HAIIF)
Overview
Haitian International Holdings Limited is a Chinese industrial machinery manufacturer best known for injection molding machines. These are the large systems used to make plastic products at scale, from packaging and household goods to automotive parts, electronics components, medical items, and other molded parts. The company also sells related equipment and provides services tied to installation, maintenance, and spare parts.
Its business is centered on manufacturing productivity: helping customers produce plastic parts faster, more consistently, and with lower operating costs. Haitian has built a broad installed base in China and overseas, and that matters because machinery customers often return for replacement units, upgrades, auxiliary equipment, and after-sales support.
Based on the company’s annual reporting structure, revenue mainly comes from the following areas:
- Injection molding machines: approximately 90%+ of revenue in most years. This is the core business and includes standard, servo-hydraulic, and higher-end electric or hybrid machines used across general manufacturing, packaging, consumer goods, automotive, and medical applications.
- Components, services, and other equipment: approximately under 10% of revenue. This typically includes spare parts, service-related activities, and smaller adjacent equipment lines.
Geographically, the company has historically had meaningful exposure to both China and overseas markets, with exports playing an important role in balancing domestic demand cycles. That international reach is one of the reasons Haitian is followed as more than a purely local machinery producer.
The business model is fairly straightforward: design and manufacture machines, distribute them through a direct and dealer network, and defend profitability through scale, efficient production, and service support. For a long-term view, the key question is less about whether plastic processing remains necessary—which it almost certainly does in many end markets—and more about whether Haitian can keep its cost advantage and expand in higher-specification machine categories.
The earnings profile shows a cyclical but resilient industrial company. Revenue and profit fell in 2022, then recovered through 2023 and 2024, with 2025 continuing that upward trend. Margins have remained notably strong for a machinery manufacturer, suggesting the company has been able to protect pricing and production efficiency even as operating expenses increased.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Specialty Industrial Machinery | |
| Market Cap ⓘ | $4.79B | |
| Beta ⓘ | 1.12 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 10.00 | 22.45 |
| P/B Ratio ⓘ | 0.21 | 1.98 |
| FCF Yield ⓘ | N/A | 6.31% |
| Dividend Yield ⓘ | 23.97% | 1.96% |
| EBIT / EV ⓘ | N/A | 4.81% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 0.90% | 9.10% |
| RPS Growth (5Y CAGR) ⓘ | 2.58% | 7.75% |
| EPS Growth (5Y CAGR) ⓘ | -25.89% | -13.59% |
| BVPS Growth (5Y CAGR) ⓘ | 9.64% | 6.22% |
| Margin Growth (5Y Trend) ⓘ | 1.26% | 0.72% |
| FCF Growth (5Y CAGR) ⓘ | -0.05% | 10.98% |
| DPS Growth (5Y CAGR) ⓘ | 5.40% | 9.48% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 10.92% |
| ROA (Latest) ⓘ | N/A | 5.41% |
| ROIC (5Y Median) ⓘ | 12.93% | 9.21% |
| ROA (5Y Median) ⓘ | 9.87% | 4.94% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 2.07 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 2.28 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 1.43 |
| Net Debt / Assets ⓘ | N/A | 19.27% |
| EBITDA / Interest ⓘ | N/A | 9.53 |
| Operating Margin (Latest) ⓘ | N/A | 10.50% |
| Operating Margin (5Y Median) ⓘ | 23.05% | 10.27% |
| Debt to Equity (Latest) ⓘ | N/A | 65.48% |
| Profit Margin (Latest) ⓘ | 17.79% | 6.62% |
| Free Cash Flow (Latest) ⓘ | N/A | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +41.17% | +58.56% |
| 12M Return (excl. last month) ⓘ | -3.60% | +15.63% |
| 6M Return ⓘ | +7.14% | +4.19% |
| Price vs. 200-Day MA ⓘ | +6.95% | +0.93% |
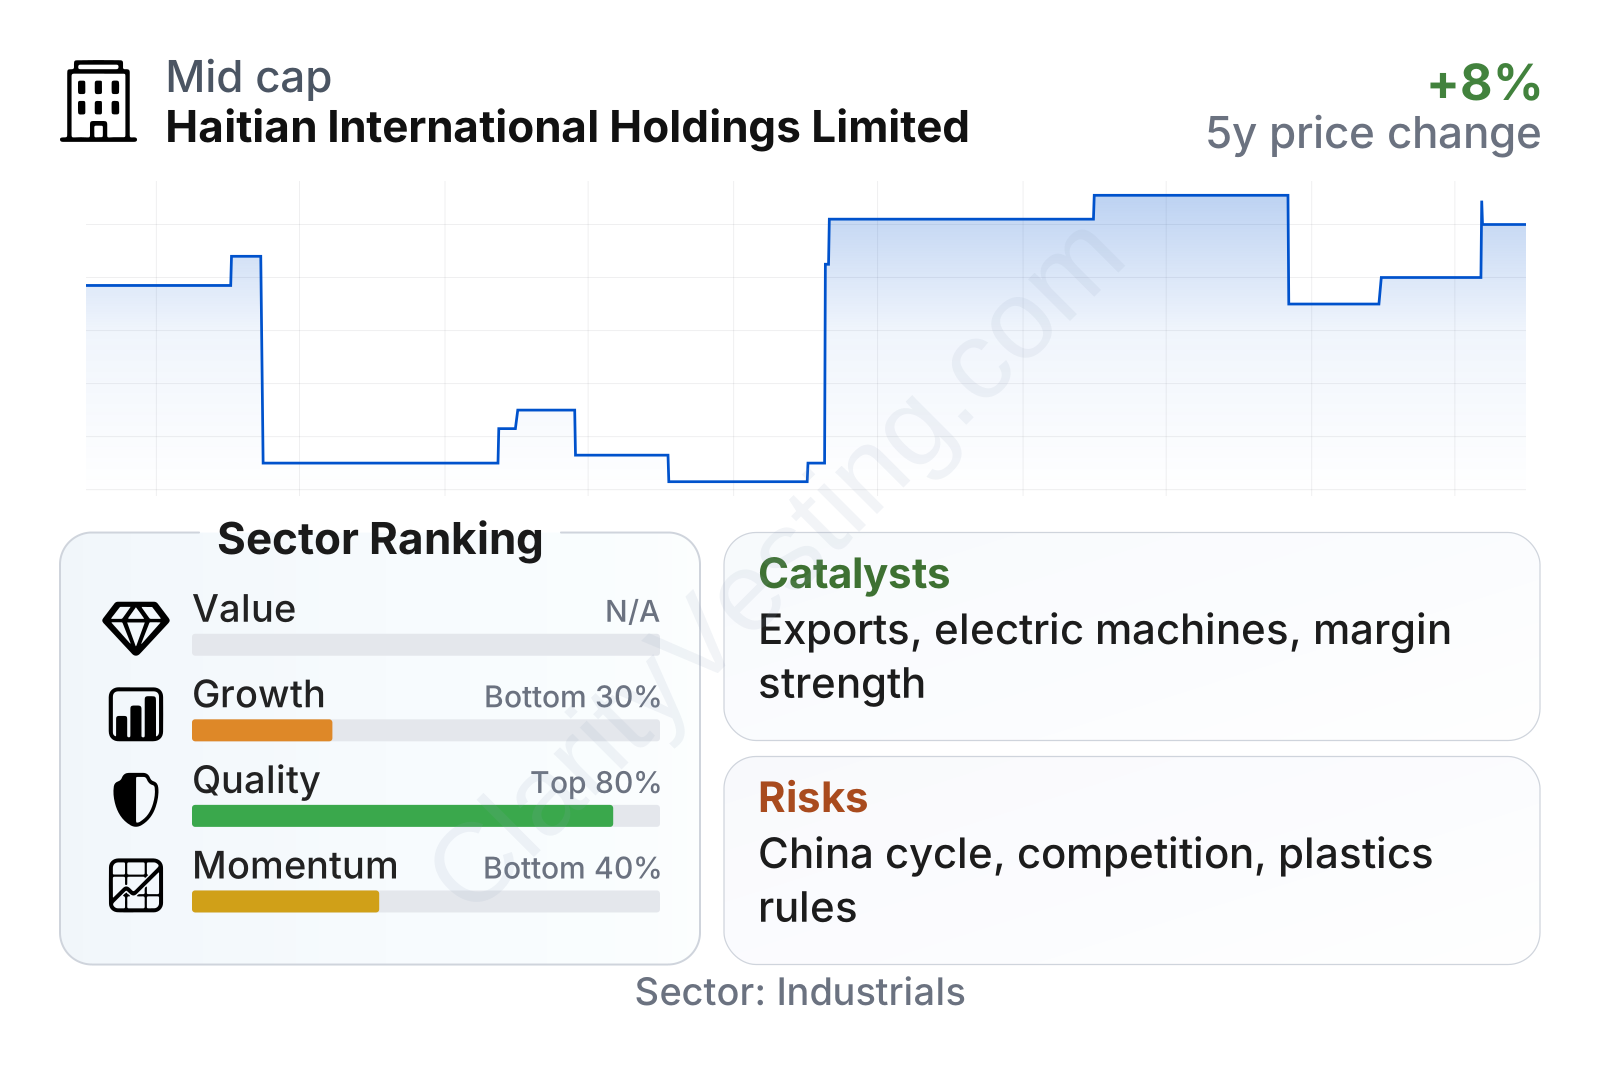
The market is valuing Haitian at earnings and book multiples that sit well below typical industrial machinery peers, while the company’s profitability looks stronger than the sector median on several measures. Profit margin is far ahead of the industry middle, and the long-term operating margin record is also unusually solid for this type of manufacturer. Balance-sheet quality appears favorable as well, with leverage metrics indicating a more conservative financial profile than many peers.
The weaker area is growth. Recent revenue expansion has been modest, five-year revenue-per-share growth has trailed the sector, and earnings growth over the last five years has been pressured by the cycle. Share-price performance has also lagged the broader machinery group over the medium term, even though the stock has shown some improvement in the last six months and is trading above its long-term trend line.
Growth
Haitian operates in a sector with durable long-term demand drivers, even if year-to-year results can be cyclical. Injection molding remains essential in packaging, consumer products, electrical goods, automotive components, medical applications, and many other manufacturing uses. Growth for the industry tends to come from automation, energy efficiency, replacement of older machinery, and production expansion in developing markets.
The company’s strategy makes sense in that context. Haitian has long emphasized scale manufacturing, cost competitiveness, and a broad product range. That positioning can work especially well when customers are cautious on capital spending and want reliable machines at attractive operating economics. It also gives Haitian a path to grow internationally, particularly in regions where local customers want lower-cost alternatives to premium European and Japanese brands.
A notable strategic opportunity is the shift toward more efficient and more precise machines, including electric and hybrid models. Environmental standards, labor costs, and product quality requirements are pushing many processors to modernize equipment. If Haitian continues moving customers from basic systems toward higher-specification platforms, it could support both revenue quality and margins over time.
Another constructive sign is the recent financial recovery. Revenue in 2024 moved back above the 2021 level, and 2025 extended that progress. Net income has also climbed back strongly from the 2022 dip. That does not automatically mean a new high-growth phase has started, but it does suggest Haitian remains well positioned when demand normalizes.
One more catalyst is its export footprint. Industrial demand is uneven across countries, so geographic diversification can help smooth domestic weakness. If manufacturing investment outside China improves, Haitian has a ready-made channel to capture that demand. Recent company materials have continued to emphasize international expansion, product upgrades, and technology development, which fit the current industry direction.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


