Stock Analysis · Granite Construction Incorporated (GVA)
Overview
Granite Construction Incorporated is a U.S. infrastructure contractor and construction materials producer. In simple terms, it helps build and improve roads, highways, bridges, airports, rail systems, water infrastructure, and other public works projects. The company has been operating for more than a century and is especially active in transportation and heavy civil construction, with a business model that combines project execution with ownership of construction materials resources such as aggregates and asphalt production.
Its revenue is mainly generated from construction services, with public-sector infrastructure as the core end market. Based on the company’s recent annual reporting structure, revenue sources can be understood approximately as follows:
- Construction segment: about 85% to 90% of revenue. This includes large infrastructure projects such as highways, streets, bridges, rail, airports, dams, site development, and water-related work performed through both fixed-price and alternative delivery contracts.
- Materials segment: about 10% to 15% of revenue. This includes sales of aggregates, asphalt concrete, liquid asphalt, and related construction materials supplied both to Granite projects and to outside customers.
That mix matters because construction brings scale and backlog visibility, while materials can improve margins when demand is strong and internal projects use Granite’s own supply network. Over the last several years, the company’s revenue has moved up from roughly $3.5 billion to more than $4.4 billion, while operating profit expanded much faster than sales through 2025, showing that execution had been improving before the latest margin setback visible in recent trailing metrics.
The business has recently shown a stronger conversion of revenue into gross profit and operating income than it did a few years ago. The broad pattern is favorable: sales have grown steadily, gross profit has widened, and net income had improved meaningfully through 2025, although the most recent trailing profitability measures suggest pressure has reappeared in 2026.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Engineering & Construction | |
| Market Cap ⓘ | $4.87B | |
| Beta ⓘ | 1.35 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 22.29 |
| P/B Ratio ⓘ | 6.86 | 1.98 |
| FCF Yield ⓘ | 9.70% | 6.26% |
| Dividend Yield ⓘ | 0.47% | 1.92% |
| EBIT / EV ⓘ | 0.05% | 4.83% |
| PEG ⓘ | 0.11 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 29.30% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | 2.15% | 7.76% |
| EPS Growth (5Y CAGR) ⓘ | 3.56% | -13.17% |
| BVPS Growth (5Y CAGR) ⓘ | 1.04% | 6.13% |
| Margin Growth (5Y Trend) ⓘ | 6.37% | 0.74% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 10.79% |
| DPS Growth (5Y CAGR) ⓘ | -4.77% | 9.41% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | -0.09% | 10.75% |
| ROA (Latest) ⓘ | -3.70% | 5.41% |
| ROIC (5Y Median) ⓘ | 7.04% | 9.37% |
| ROA (5Y Median) ⓘ | 3.57% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | 272.48 | 2.04 |
| Net Debt / EBIT (5Y Median) ⓘ | 1.13 | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | 4.52 | 1.39 |
| Net Debt / Assets ⓘ | 17.90% | 19.27% |
| EBITDA / Interest ⓘ | 2.72 | 9.58 |
| Operating Margin (Latest) ⓘ | 0.06% | 10.49% |
| Operating Margin (5Y Median) ⓘ | 3.16% | 10.30% |
| Debt to Equity (Latest) ⓘ | 230.15% | 64.82% |
| Profit Margin (Latest) ⓘ | -3.32% | 6.67% |
| Free Cash Flow (Latest) ⓘ | $471.91M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +216.66% | +67.77% |
| 12M Return (excl. last month) ⓘ | +6.09% | +12.05% |
| 6M Return ⓘ | -11.28% | 0.00% |
| Price vs. 200-Day MA ⓘ | -13.32% | +0.67% |
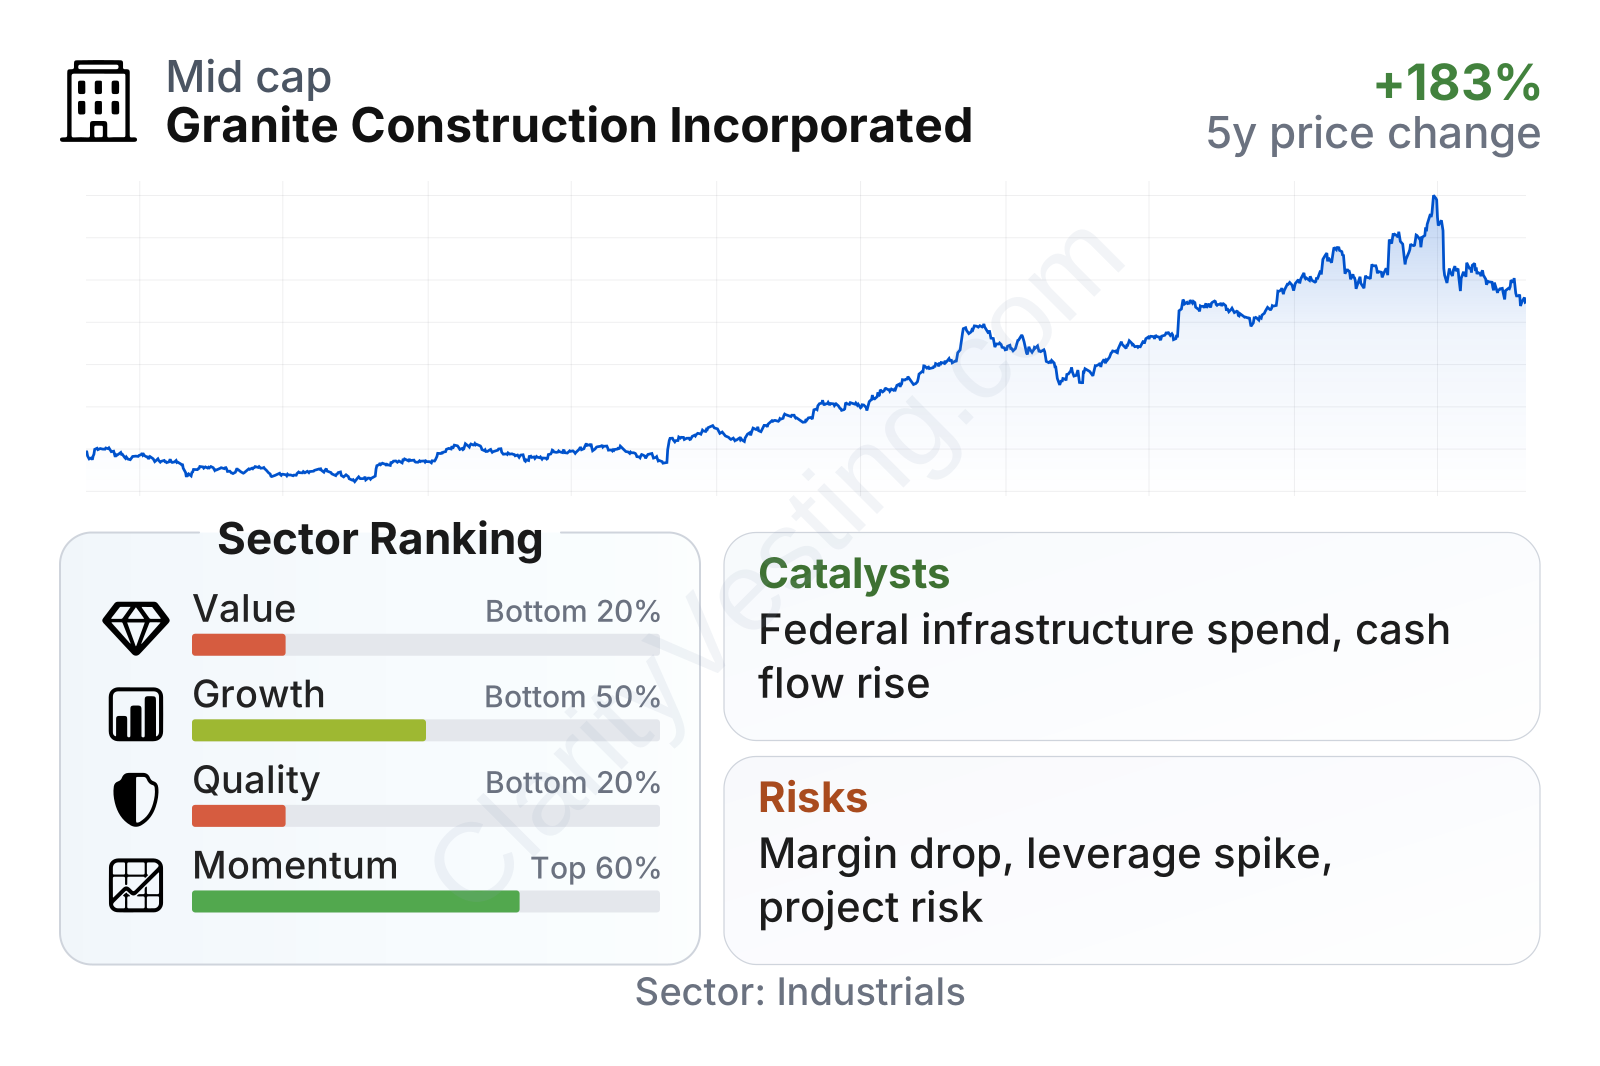
Granite is a mid-sized company within the industrials sector, and its share price has risen sharply over the last several years despite some recent cooling. The overall profile is mixed: growth and cash generation have improved, but current quality measures look weak because profitability has dropped sharply in the latest trailing period and leverage has climbed. The stock’s valuation metrics also send conflicting signals, with strong free cash flow yield and a low PEG ratio on one side, but expensive asset-based multiples and weak current earnings efficiency on the other.
Growth
Granite operates in a sector with real long-term support. U.S. infrastructure needs remain large, and public funding for highways, transit, water, and resilience projects continues to create a multiyear pipeline for contractors with scale, technical know-how, and agency relationships. This is not a fast-changing technology market, but it is a structurally important one with long project cycles and significant barriers to entry.
The company’s strategy is logical for that environment. Granite has been focusing on disciplined bidding, risk selection, and a better balance between large construction contracts and materials operations. That approach aims to avoid the low-margin or overly risky projects that have historically hurt many engineering and construction companies. Its integrated model also gives it some control over supply and cost on selected jobs, which can be helpful when materials markets are tight.
Recent sales momentum has been clearly stronger than the sector median. The latest year-over-year revenue growth is close to 29%, versus about 9% for the sector median, which indicates Granite is currently capturing more project volume than many peers. That said, the longer-term picture is less impressive than the latest surge: five-year revenue-per-share growth remains modest, so the current acceleration still needs to prove that it can last through a full cycle.
Cash generation has improved materially. Free cash flow moved from negative territory a few years ago to more than $300 million on a trailing basis by early 2026, and the latest table shows free cash flow yield above the sector median. For a construction company, that is an important positive sign because reported earnings can be volatile, while cash flow gives a better sense of how contracts, working capital, and capital spending are translating into actual financial flexibility.
A meaningful catalyst is the continued rollout of federally supported infrastructure programs in the United States, especially in transportation and water-related spending. Granite is well positioned in exactly those categories. Another catalyst is project mix: if the company keeps shifting toward contracts with better risk-sharing and toward markets where it has strong local density, margin recovery could become more durable than simple revenue growth alone suggests.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


