Stock Analysis · Getlink SE (GRPTF)
Overview
Getlink SE is the infrastructure group that operates the Channel Tunnel, the fixed rail link between France and the United Kingdom. Its core business is moving passengers and freight through that tunnel and managing the related rail infrastructure. In practical terms, the company earns money from shuttle trains carrying cars, buses, trucks, and other vehicles between Folkestone and Coquelles, and from charging railway operators that use the tunnel for high-speed passenger and freight services.
The business is relatively easy to understand: Getlink owns and runs a strategic transport asset with high barriers to entry. A new competing tunnel is highly unlikely, which gives the company a unique position in cross-Channel rail transport. It also has a smaller electricity interconnection activity that links the UK and France, adding some diversification beyond transport.
Based on recent annual reporting, Getlink’s revenue mix can be summarized approximately as follows:
- Shuttle services: about 55% to 60% — vehicle shuttle trains for passenger cars, coaches, and trucks using LeShuttle.
- Rail network access charges: about 25% to 30% — fees paid by rail operators such as Eurostar and freight train companies to use the tunnel infrastructure.
- ElecLink and other activities: about 10% to 15% — mainly electricity interconnection revenue and a smaller contribution from related services.
This mix matters because it shows that Getlink is not only exposed to tourism and passenger travel. Freight traffic and infrastructure access charges provide additional income streams, while the electricity link gives the group a business that is not directly tied to transport volumes.
The broader financial picture over the last few years shows a strong rebound from the pandemic period. Revenue and operating income rose sharply after 2021, and profitability stayed solid through 2024 and 2025, even as revenue moderated from the 2023 peak. Interest expense remains meaningful, which is typical for a long-life infrastructure operator financed with substantial debt.
The company’s recent pattern looks like a recovery followed by normalization rather than a straight-line growth surge. Revenue nearly doubled from 2021 to 2023, then eased in 2024 and 2025 while net income remained comparatively resilient, which suggests the underlying asset can still generate substantial earnings even when volumes are not at peak levels.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Railroads | |
| Market Cap ⓘ | $11.88B | |
| Beta ⓘ | 0.53 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 31.29 | 22.29 |
| P/B Ratio ⓘ | 4.87 | 1.98 |
| FCF Yield ⓘ | N/A | 6.26% |
| Dividend Yield ⓘ | 3.65% | 1.92% |
| EBIT / EV ⓘ | N/A | 4.83% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 10.80% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | 19.67% | 7.76% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -13.17% |
| BVPS Growth (5Y CAGR) ⓘ | 20.22% | 6.13% |
| Margin Growth (5Y Trend) ⓘ | 22.35% | 0.74% |
| FCF Growth (5Y CAGR) ⓘ | 30.08% | 10.79% |
| DPS Growth (5Y CAGR) ⓘ | 84.55% | 9.41% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 10.75% |
| ROA (Latest) ⓘ | N/A | 5.41% |
| ROIC (5Y Median) ⓘ | 5.45% | 9.37% |
| ROA (5Y Median) ⓘ | 3.47% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 2.04 |
| Net Debt / EBIT (5Y Median) ⓘ | 6.90 | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 1.39 |
| Net Debt / Assets ⓘ | 43.54% | 19.27% |
| EBITDA / Interest ⓘ | N/A | 9.58 |
| Operating Margin (Latest) ⓘ | N/A | 10.49% |
| Operating Margin (5Y Median) ⓘ | 33.83% | 10.30% |
| Debt to Equity (Latest) ⓘ | N/A | 64.82% |
| Profit Margin (Latest) ⓘ | 18.79% | 6.67% |
| Free Cash Flow (Latest) ⓘ | N/A | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +49.78% | +67.77% |
| 12M Return (excl. last month) ⓘ | +13.59% | +12.05% |
| 6M Return ⓘ | +1.86% | 0.00% |
| Price vs. 200-Day MA ⓘ | +15.36% | +0.67% |
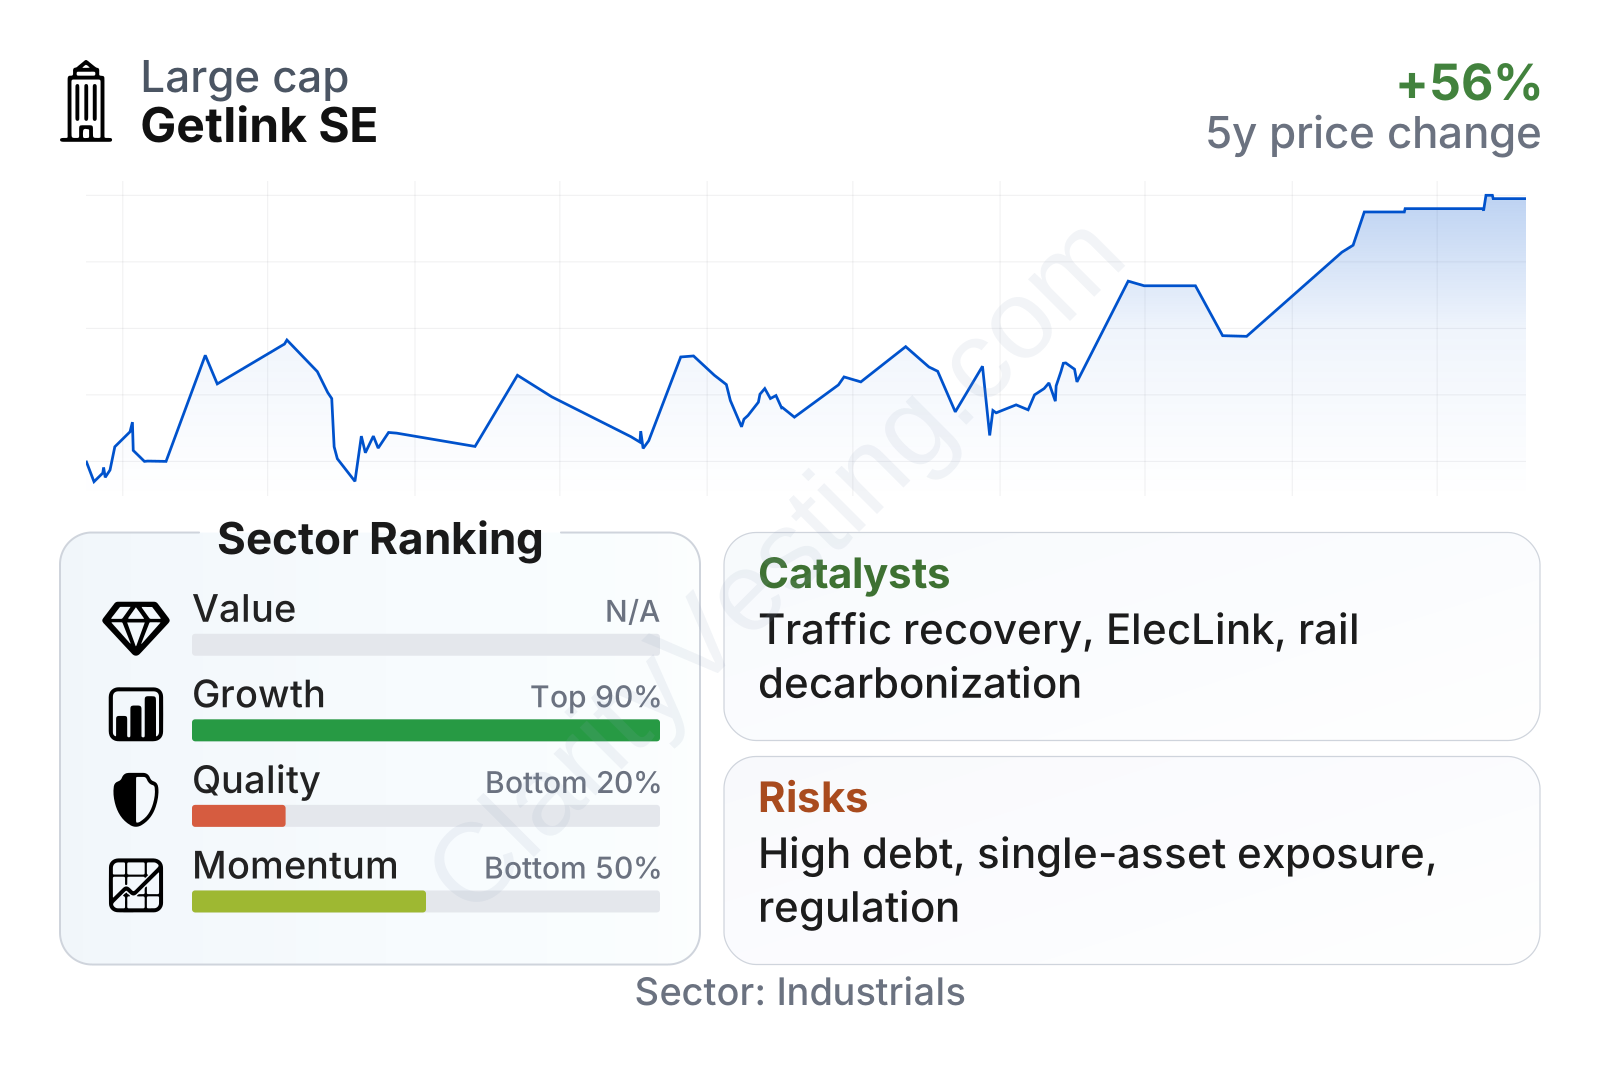
Getlink is a large infrastructure company with a stock that has been less volatile than the broader market, as reflected by its low beta. The share price trend over the last several years has been positive overall, with a clear recovery from earlier levels and a recent position above its long-term average, although medium-term performance has not outpaced the broader industrial sector.
The metrics table presents a mixed but understandable profile. Growth stands out: revenue, free cash flow, book value per share, and dividend growth over five years all compare well with sector norms. Profitability is also stronger than many peers on operating and net margin. On the other hand, returns on capital are weaker and leverage is clearly heavier than the sector median, which pulls down the quality profile. Valuation also looks fuller than the sector on earnings and book value multiples, while the dividend yield is above the sector median.
Growth
Getlink operates in a sector with long-term structural relevance rather than fast disruption-driven expansion. Cross-Channel transport is an essential corridor for trade and travel between the UK and continental Europe, and rail has an attractive position as a lower-emission mode of transport compared with many road and air alternatives. That gives the company exposure to trends such as supply-chain resilience, modal shift toward rail, and pressure to decarbonize transport.
The company’s strategy is logical for this type of asset. Management has focused on maximizing use of an existing infrastructure base, improving traffic mix, expanding freight relevance, and building adjacent activities such as electricity interconnection. For a mature infrastructure operator, that is often more important than aggressive expansion into unrelated businesses. The attraction here is not rapid reinvention, but disciplined monetization of a scarce, hard-to-replicate asset.
Recent financial trends support that view. Over five years, revenue per share growth has been far ahead of the sector median, and free cash flow growth has also been notably strong. Even though annual revenue has softened from the 2023 high, the longer-term picture still points to a business that has emerged from the pandemic in better shape than before, with stronger margins and a larger profit base.
One important catalyst is the continued normalization and potential expansion of rail traffic through the Channel Tunnel. Passenger volumes still have room to improve over time, while freight can benefit if shippers continue to favor reliable cross-Channel routes. Another catalyst is ElecLink, which adds earnings from energy infrastructure and gives Getlink a second strategic asset connecting the UK and France.
Recent company updates have also highlighted ongoing operational initiatives around capacity, service quality, and decarbonization. None of these changes transform the business overnight, but they fit well with the economics of an infrastructure owner: incremental volume gains and efficient asset use can have an outsized effect on profit and cash generation.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


