Stock Analysis · Generac Holdings Inc (GNRC)
Overview
Generac Holdings Inc. designs and manufactures power generation equipment and energy technology products. The company is best known for standby generators used at homes and businesses, but it has broadened into portable generators, light towers, industrial power systems, energy storage, and software used to manage distributed energy resources. Its business is closely tied to power reliability: when grid outages increase, or when homes and facilities want more resilience and backup capacity, demand for Generac’s products tends to rise.
Generac reports revenue through two operating segments. Based on recent annual reporting, the business mix is approximately:
- Domestic segment: about 84% of revenue — primarily residential standby generators, portable generators, home energy storage, clean energy products, and commercial & industrial products sold in the United States.
- International segment: about 16% of revenue — similar product categories sold outside the United States, including power generation equipment and related energy solutions.
Within products, residential backup power remains the company’s economic center, while commercial and industrial systems provide diversification. Revenue also includes accessories, parts, service-related items, and newer energy technology offerings such as battery storage, energy management devices, and virtual power plant capabilities. That mix matters because the traditional generator business is mature but still supported by long-term outage concerns, while the newer energy platform offers a possible second leg of expansion.
Over the last several years, the company’s revenue has stayed above $4 billion annually, but earnings have been much more volatile. Gross profit recovered after the 2023 downturn, yet operating income and net income have remained less stable as Generac continued spending on product development, sales infrastructure, and expansion into newer energy categories.
The long-term pattern shows a business that scaled rapidly in 2021 and 2022, then normalized. Sales have held relatively firm, but profit conversion has become less efficient than at the 2021 peak, suggesting that future returns will depend less on simple demand growth and more on execution, mix improvement, and cost discipline.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Specialty Industrial Machinery | |
| Market Cap ⓘ | $11.49B | |
| Beta ⓘ | 1.92 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 44.74 | 22.29 |
| P/B Ratio ⓘ | 4.20 | 1.98 |
| FCF Yield ⓘ | 3.30% | 6.26% |
| Dividend Yield ⓘ | N/A | 1.92% |
| EBIT / EV ⓘ | 3.11% | 4.83% |
| PEG ⓘ | 0.56 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 10.60% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | 5.12% | 7.76% |
| EPS Growth (5Y CAGR) ⓘ | -14.87% | -13.17% |
| BVPS Growth (5Y CAGR) ⓘ | 6.49% | 6.13% |
| Margin Growth (5Y Trend) ⓘ | -12.98% | 0.74% |
| FCF Growth (5Y CAGR) ⓘ | -2.86% | 10.79% |
| DPS Growth (5Y CAGR) ⓘ | -69.92% | 9.41% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 7.92% | 10.75% |
| ROA (Latest) ⓘ | 4.54% | 5.41% |
| ROIC (5Y Median) ⓘ | 10.16% | 9.37% |
| ROA (5Y Median) ⓘ | 6.38% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | 3.09 | 2.04 |
| Net Debt / EBIT (5Y Median) ⓘ | 2.60 | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | 2.23 | 1.39 |
| Net Debt / Assets ⓘ | 21.63% | 19.27% |
| EBITDA / Interest ⓘ | 8.31 | 9.58 |
| Operating Margin (Latest) ⓘ | 9.12% | 10.49% |
| Operating Margin (5Y Median) ⓘ | 11.62% | 10.30% |
| Debt to Equity (Latest) ⓘ | 52.60% | 64.82% |
| Profit Margin (Latest) ⓘ | 5.82% | 6.67% |
| Free Cash Flow (Latest) ⓘ | $379.25M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +129.85% | +67.77% |
| 12M Return (excl. last month) ⓘ | +12.44% | +12.05% |
| 6M Return ⓘ | -5.01% | 0.00% |
| Price vs. 200-Day MA ⓘ | -6.39% | +0.67% |
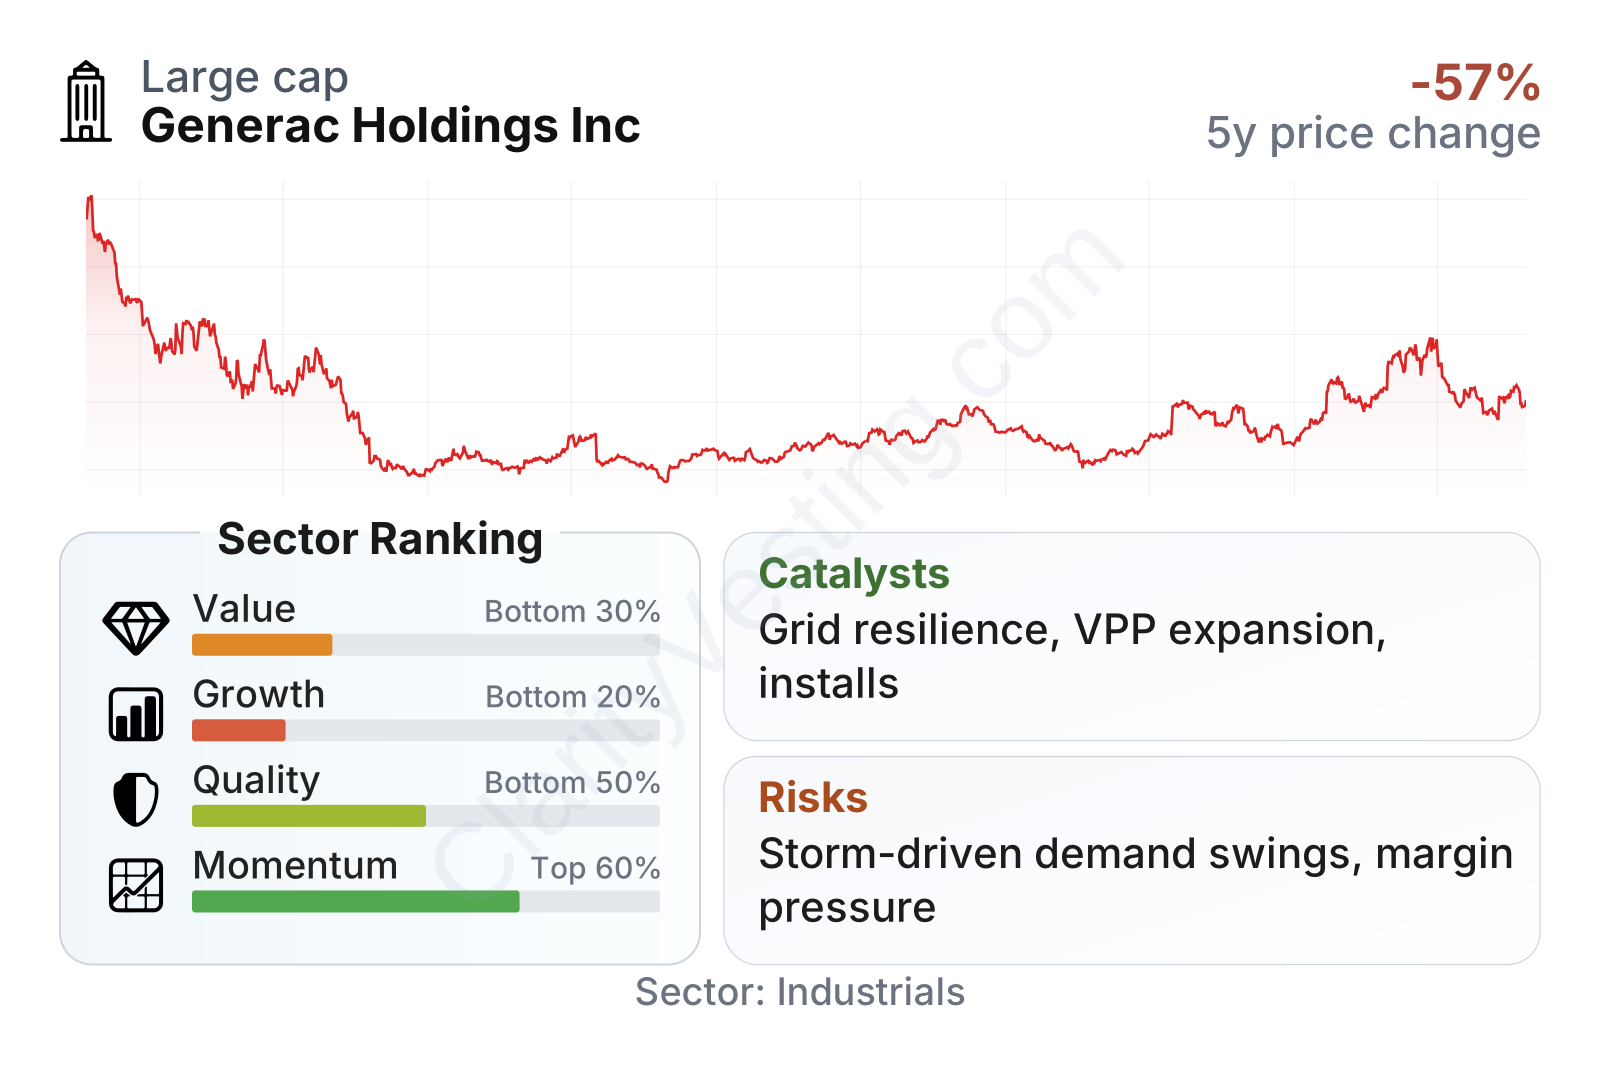
Generac is a mid-to-large industrial company with a stock that has been notably volatile, reflected in a beta close to 1.9. The factor profile is mixed: valuation metrics look expensive versus the sector median, quality sits around the middle to lower half, and growth ranks weakly on a multi-year basis even though recent revenue growth has improved. The company still generates positive free cash flow, but cash flow yield and earnings-based valuation multiples suggest the market is already pricing in a meaningful recovery.
The share price history also highlights how cyclical sentiment can be around this company. After peaking in 2021, the stock fell sharply through 2022, then rebuilt momentum in a choppy way before rebounding strongly into 2026. That pattern fits a business whose earnings outlook can change quickly when demand, inventory conditions, weather events, and margin expectations shift.
Growth
Generac operates in a sector with credible long-term demand drivers. Aging electric grids, more frequent severe weather, wildfire-related shutoffs, electrification of homes, and the need for resilience at small businesses and critical sites all support demand for backup power. On top of that, distributed energy resources such as batteries, smart controls, and grid services create a broader market than generators alone. In simple terms, the company is no longer tied only to emergency backup equipment; it is trying to become a wider residential and light commercial energy platform.
The strategy is coherent. Generac has expanded from its core generator franchise into adjacent categories including residential battery storage, energy management devices, EV-related home power coordination, and software that can aggregate customer assets into virtual power plant programs. This matters because grid instability can create demand not only for backup generators, but also for systems that reduce peak usage, shift electricity consumption, and provide flexible capacity back to utilities.
Recent sales trends show that the business has moved beyond the sharp contraction seen in 2023. Revenue growth turned positive again during 2024, weakened late in 2025, and then accelerated back into low double-digit growth in the first half of 2026. That recovery is important, but it also shows how uneven demand can be. The company is still working through a business that can swing between periods of exceptionally strong orders and periods of normalization.
Cash generation has also remained positive overall, although not in a straight line. Free cash flow improved materially from the weak 2023 level, then came down from a high point reached in 2025. Even after that pullback, the business continues to produce meaningful cash, which gives management room to invest in product development, manufacturing, and selective acquisitions without depending entirely on external financing.
A notable catalyst is the company’s exposure to grid modernization and utility partnerships. Generac has been building software and hardware capabilities that allow fleets of home batteries and flexible devices to participate in utility demand-response or virtual power plant programs. If these programs scale, they could gradually make the revenue base less seasonal and less dependent on storm-driven generator purchases. Another catalyst is the replacement cycle: a large installed base of standby generators creates ongoing opportunities for accessories, service, and eventual equipment upgrades.
Recent company updates have also pointed to continued progress in residential energy technology and commercial & industrial offerings. Those areas are still smaller than the core home standby business, but they represent some of the clearest avenues for faster growth if execution improves and adoption broadens.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


