Stock Analysis · Genscript Biotech Corporation (GNNSF)
Overview
GenScript Biotech Corporation is a life sciences company focused on tools, services, and manufacturing support used in drug discovery and biotechnology research. In simple terms, it helps pharmaceutical and biotech customers design genes, make biological research materials, and produce advanced therapies. The group has historically combined a steadier research-tools business with higher-growth but more volatile cell and gene therapy activities.
Its business mix has changed in an important way. In late 2024, GenScript completed the deconsolidation of Legend Biotech, the CAR-T therapy company it had incubated and previously consolidated in its accounts. That means GenScript’s reported revenue and profit profile after that point became much more centered on its core life science services and manufacturing platform rather than directly reflecting Legend’s commercial CAR-T sales.
Based on the company’s recent segment disclosures, revenue is mainly generated from the following activities:
- Life-science services and products: about 55% to 65% of revenue in the current post-deconsolidation structure. This includes gene synthesis, peptide services, antibody development, protein and reagent offerings, and broader contract research support used by laboratories and drug developers.
- Cell and gene therapy contract development and manufacturing: about 25% to 35%. This activity is tied mainly to GenScript ProBio, which helps customers develop and manufacture plasmids, viral vectors, mRNA, proteins, and other materials used in advanced therapies.
- Industrial synthetic biology and other operations: about 5% to 10%. This includes enzyme and synthetic biology applications aimed at industrial customers.
- Other income tied to portfolio holdings or legacy consolidation effects: variable. This can materially affect reported profit even when it is not a core recurring source of operating revenue.
The financial flow over the last several years shows two distinct phases: a long investment period with heavy research spending and losses, followed by a sharp change in reported profitability after the Legend Biotech deconsolidation and related accounting effects. Revenue itself has also been uneven, which matters because GenScript is not a simple one-line growth business.
The business model remains appealing because it sits across multiple steps of biotech development, from early research to manufacturing support. That gives GenScript more than one way to participate in industry growth, but it also makes the accounts harder to read because reported earnings can be influenced by ownership changes and non-operating items.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Biotechnology | |
| Market Cap ⓘ | $12.60B | |
| Beta ⓘ | 0.98 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 24.06 |
| P/B Ratio ⓘ | 3.21 | 3.08 |
| FCF Yield ⓘ | 1.88% | 3.07% |
| Dividend Yield ⓘ | N/A | 2.05% |
| EBIT / EV ⓘ | 4.01% | 0.63% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | -22.10% | 7.50% |
| RPS Growth (5Y CAGR) ⓘ | 15.21% | 8.70% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -18.20% |
| BVPS Growth (5Y CAGR) ⓘ | 37.18% | 3.95% |
| Margin Growth (5Y Trend) ⓘ | N/A | -0.58% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 0.88% |
| DPS Growth (5Y CAGR) ⓘ | 188.30% | 6.80% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 3.29% |
| ROA (Latest) ⓘ | 49.17% | 3.02% |
| ROIC (5Y Median) ⓘ | -16.56% | 4.75% |
| ROA (5Y Median) ⓘ | -9.49% | 1.93% |
| Net Debt / EBIT (Latest) ⓘ | 0.27 | 1.33 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.83 |
| Net Debt / EBITDA (Latest) ⓘ | 0.21 | 0.99 |
| Net Debt / Assets ⓘ | 2.64% | 5.33% |
| EBITDA / Interest ⓘ | 13.52 | 9.63 |
| Operating Margin (Latest) ⓘ | 33.28% | 9.25% |
| Operating Margin (5Y Median) ⓘ | -38.45% | 7.80% |
| Debt to Equity (Latest) ⓘ | 8.84% | 28.99% |
| Profit Margin (Latest) ⓘ | -75.35% | 3.60% |
| Free Cash Flow (Latest) ⓘ | $236.92M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +116.24% | +37.48% |
| 12M Return (excl. last month) ⓘ | +111.36% | +20.85% |
| 6M Return ⓘ | +301.41% | +9.73% |
| Price vs. 200-Day MA ⓘ | +161.44% | +4.69% |
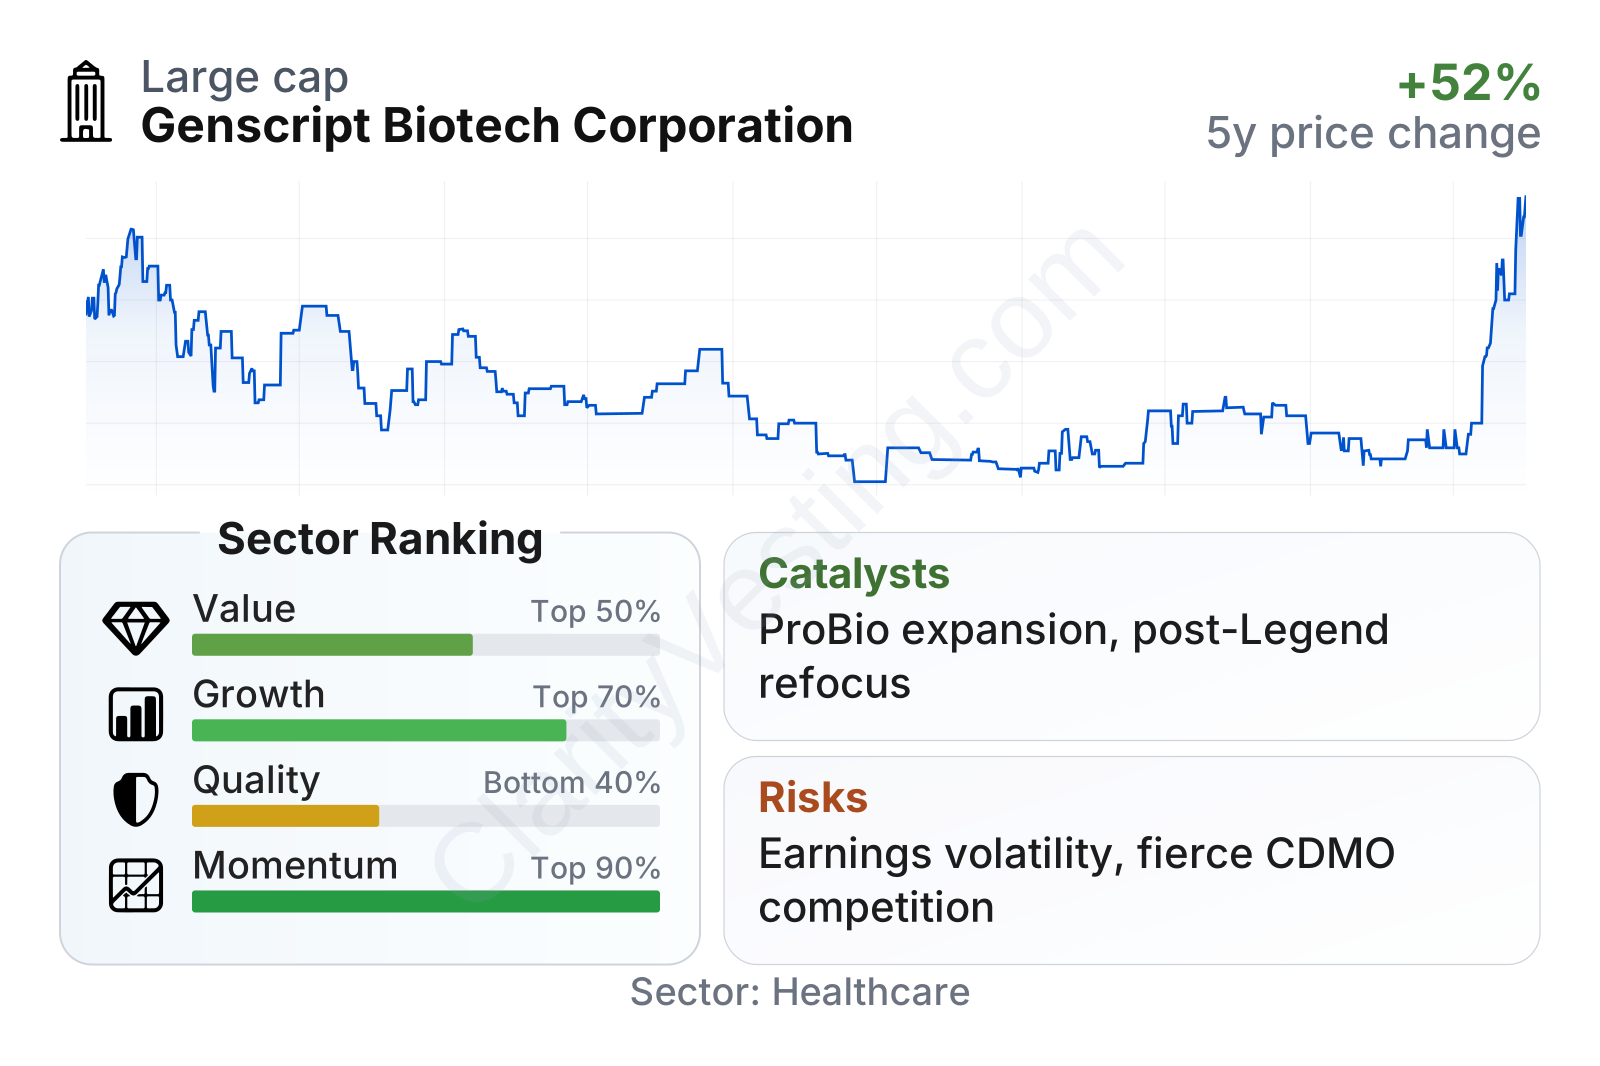
GenScript is a large company by biotech standards, with a market value in the multi-billion-dollar range and share-price volatility close to the broader market. The table points to a mixed profile. On growth, the longer-term picture is stronger than the latest year, with five-year revenue per share growth above the sector median, while the most recent year shows a sharp revenue decline of about 22%, well below the sector’s positive median. On quality, current operating margin is strong at about 33%, but bottom-line profitability is distorted by large swings, which is why the quality ranking still lands below the stronger part of the sector. Balance-sheet pressure looks limited, with debt to equity around 9% and net debt ratios comfortably below sector medians. Momentum is clearly strong, with recent price performance far ahead of most healthcare peers.
Growth
GenScript operates in parts of healthcare that still have favorable long-term demand drivers. Biopharma research outsourcing, biologics development, and cell and gene therapy manufacturing all benefit from a larger pipeline of complex medicines. Even when funding conditions cool temporarily, drug developers still need specialized partners for gene construction, plasmids, vectors, analytical work, and process development. That gives the company exposure to sectors that are structurally growing over a multi-year horizon.
The company’s strategy also makes industrial sense. Its traditional research-tools platform can bring recurring demand from a wide customer base, while GenScript ProBio offers a path into higher-value manufacturing relationships. If that manufacturing arm scales well, it can deepen customer ties because switching providers in regulated biologics work is not easy once a program advances.
The main issue is that growth has not been smooth. The latest annual comparison is weak, with revenue down by roughly 22%. That needs to be read carefully, because accounting perimeter changes after the Legend deconsolidation make year-to-year comparisons less straightforward. Looking over a longer window, revenue per share has still compounded at roughly 15% annually over five years, which is materially above the sector median. In other words, the company has demonstrated expansion over time, but reported growth can look erratic from one year to the next.
A major catalyst is the company’s increased focus on GenScript ProBio and on the broader outsourced manufacturing market for advanced therapies. Industry demand for plasmid DNA, viral vectors, and related biologic materials could support future growth if customer programs continue moving into later-stage development. Another positive element is that GenScript’s core life-science business remains connected to a large and diversified global research customer base, reducing dependence on any single product launch.
Recent corporate developments also matter. The separation from Legend Biotech has simplified the investment case to some extent: GenScript is now more exposed to its core operating businesses rather than to the accounting and valuation impact of a listed subsidiary. That may improve visibility over time, especially if management can show that the remaining businesses can produce more stable operating profit and cash flow on their own.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


