Stock Analysis · Greencore Group plc (GNCGF)
Overview
Greencore Group plc is a convenience food manufacturer focused mainly on the United Kingdom. It supplies supermarkets, grocery retailers, and foodservice customers with ready-to-eat and easy-to-prepare products such as sandwiches, salads, sushi, chilled meals, soups, sauces, quiches, and desserts. The business is built around high-volume fresh food production, short shelf life, and close relationships with large retail customers that need dependable daily supply.
The company’s revenue is heavily concentrated in chilled convenience foods sold in the UK and Ireland, with the UK representing the clear center of the business. Based on company reporting in recent annual results and trading updates, the revenue mix is best understood as follows:
- Food to Go and salads: approximately 45% to 55% of revenue. This includes sandwiches, wraps, rolls, sushi, and prepared salads sold through major retailers and convenience channels.
- Other chilled convenience categories: approximately 45% to 55% of revenue. This includes ready meals, soups, sauces, quiches, pickles, chilled snacks, desserts, and related prepared foods.
- Geographic exposure: the UK accounts for the vast majority of sales, likely above 90%, with Ireland and a smaller set of adjacent activities making up the balance.
Greencore’s business model is straightforward: it manufactures private-label products for retailers rather than relying primarily on consumer-facing brands. That gives it scale and recurring volume, but it also means retailer relationships, efficiency, and execution matter more than brand power.
The flow of revenue into profit shows a business with large input costs but improving operating discipline. Over the last four reported fiscal years in the figures shown, revenue moved from roughly £1.7 billion to nearly £1.95 billion, while operating income and net income improved faster than sales. That points to better plant utilization, mix, and cost control, even though food manufacturing remains a relatively low-margin activity.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Consumer Defensive | |
| Industry | Packaged Foods | |
| Market Cap ⓘ | $2.82B | |
| Beta ⓘ | 0.85 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 117.33 | 17.88 |
| P/B Ratio ⓘ | 1.39 | 1.29 |
| FCF Yield ⓘ | 5.44% | 12.39% |
| Dividend Yield ⓘ | 0.74% | 2.85% |
| EBIT / EV ⓘ | N/A | 6.43% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 43.00% | 4.10% |
| RPS Growth (5Y CAGR) ⓘ | 13.36% | 6.18% |
| EPS Growth (5Y CAGR) ⓘ | 19.48% | -13.59% |
| BVPS Growth (5Y CAGR) ⓘ | 6.91% | 3.20% |
| Margin Growth (5Y Trend) ⓘ | 1.92% | -0.15% |
| FCF Growth (5Y CAGR) ⓘ | 18.25% | 4.10% |
| DPS Growth (5Y CAGR) ⓘ | -3.13% | 6.79% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 14.80% | 12.34% |
| ROA (Latest) ⓘ | 2.45% | 6.30% |
| ROIC (5Y Median) ⓘ | 7.55% | 10.49% |
| ROA (5Y Median) ⓘ | 2.72% | 5.44% |
| Net Debt / EBIT (Latest) ⓘ | 4.32 | 1.96 |
| Net Debt / EBIT (5Y Median) ⓘ | 3.05 | 2.35 |
| Net Debt / EBITDA (Latest) ⓘ | 2.59 | 1.38 |
| Net Debt / Assets ⓘ | 24.86% | 21.51% |
| EBITDA / Interest ⓘ | 7.18 | 9.46 |
| Operating Margin (Latest) ⓘ | 5.23% | 8.87% |
| Operating Margin (5Y Median) ⓘ | 3.93% | 9.53% |
| Debt to Equity (Latest) ⓘ | 80.03% | 72.35% |
| Profit Margin (Latest) ⓘ | 0.30% | 5.40% |
| Free Cash Flow (Latest) ⓘ | $153.26M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +226.74% | +20.92% |
| 12M Return (excl. last month) ⓘ | +2.92% | +2.13% |
| 6M Return ⓘ | -13.73% | +1.26% |
| Price vs. 200-Day MA ⓘ | +2.65% | +1.39% |
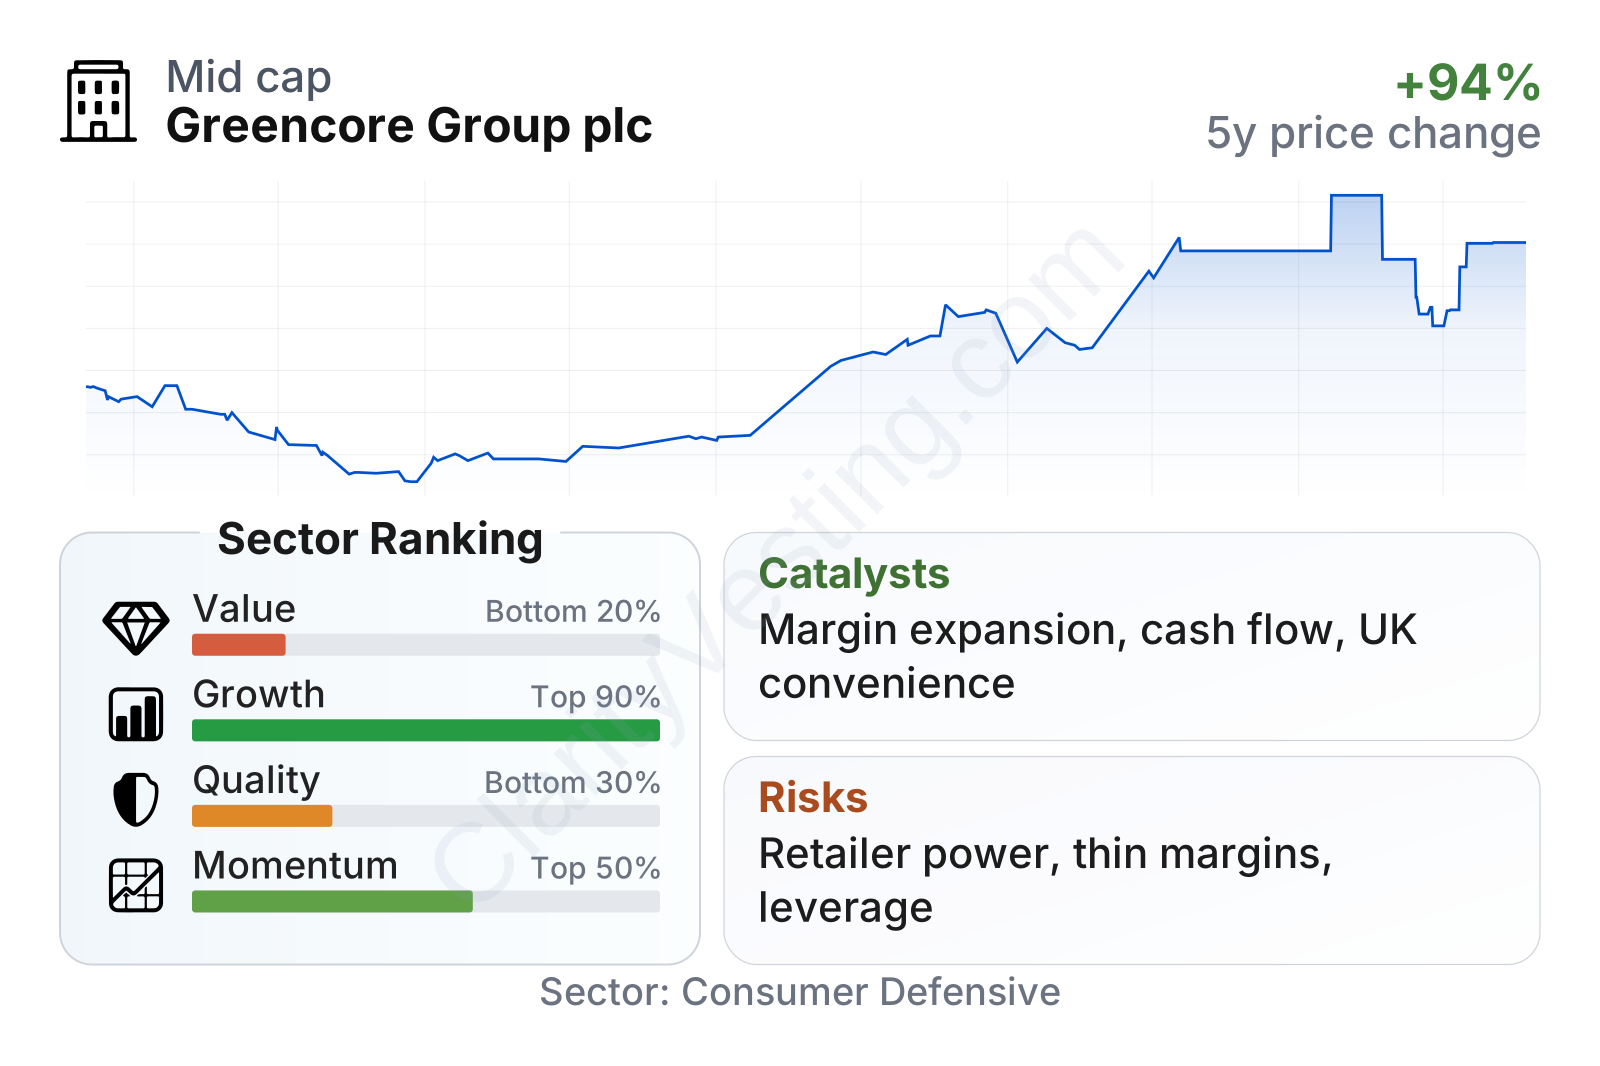
Greencore stands out more for growth than for traditional value or balance-sheet strength. Revenue growth, earnings growth, cash flow growth, and margin trend all rank well versus the broader packaged foods group. The stock’s longer-term share performance has also been strong, although the last six months have been softer.
On the other hand, the company screens weaker on valuation and quality. Profitability remains thinner than many sector peers, leverage is above sector norms, and dividend yield is modest. In simple terms, the business has been improving, but the market is no longer pricing it like a struggling food manufacturer.
Growth
Greencore operates in a part of food consumption that has durable demand drivers. Busy consumers continue to spend on convenience, ready-to-eat meals, meal solutions, and food purchased for immediate consumption. That does not make the sector fast-growing every year, but it does provide a solid long-term base because time-saving food formats are now a normal part of modern grocery shopping.
The company’s strategy also makes practical sense. It has concentrated on categories where scale, freshness, logistics, and retailer service matter most. Those are not easy capabilities to replicate quickly. By focusing on private-label prepared foods, Greencore can deepen relationships with large supermarket chains and benefit when retailers continue expanding their convenience and chilled prepared food ranges.
A notable positive is that the company has recently translated sales into better profitability. Revenue in the financial flow rose from about £1.81 billion in fiscal 2024 to about £1.95 billion in fiscal 2025, while operating income increased from roughly £86 million to about £101 million and net income rose from roughly £46 million to about £58 million. That suggests growth is not coming only from price inflation; operational execution appears to be improving as well.
Recent company updates have also pointed to continued momentum in convenience food categories and disciplined capital allocation. A further catalyst is free cash flow generation: the business is now producing meaningful cash, which can support debt reduction, investment in capacity, and shareholder returns. If Greencore can keep expanding margins from current low-to-mid single-digit operating levels, even modest revenue growth could have an outsized effect on earnings.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


