Stock Analysis · Entain Plc (GMVHF)
Overview
Entain Plc is a global sports betting and gaming company. It operates online betting, online casino, poker, bingo, and retail betting shops through a portfolio of brands that includes bwin, Sportingbet, Ladbrokes, Coral, PartyPoker, and BetMGM through its joint venture in the United States. In simple terms, the business makes money by taking wagers on sports and events, offering digital casino games, and running betting shops in regulated markets.
Its revenue base is diversified across geography, product type, and channels. Based on recent company reporting, the main sources of revenue can be described as follows:
- Online sports betting and gaming: approximately 65% to 75% of group revenue. This includes digital sports wagers, online casino, poker, bingo, and other interactive gaming products across multiple international markets.
- Retail betting shops: approximately 15% to 25% of group revenue. This mainly comes from Ladbrokes and Coral betting shops, especially in the United Kingdom and Ireland.
- BetMGM joint venture contribution: economically important but not fully consolidated as standard group revenue. Entain owns 50% of BetMGM, so its value shows up through earnings, cash expectations, and strategic positioning rather than as a simple top-line line item in the same way as wholly owned operations.
- Other business-to-business and smaller activities: a low-single-share portion of group activity, depending on the reporting period and classification.
What stands out is the mix between mature cash-generating brands and digital operations with international reach. Over the last several years, revenue has generally moved higher, but profits have been much more volatile because of impairment charges, regulatory costs, taxes, and financing expenses. That means the business is easier to understand at the revenue and cash generation level than at headline net income.
The long-term pattern shows a company that kept expanding its top line from 2021 through 2025, while profitability became uneven. Gross profit remained substantial, but interest expense stayed elevated and net income turned negative in multiple years. That gap between strong customer activity and weaker bottom-line results is central to understanding Entain.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Consumer Cyclical | |
| Industry | Gambling | |
| Market Cap ⓘ | $3.75B | |
| Beta ⓘ | 0.76 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 17.04 |
| P/B Ratio ⓘ | 9.56 | 1.61 |
| FCF Yield ⓘ | 26.83% | 9.02% |
| Dividend Yield ⓘ | 3.34% | 2.75% |
| EBIT / EV ⓘ | N/A | 6.69% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 7.40% | 5.60% |
| RPS Growth (5Y CAGR) ⓘ | 6.14% | 9.04% |
| EPS Growth (5Y CAGR) ⓘ | -10.34% | -17.44% |
| BVPS Growth (5Y CAGR) ⓘ | -39.79% | 5.73% |
| Margin Growth (5Y Trend) ⓘ | -2.91% | -0.26% |
| FCF Growth (5Y CAGR) ⓘ | 4.81% | 4.91% |
| DPS Growth (5Y CAGR) ⓘ | 46.50% | 10.48% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 12.38% |
| ROA (Latest) ⓘ | N/A | 5.54% |
| ROIC (5Y Median) ⓘ | 5.02% | 10.63% |
| ROA (5Y Median) ⓘ | -4.31% | 5.44% |
| Net Debt / EBIT (Latest) ⓘ | 4.67 | 2.16 |
| Net Debt / EBIT (5Y Median) ⓘ | 4.42 | 2.31 |
| Net Debt / EBITDA (Latest) ⓘ | 2.15 | 1.52 |
| Net Debt / Assets ⓘ | 38.68% | 21.74% |
| EBITDA / Interest ⓘ | 4.31 | 9.06 |
| Operating Margin (Latest) ⓘ | 9.65% | 9.12% |
| Operating Margin (5Y Median) ⓘ | 10.21% | 9.56% |
| Debt to Equity (Latest) ⓘ | 497.51% | 76.18% |
| Profit Margin (Latest) ⓘ | -10.65% | 5.30% |
| Free Cash Flow (Latest) ⓘ | $1.01B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | -43.83% | +11.77% |
| 12M Return (excl. last month) ⓘ | -37.86% | +0.61% |
| 6M Return ⓘ | -19.94% | +1.32% |
| Price vs. 200-Day MA ⓘ | -24.58% | -3.47% |
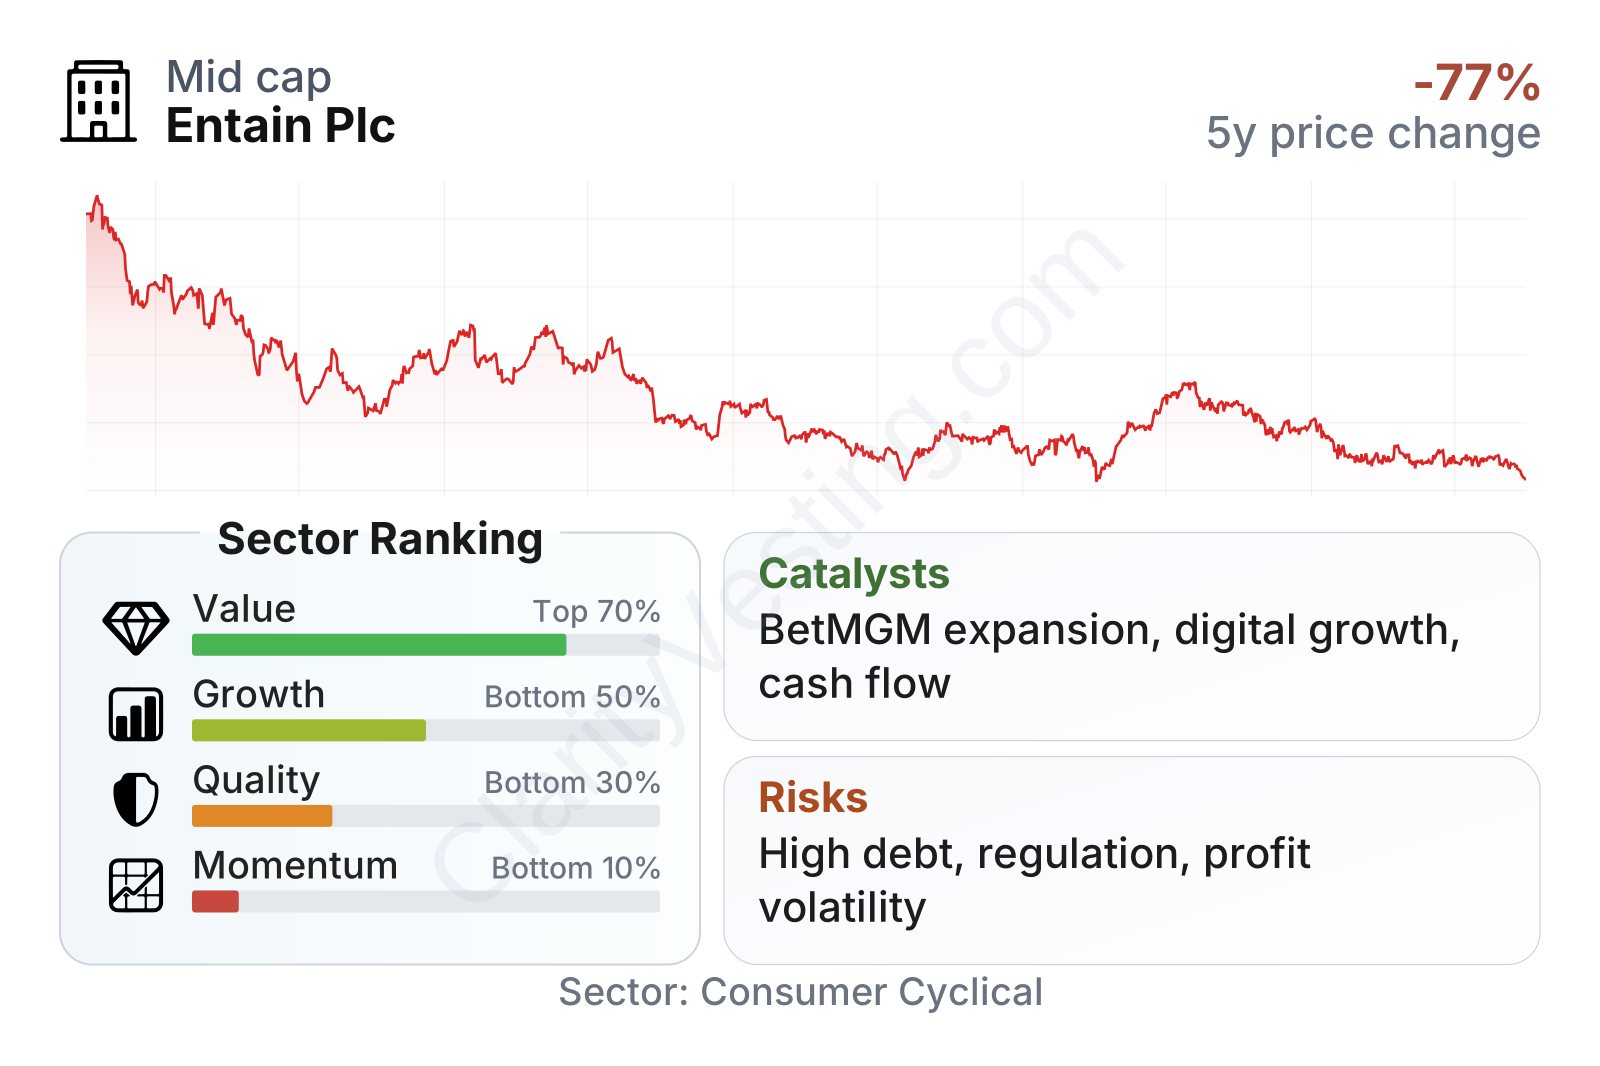
Entain is a mid-sized company by public market standards, with a share price that has been under heavy pressure over the last few years. The stock has fallen sharply from 2021 levels, and recent momentum remains weak relative to the broader consumer cyclical group. At the same time, free cash flow generation looks strong, the dividend yield is above the sector median, and recent year-over-year revenue growth is slightly ahead of the sector median. The mixed picture is important: market performance has been poor, but the underlying business is still producing meaningful cash. Quality measures are weaker, mainly because leverage is high, returns on assets have been soft, and recent profit margins have been negative.
Growth
The broader sector is still supported by a long-term structural shift from physical betting locations toward mobile and online gambling. In many regulated markets, customers continue to move toward app-based betting, in-play wagering, and online casino products. That trend is favorable for operators with established technology, brand recognition, and compliance infrastructure, and Entain has all three.
Its strategy also makes sense on paper. The company has a large portfolio of consumer brands, broad exposure to regulated markets, and a meaningful stake in BetMGM, one of the better-known names in U.S. online betting and iGaming. Entain has also emphasized operational efficiency, capital discipline, and focusing on markets where regulation is clearer and scale matters more. For a business in gambling, regulation can raise costs, but it can also strengthen the position of larger licensed operators by making life harder for smaller or less compliant rivals.
Revenue growth has remained positive recently, though the longer-term growth profile is not especially strong compared with the sector. That suggests a business still expanding, but not at a pace that automatically offsets all of its balance-sheet and profitability pressures. The more compelling growth catalyst is the combination of digital expansion and the U.S. opportunity through BetMGM. If BetMGM keeps improving its economics and if more U.S. states allow online casino or broader digital betting, Entain’s strategic value could improve even without dramatic growth in its legacy retail estate.
Another positive development is that the company has continued to highlight solid underlying trading in core markets and ongoing cash generation. For long-term analysis, this matters because the business does not rely only on a distant future opportunity; it already operates a large, active betting platform with established brands and recurring customer activity.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


