Stock Analysis · G Mining Ventures Corp (GMINF)
Overview
G Mining Ventures Corp is a gold mining company focused on building and operating large-scale mines in the Americas. The company moved from a development-stage profile into a producing miner with the start-up of its Tocantinzinho gold mine in Brazil. That transition matters because it changes the business from one that mainly spends capital on construction into one that can generate operating cash flow from gold sales.
Today, the business is much simpler than a diversified miner. Its revenue is overwhelmingly tied to one commodity, gold, and mainly to one producing asset, Tocantinzinho. That concentration can make performance easier to understand, but it also means results are highly dependent on mine execution and the gold price.
The main sources of revenue are currently:
- Gold sales from Tocantinzinho: approximately nearly 100% of revenue. This includes doré production sold after processing ore at the Brazilian operation.
- Other revenue: immaterial based on public reporting. The company is not meaningfully diversified by metal, geography, or operating segment at this stage.
The recent financial progression shows a sharp break from the earlier pre-production years. Revenue was essentially absent through 2023, then appeared in 2024 as the mine ramped up, and expanded strongly in 2025. That is consistent with a company completing construction and entering commercial production rather than a mature miner growing incrementally.
The operating profile changed dramatically once production began: the company went from no revenue and recurring losses during the build phase to strong sales, high operating margins, and meaningful net income. That step-up is the central feature of the business today.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Gold | |
| Market Cap ⓘ | $9.44B | |
| Beta ⓘ | 0.87 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 20.29 | 16.92 |
| P/B Ratio ⓘ | 3.98 | 1.66 |
| FCF Yield ⓘ | -0.17% | 5.83% |
| Dividend Yield ⓘ | N/A | 2.07% |
| EBIT / EV ⓘ | 3.96% | 6.38% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 21.20% | 11.25% |
| RPS Growth (5Y CAGR) ⓘ | N/A | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -15.24% |
| BVPS Growth (5Y CAGR) ⓘ | 141.09% | 5.49% |
| Margin Growth (5Y Trend) ⓘ | N/A | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 5.91% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 19.28% | 9.59% |
| ROA (Latest) ⓘ | 18.17% | 4.92% |
| ROIC (5Y Median) ⓘ | -2.00% | 7.91% |
| ROA (5Y Median) ⓘ | -1.47% | 3.92% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.36 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.69 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 0.93 |
| Net Debt / Assets ⓘ | N/A | 13.69% |
| EBITDA / Interest ⓘ | 29.96 | 12.38 |
| Operating Margin (Latest) ⓘ | 64.55% | 13.24% |
| Operating Margin (5Y Median) ⓘ | N/A | 11.82% |
| Debt to Equity (Latest) ⓘ | N/A | 40.30% |
| Profit Margin (Latest) ⓘ | 56.47% | 6.38% |
| Free Cash Flow (Latest) ⓘ | -$16.15M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +863.23% | +73.47% |
| 12M Return (excl. last month) ⓘ | +94.76% | +27.59% |
| 6M Return ⓘ | -13.33% | -4.02% |
| Price vs. 200-Day MA ⓘ | -6.35% | -0.65% |
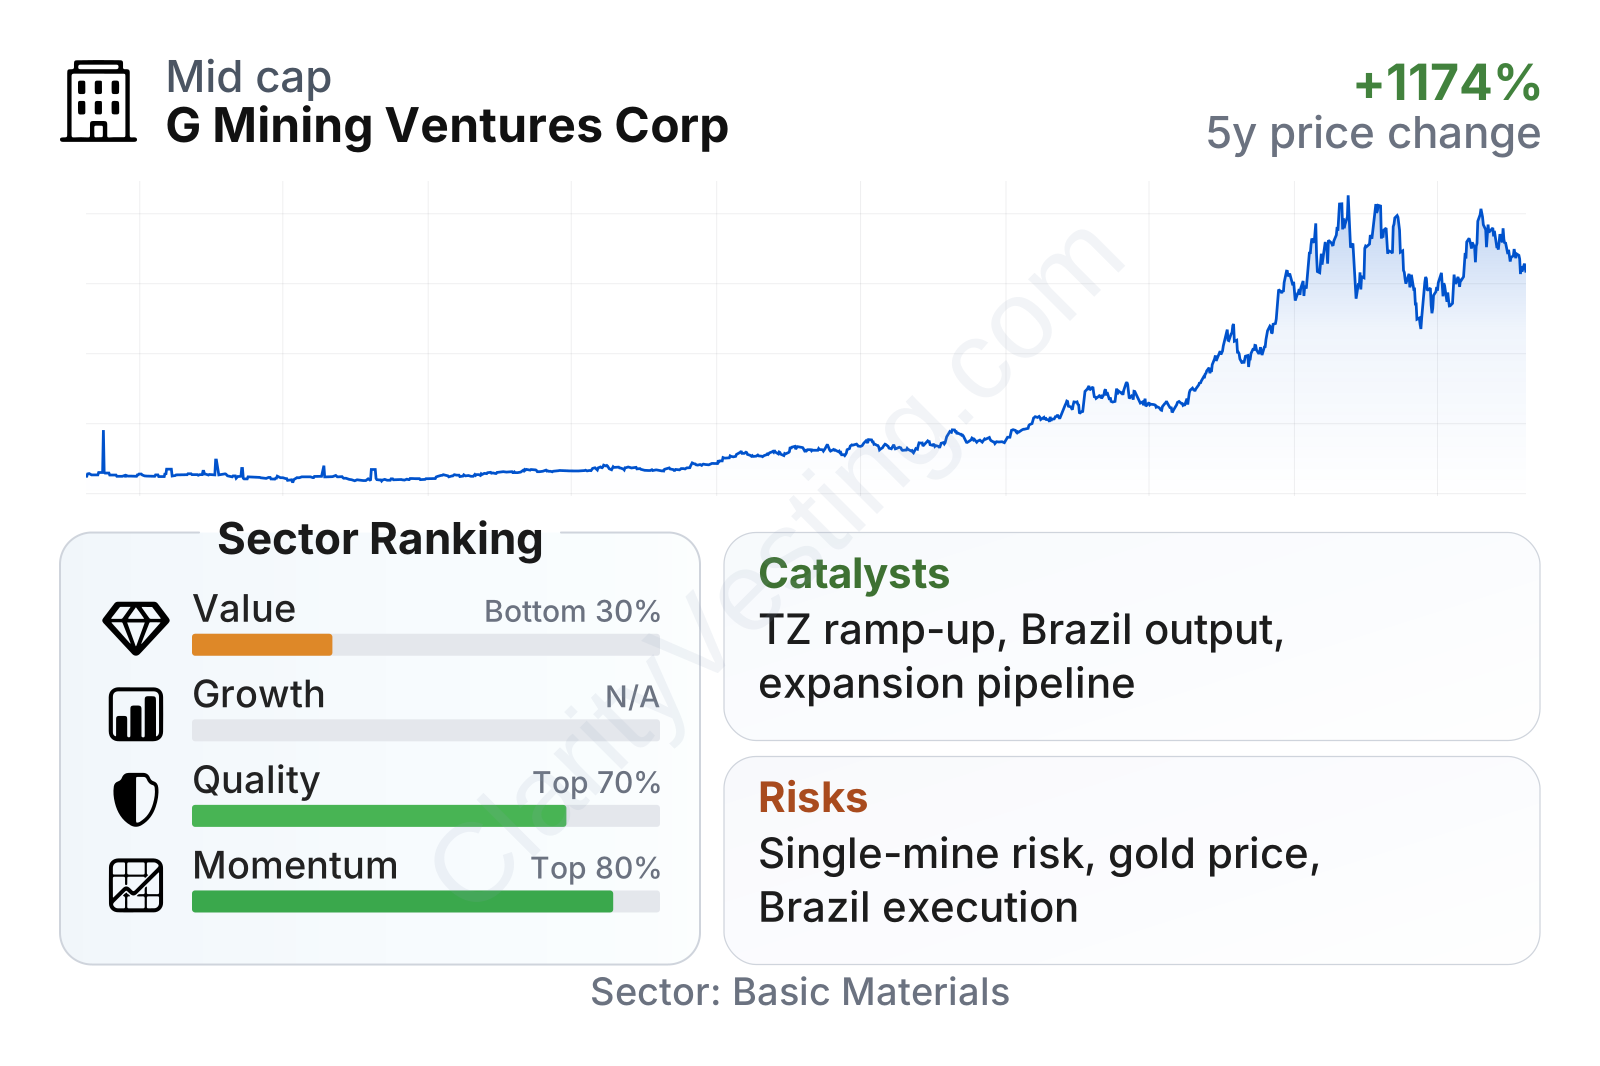
The market now treats G Mining Ventures as a sizeable gold producer rather than a speculative developer. Recent growth and profitability metrics are strong versus much of the sector, with revenue growth above the sector median and unusually high current margins and returns on capital. At the same time, valuation measures look less conservative: earnings and especially book-value multiples sit above sector medians, while free cash flow remains slightly negative on a trailing basis. In short, the company scores well on current operating quality and share-price momentum, but the valuation already reflects a meaningful portion of that progress.
Growth
Gold remains a supportive sector for long-term interest because it benefits from several durable themes: central-bank buying, demand for financial hedges during inflation or geopolitical stress, and the need for new mine supply as many global deposits age. Unlike industrial metals, gold demand is less tied to one economic cycle, although price swings still matter a great deal.
For G Mining Ventures specifically, the growth case is closely linked to successful mine execution. The most important recent change is that Tocantinzinho has moved from construction into production. That creates a much larger earnings base than the company had in prior years. The jump from no meaningful revenue before 2024 to hundreds of millions of dollars in annual sales by 2025 shows how powerful that shift can be when a mine starts operating as planned.
The broader strategy also makes sense in a sector where large, buildable projects are scarce. The company has roots connected to the G Mining group, which has a reputation in mine development and construction. For a mining company, the ability to permit, finance, build, and ramp a mine is a core growth engine. It can support future project expansion more effectively than a pure exploration model that depends mainly on drilling results and capital markets access.
A further catalyst is operating optimization at Tocantinzinho. In the early life of a mine, companies often improve throughput, recovery, and unit costs after the initial ramp-up. If management can stabilize production and keep costs under control, the same asset may produce stronger cash generation than the first year alone suggests. With gold prices remaining favorable in the recent environment, each improvement in production efficiency can have an outsized effect on profitability.
Recent company communications have also highlighted the company’s ambition to grow beyond a single asset. That matters because the market generally gives higher strategic value to miners that can evolve from one-mine businesses into multi-asset platforms. If additional projects are acquired, advanced, or financed under acceptable terms, the company’s growth profile could broaden materially over time.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


