Stock Analysis · GoGold Resources Inc (GLGDF)
Overview
GoGold Resources Inc. is a precious-metals mining company focused on Mexico. Its business has two distinct parts: producing silver and gold from its operating Parral tailings project in Chihuahua, and advancing the much larger Los Ricos project, which is split into Los Ricos South and Los Ricos North in Jalisco. In simple terms, Parral generates current cash flow, while Los Ricos is the company’s main long-term development engine.
Today, revenue comes overwhelmingly from metal sales at Parral. Based on the latest full-year results, the company’s sales are tied primarily to silver, with gold and smaller by-product metals making up the remainder. Exact product mix can move with metal prices and recovery rates, but the revenue base can be summarized as follows:
- Silver sales: approximately 70% to 80% of revenue. This is the company’s main economic driver and comes from processing historical mine tailings at Parral.
- Gold sales: approximately 15% to 25% of revenue. Gold is recovered alongside silver and provides an important secondary contribution.
- Other metals, mainly copper and minor by-products: generally less than 10% of revenue.
That concentration matters. Unlike diversified miners with multiple producing assets across countries, GoGold remains largely dependent on one operating site for current income. At the same time, that operating base helps fund development work instead of relying only on repeated share issuance.
The recent operating picture also looks meaningfully stronger than it did two years ago. Revenue and net income have improved sharply, and the business has moved from losses to healthier profitability as grades, recoveries, and metal-price conditions improved. The company remains mid-sized by market value, but it is still essentially a single-producer with a development pipeline attached.
The business mix has become much more favorable. Revenue expanded strongly in the latest year, while operating income and net income improved far faster than sales, showing that fixed costs are being spread over a better production base. Interest expense remained modest, which suggests that recent earnings gains were driven mainly by operations rather than financial engineering.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Other Precious Metals & Mining | |
| Market Cap ⓘ | $1.17B | |
| Beta ⓘ | 1.73 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 24.64 | 16.90 |
| P/B Ratio ⓘ | 2.27 | 1.65 |
| FCF Yield ⓘ | 5.05% | 5.76% |
| Dividend Yield ⓘ | N/A | 2.13% |
| EBIT / EV ⓘ | 5.11% | 6.30% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 56.80% | 11.10% |
| RPS Growth (5Y CAGR) ⓘ | -0.00% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | 109.01% | -13.47% |
| BVPS Growth (5Y CAGR) ⓘ | 6.41% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | 18.48% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.08% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 11.33% | 9.26% |
| ROA (Latest) ⓘ | 9.76% | 4.91% |
| ROIC (5Y Median) ⓘ | 2.18% | 7.70% |
| ROA (5Y Median) ⓘ | 0.51% | 3.86% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 0.95 |
| Net Debt / Assets ⓘ | N/A | 13.69% |
| EBITDA / Interest ⓘ | 133.63 | 12.34 |
| Operating Margin (Latest) ⓘ | 61.05% | 13.20% |
| Operating Margin (5Y Median) ⓘ | 15.03% | 11.80% |
| Debt to Equity (Latest) ⓘ | N/A | 40.56% |
| Profit Margin (Latest) ⓘ | 43.37% | 6.43% |
| Free Cash Flow (Latest) ⓘ | $59.29M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +177.42% | +68.89% |
| 12M Return (excl. last month) ⓘ | +54.69% | +30.21% |
| 6M Return ⓘ | +25.24% | -4.16% |
| Price vs. 200-Day MA ⓘ | +6.84% | -1.27% |
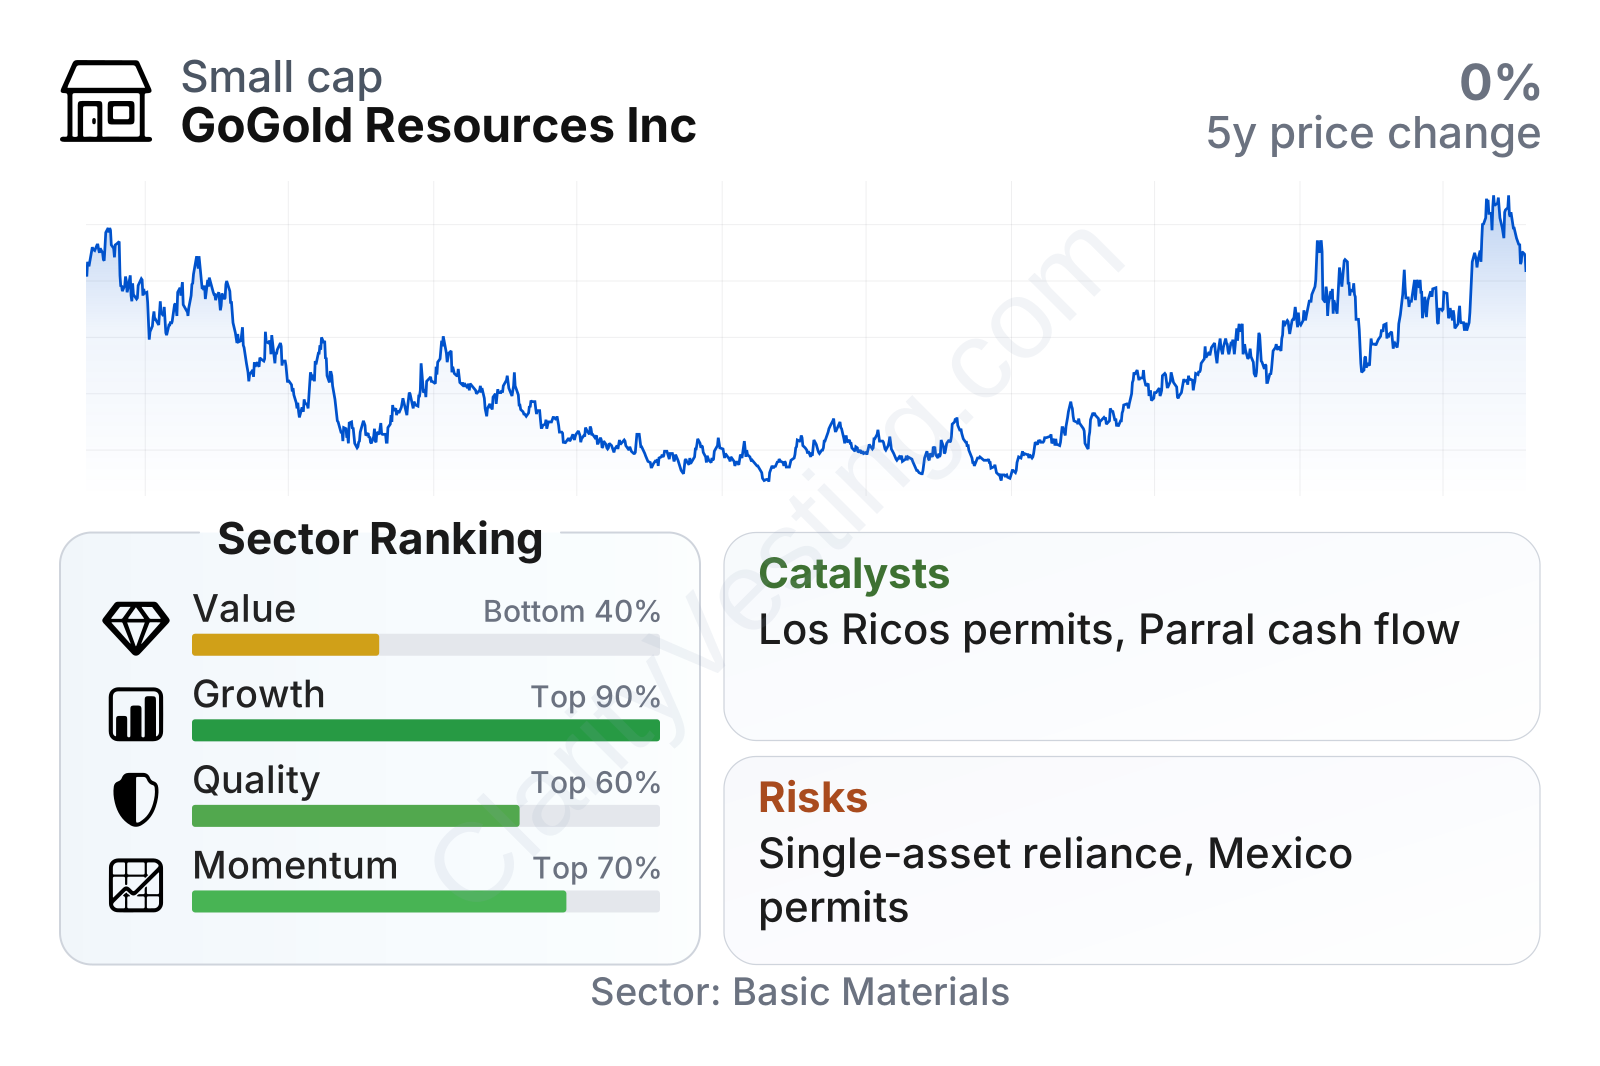
GoGold stands out for growth, with revenue expansion far above the sector median and earnings progression that has improved sharply over the last several years. Quality is more mixed but still respectable: current returns on capital and assets are ahead of many peers, margins are strong, and interest coverage is unusually high. Valuation is less forgiving, with earnings and book-value multiples above sector medians, while free-cash-flow yield is slightly below the broader group. Market behavior has also been strong, as the shares have materially outperformed over six months, twelve months, and three years, but the elevated beta points to above-average volatility.
Growth
GoGold operates in a sector with durable long-term relevance. Silver benefits from both traditional precious-metals demand and industrial uses such as solar, electronics, and electrification. Gold remains closely tied to store-of-value demand and central-bank accumulation. That does not create steady year-to-year growth the way software or healthcare might, but it does provide a meaningful structural backdrop for quality precious-metals projects.
The company’s strategy is logical. Parral gives it a producing asset with cash generation, while Los Ricos offers the potential step-change. This is the central point for long-term analysis: the current operation alone does not fully explain the company’s ambition or market profile. Much of the long-range case depends on whether Los Ricos becomes a larger, higher-value mining complex over time.
The turnaround in sales growth has been significant. After a long period of declines, revenue growth moved decisively positive and then accelerated into very strong territory. That kind of reversal usually signals more than just a small price benefit; it often reflects improving throughput, recoveries, grade mix, or commercial conditions. The result is that GoGold has shifted from a weak production phase into a much stronger operating period.
Cash generation has also improved in an important way. Free cash flow moved from negative territory to positive, which matters for a miner that is trying to advance development assets without excessive balance-sheet strain. Positive free cash flow does not remove funding questions around future construction, but it does strengthen the company’s flexibility and lowers dependence on outside capital for routine needs.
A major catalyst remains project advancement at Los Ricos, especially permitting, updated studies, and any financing or construction milestones that reduce uncertainty around development. Company disclosures in 2026 continued to emphasize progress at Los Ricos South and the broader development path in Mexico. If those milestones continue to de-risk the project, the company could evolve from a single operating asset into a larger multi-asset precious-metals producer.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


