Stock Analysis · Glanbia plc (GLAPF)
Overview
Glanbia plc is an Irish nutrition company focused on cheese, dairy ingredients, and performance nutrition products. The group has reshaped itself over the past several years through portfolio changes, with a stronger emphasis today on branded nutrition and value-added ingredients rather than broad commodity food exposure. Its activities span consumer brands, sports nutrition, lifestyle nutrition, and ingredient solutions used by food and beverage manufacturers.
The company’s revenue base is now mainly organized around two operating segments. Based on recent annual reporting, the business mix is approximately:
- Glanbia Performance Nutrition: about 65% to 75% of revenue. This segment includes sports nutrition and lifestyle nutrition brands such as Optimum Nutrition, Isopure, SlimFast, think!, Amazing Grass, and related products sold through retail, specialty, e-commerce, and international distribution channels.
- Glanbia Nutritionals: about 25% to 35% of revenue. This unit supplies cheese, dairy and non-dairy ingredients, micronutrient premixes, flavor and functional solutions, and customized ingredient systems for food, beverage, and nutrition customers.
That mix makes Glanbia more exposed to higher-value nutrition categories than many traditional dairy processors, although dairy input costs still matter because ingredients remain an important part of the group. The business is also geographically diversified, with North America representing the largest market, supported by operations in Europe and other international regions.
Over the last several years, revenue and profit conversion have not moved in a straight line because acquisitions, disposals, and business restructuring changed the size and shape of the company. Even so, one notable pattern is that gross profit has held up better than total revenue after the portfolio reset, suggesting the company is leaning toward businesses with better value-added characteristics than pure volume processing.
The profit flow also shows why Glanbia is not simply a commodity food company. Cost of sales remains the largest outflow, as expected in nutrition and dairy-linked products, but operating profitability improved meaningfully from earlier years before becoming more affected by restructuring of the portfolio. Free cash generation has remained solid relative to the company’s size, which is an important support for flexibility.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 21, 2026 | |
| Context | ||
| Sector | Consumer Defensive | |
| Industry | Packaged Foods | |
| Market Cap ⓘ | $5.68B | |
| Beta ⓘ | 0.51 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 24.23 | 18.68 |
| P/B Ratio ⓘ | 3.02 | 1.24 |
| FCF Yield ⓘ | 12.13% | 12.11% |
| Dividend Yield ⓘ | 2.28% | 2.67% |
| EBIT / EV ⓘ | 11.36% | 6.40% |
| PEG ⓘ | 8.27 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 7.90% | 4.10% |
| RPS Growth (5Y CAGR) ⓘ | 3.24% | 6.22% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -13.59% |
| BVPS Growth (5Y CAGR) ⓘ | 6.61% | 3.27% |
| Margin Growth (5Y Trend) ⓘ | 3.97% | -0.13% |
| FCF Growth (5Y CAGR) ⓘ | 18.71% | 4.10% |
| DPS Growth (5Y CAGR) ⓘ | 15.31% | 6.83% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 20.40% | 12.34% |
| ROA (Latest) ⓘ | 11.08% | 6.30% |
| ROIC (5Y Median) ⓘ | 8.61% | 10.53% |
| ROA (5Y Median) ⓘ | 4.99% | 5.44% |
| Net Debt / EBIT (Latest) ⓘ | 1.16 | 1.98 |
| Net Debt / EBIT (5Y Median) ⓘ | 2.20 | 2.35 |
| Net Debt / EBITDA (Latest) ⓘ | 0.82 | 1.38 |
| Net Debt / Assets ⓘ | 20.84% | 21.70% |
| EBITDA / Interest ⓘ | 15.16 | 9.49 |
| Operating Margin (Latest) ⓘ | 7.87% | 8.88% |
| Operating Margin (5Y Median) ⓘ | 6.18% | 9.57% |
| Debt to Equity (Latest) ⓘ | 63.69% | 72.35% |
| Profit Margin (Latest) ⓘ | 5.80% | 5.40% |
| Free Cash Flow (Latest) ⓘ | $689.10M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +63.19% | +24.53% |
| 12M Return (excl. last month) ⓘ | +30.74% | +1.93% |
| 6M Return ⓘ | +16.76% | +1.61% |
| Price vs. 200-Day MA ⓘ | +29.14% | +2.99% |
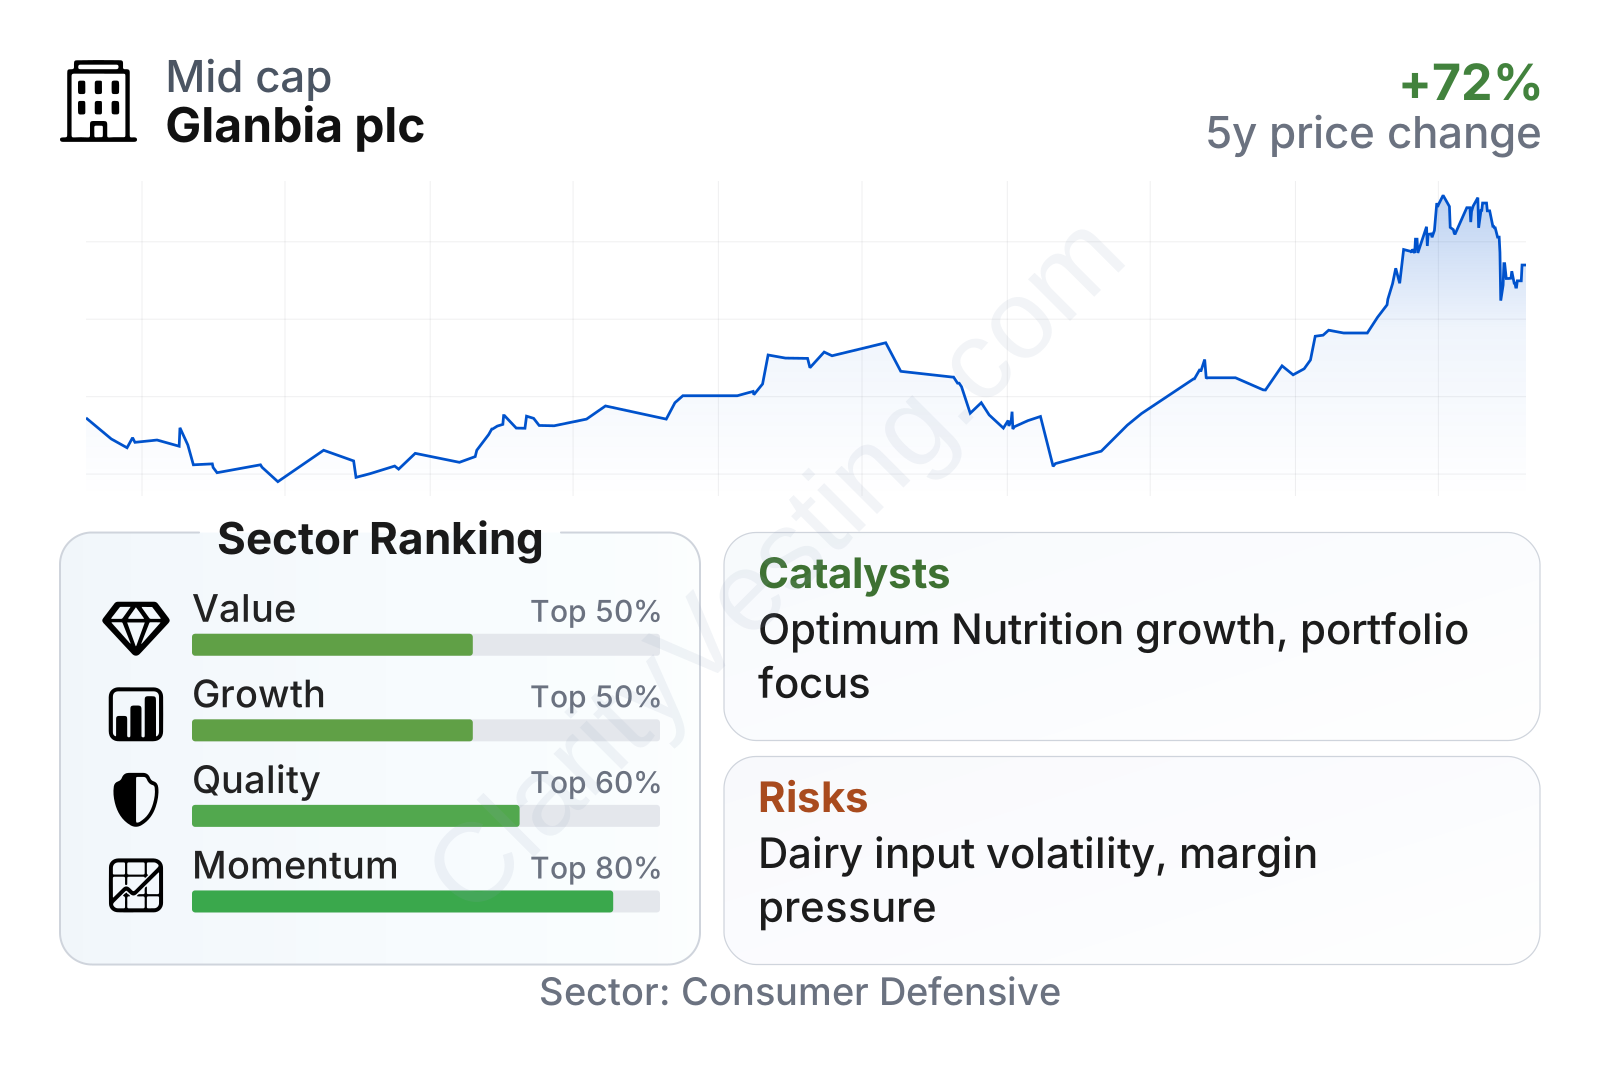
Glanbia sits in the mid-cap range and its share price volatility has been relatively low, with a beta around 0.5. Recent market performance has been strong: the stock has risen sharply over three years and has outperformed much of the broader consumer staples universe over the last 6 to 12 months. That suggests the market has become more confident in the company’s repositioning and earnings quality.
On growth and profitability, the picture is mixed but broadly constructive. Recent revenue growth is ahead of the sector median, and free cash flow growth over five years has been especially strong. Returns on capital and assets are also above sector medians on a trailing basis, while leverage looks controlled, with net debt below many peers and interest coverage at a comfortable level. The weaker area is margin depth: operating margin remains below the sector median, which means Glanbia is profitable but not among the very best-margin businesses in packaged foods and nutrition.
Valuation signals are also mixed. The earnings multiple and price-to-book ratio are above sector medians, which points to a market that already assigns credit for business quality and recent momentum. At the same time, cash-flow-based measures look more reasonable, with free cash flow yield close to the sector median and EBIT relative to enterprise value stronger than the sector median. In simple terms, the shares do not look distressed, but they also do not appear priced like a low-quality staples business.
Growth
Glanbia operates in areas with better structural growth than standard packaged food categories. Performance nutrition, active lifestyle products, high-protein formats, and specialized ingredient systems have all benefited from long-term demand trends tied to wellness, convenient nutrition, and protein consumption. These are not brand-new themes anymore, but they still offer room for expansion through premium products, international distribution, and direct-to-consumer or digital channels.
The company’s strategy broadly makes sense for future growth because it concentrates capital on categories where branding, formulation expertise, and customer relationships can matter more than scale alone. In branded performance nutrition, products are sold on trust, efficacy, taste, and product innovation. In ingredients, the value can come from formulation know-how and integration into customers’ product pipelines rather than just raw material supply. That combination gives Glanbia a better growth profile than a pure dairy processor.
A key catalyst is the continued global expansion of sports and lifestyle nutrition. Optimum Nutrition remains one of the best-known brands in the category, and that creates opportunities in protein powders, ready-to-drink formats, bars, and adjacent wellness products. Another support is that Glanbia has been simplifying its portfolio, which can improve management focus and capital allocation. If the company continues shifting toward branded and specialized products, earnings quality could improve even if top-line growth is not spectacular every year.
Recent corporate updates have also highlighted ongoing efforts around productivity, portfolio streamlining, and investment behind core nutrition brands. That matters because the long-term opportunity is not only about selling more volume; it is also about improving the mix toward products with stronger pricing power and steadier margins.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


