Stock Analysis · Guardant Health Inc (GH)
Overview
Guardant Health is a precision oncology company focused on blood-based testing, often called “liquid biopsy.” Instead of relying only on tissue samples, its tests analyze tumor-related signals in blood to help detect cancer, guide treatment decisions, and monitor disease. The company operates across several points in the cancer care pathway: screening for cancer in people without symptoms, identifying tumor mutations for therapy selection, and tracking disease over time.
Its business is built around laboratory testing services and related biopharma partnerships. Based on recent company reporting, revenue is primarily generated from oncology testing sold to clinical customers, with a smaller but still meaningful contribution from drug-development and companion-diagnostic work for biopharma companies. Recent filings also show a fast-growing contribution from screening, helped by the launch and adoption of Shield, the company’s blood test for colorectal cancer screening.
The main revenue sources can be summarized as follows:
- Precision oncology testing: approximately 70% to 80% of revenue recently, including tests such as Guardant360 for advanced cancer treatment selection and Guardant Reveal for minimal residual disease and recurrence monitoring.
- Screening: approximately 10% to 20% of revenue and rising, mainly driven by Shield, the company’s blood-based colorectal cancer screening test.
- Biopharma and data partnerships: approximately 10% to 15% of revenue, including services tied to clinical trials, companion diagnostics, and molecular data work with drug developers.
Financially, the company is still in build-out mode. Revenue has scaled sharply over the past several years, gross profit has expanded with it, and losses have narrowed from peak levels, but spending on research, clinical programs, commercial rollout, and infrastructure remains high. That pattern fits a company trying to establish itself across multiple large cancer testing markets at once.
The long-term pattern is clear: revenue has climbed strongly, gross profit has widened, and net losses have improved from the deepest period, but operating expenses remain very heavy. Research and development continues to absorb a large share of resources, which reflects both product innovation and the cost of pursuing large regulated screening markets.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Diagnostics & Research | |
| Market Cap ⓘ | $23.94B | |
| Beta ⓘ | 1.58 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 24.06 |
| P/B Ratio ⓘ | N/A | 3.08 |
| FCF Yield ⓘ | -1.01% | 3.07% |
| Dividend Yield ⓘ | N/A | 2.05% |
| EBIT / EV ⓘ | -1.84% | 0.63% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 44.30% | 7.50% |
| RPS Growth (5Y CAGR) ⓘ | 20.72% | 8.70% |
| EPS Growth (5Y CAGR) ⓘ | -27.40% | -18.20% |
| BVPS Growth (5Y CAGR) ⓘ | N/A | 3.95% |
| Margin Growth (5Y Trend) ⓘ | N/A | -0.58% |
| FCF Growth (5Y CAGR) ⓘ | -4.83% | 0.88% |
| DPS Growth (5Y CAGR) ⓘ | 68.09% | 6.80% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | -29.43% | 3.29% |
| ROA (Latest) ⓘ | -28.44% | 3.02% |
| ROIC (5Y Median) ⓘ | -29.32% | 4.75% |
| ROA (5Y Median) ⓘ | -26.67% | 1.93% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.33 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.83 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 0.99 |
| Net Debt / Assets ⓘ | 33.65% | 5.33% |
| EBITDA / Interest ⓘ | N/A | 9.63 |
| Operating Margin (Latest) ⓘ | -38.01% | 9.25% |
| Operating Margin (5Y Median) ⓘ | -84.44% | 7.80% |
| Debt to Equity (Latest) ⓘ | -761.45% | 28.99% |
| Profit Margin (Latest) ⓘ | -38.33% | 3.60% |
| Free Cash Flow (Latest) ⓘ | -$240.72M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +498.87% | +37.48% |
| 12M Return (excl. last month) ⓘ | +143.86% | +20.85% |
| 6M Return ⓘ | +91.72% | +9.73% |
| Price vs. 200-Day MA ⓘ | +41.43% | +4.69% |
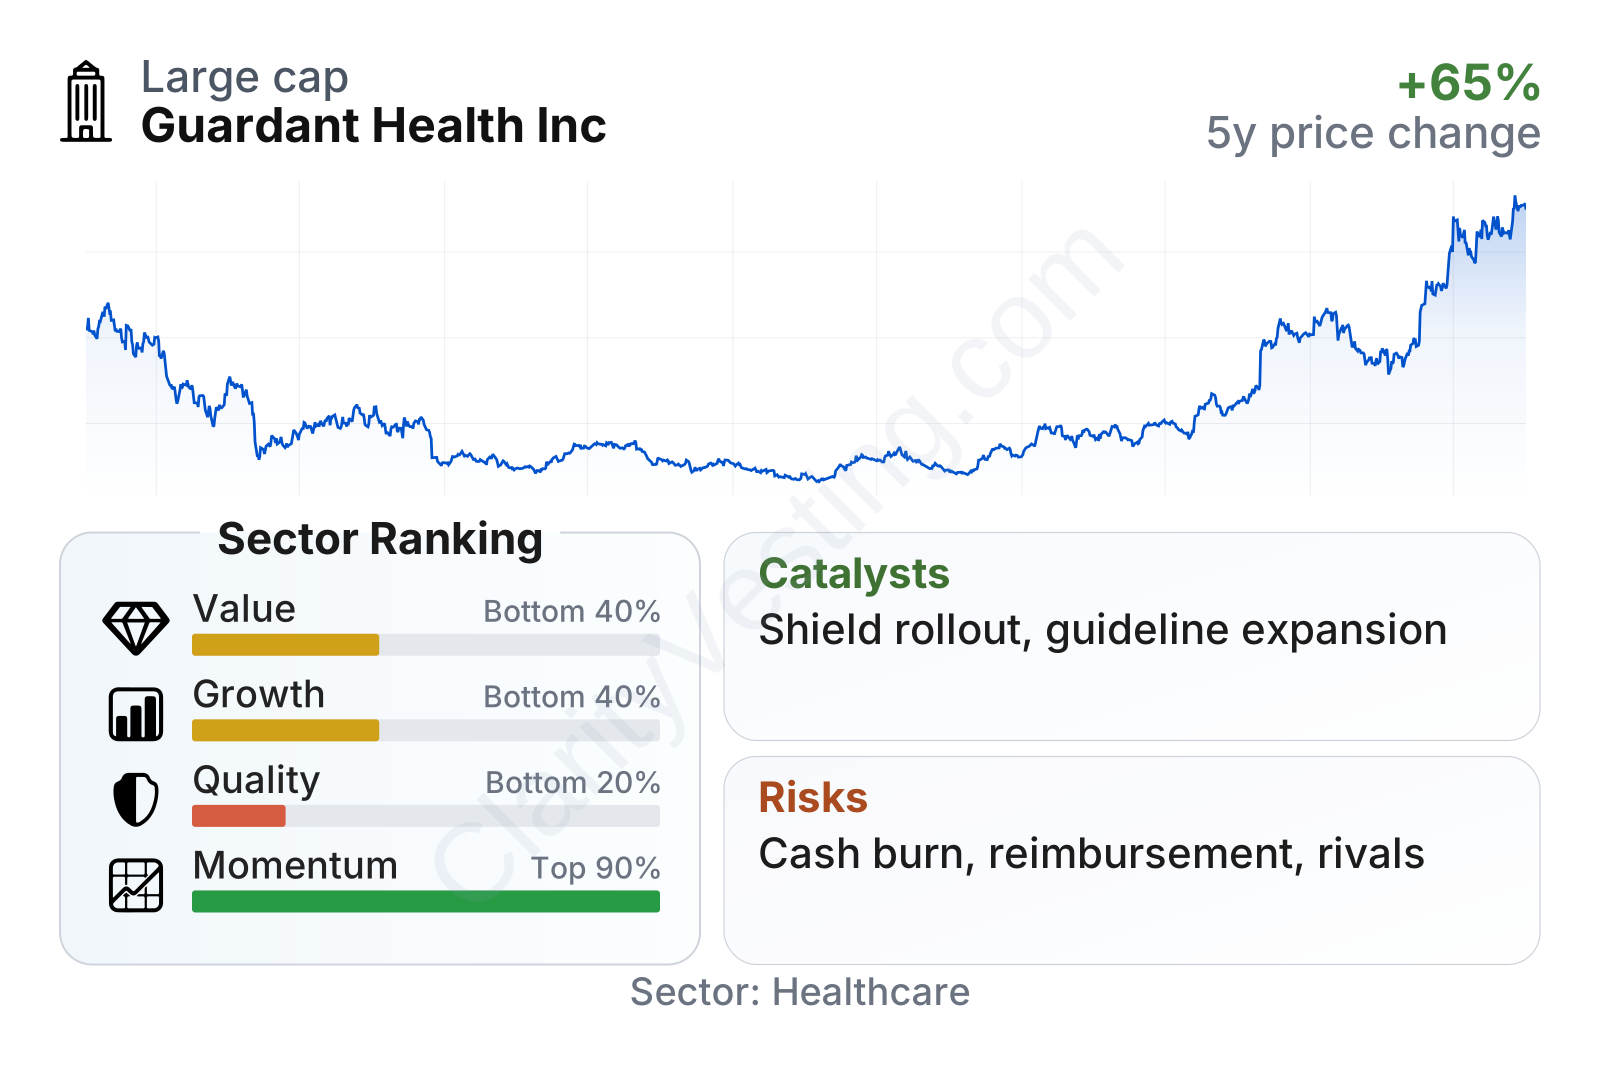
Guardant Health stands out for market momentum and revenue expansion, but the operating profile is still weak compared with much of the healthcare sector. Revenue growth is far above the sector median, while profitability, returns on capital, and cash generation remain well below typical peers. In other words, the market is rewarding acceleration and future potential more than current earnings quality.
The stock’s trading history also shows how sensitive sentiment has been. After a deep decline from 2021 into 2024, the share price rebounded sharply through 2025 and into 2026. That kind of move usually signals improving expectations, but it also means the market is already pricing in a meaningful amount of future progress.
Growth
Guardant Health operates in a sector with genuine long-term tailwinds. Cancer remains one of the largest healthcare burdens globally, and there is strong medical interest in tests that are less invasive, easier to repeat, and potentially usable earlier in the care journey. Liquid biopsy fits that direction well. If these tests continue to gain clinical acceptance, they can become useful in advanced cancer, recurrence monitoring, and population screening, each of which is a very large market on its own.
The company’s strategy is coherent because it is not relying on a single niche use case. It has built products for advanced cancer genotyping, residual disease detection, and cancer screening. That diversification matters: advanced cancer testing can support current revenue, while screening offers the largest long-term commercial opportunity if adoption continues. The company has also spent years building evidence, payer relationships, and biopharma ties, which can strengthen adoption over time.
Recent growth has been unusually strong. Year-over-year revenue growth has stayed well above most sector peers and accelerated into the 40% range in the latest periods. That suggests the company is moving beyond a slow adoption phase and into a broader commercial expansion, with screening appearing to be an important driver.
A major catalyst has been Shield. The test received U.S. FDA approval in 2024 for colorectal cancer screening in average-risk adults, a milestone that opened the door to broader commercial adoption. The next key step was guideline support: inclusion in recognized screening guidelines can make physician uptake and payer coverage more realistic at scale. For Guardant Health, that matters because screening is a much larger market than advanced cancer therapy selection alone.
Another favorable development is the broader trend toward blood-based cancer testing in routine care. Hospitals, oncologists, and health systems increasingly want faster and less invasive tools. Guardant360 already has strong recognition in comprehensive genomic profiling for advanced cancer, and that installed position can help the company cross-sell other offerings and deepen relationships with providers and payers.
Cash burn is still negative, but the trajectory has improved from earlier periods. Free cash outflow remains substantial, yet it has become less severe than it was near the company’s weaker phase. For a business investing heavily in commercial scale-up, this suggests progress, though not completion, on the path toward a more self-supporting model.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


