Stock Analysis · Gold Fields Ltd (GFI)
Overview
Gold Fields Ltd is a large gold mining company with operations across several countries. Its business is straightforward: it explores for gold deposits, develops mines, extracts ore, processes it, and sells refined gold. The group also produces some copper as a by-product at certain operations, but gold is the economic core of the company.
The company’s revenue is mainly tied to the volume of gold sold and the market price of gold. Based on recent annual reporting and the company’s mine portfolio, revenue sources can be understood primarily by metal and then by operating region.
By product, the revenue mix is approximately:
- Gold: about 90% to 95% of revenue. This includes production from mines in Australia, South Africa, Ghana, Peru, and Chile.
- Copper and other by-products: about 5% to 10% of revenue. This is mainly linked to by-product output from mines where metals are recovered alongside gold.
By geography and operating assets, the contribution can shift year to year depending on mine performance, grades, and commodity prices. In broad terms, Australia is a major earnings base, with important contributions from Ghana and South Africa, while Salares Norte in Chile has become increasingly relevant as a newer project ramps up.
Gold Fields is not a royalty company or a financial intermediary; it is an operator with direct exposure to mining costs, mine life, reserve replacement, permitting, labor, and local-country conditions. That makes the business more cyclical than many non-mining sectors, but also gives it strong leverage when gold prices rise.
The recent financial flow shows a notable step-up in revenue, operating income, and net income over the past two years, with margins expanding faster than costs. Interest expense also remained modest relative to operating profit, which points to a healthier balance between growth spending and financial discipline than many miners achieve during expansion phases.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Gold | |
| Market Cap ⓘ | $32.38B | |
| Beta ⓘ | 0.64 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 7.45 | 16.90 |
| P/B Ratio ⓘ | 3.65 | 1.65 |
| FCF Yield ⓘ | 19.16% | 5.76% |
| Dividend Yield ⓘ | 5.92% | 2.13% |
| EBIT / EV ⓘ | 26.43% | 6.30% |
| PEG ⓘ | 11.59 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 78.90% | 11.10% |
| RPS Growth (5Y CAGR) ⓘ | 20.14% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -13.47% |
| BVPS Growth (5Y CAGR) ⓘ | 18.55% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | 15.40% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | 61.07% | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | 21.70% | 6.08% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 69.65% | 9.26% |
| ROA (Latest) ⓘ | 48.88% | 4.91% |
| ROIC (5Y Median) ⓘ | 29.95% | 7.70% |
| ROA (5Y Median) ⓘ | 10.65% | 3.86% |
| Net Debt / EBIT (Latest) ⓘ | 0.04 | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | 0.70 | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | 0.04 | 0.95 |
| Net Debt / Assets ⓘ | 2.80% | 13.69% |
| EBITDA / Interest ⓘ | 61.11 | 12.34 |
| Operating Margin (Latest) ⓘ | 56.45% | 13.20% |
| Operating Margin (5Y Median) ⓘ | 33.01% | 11.80% |
| Debt to Equity (Latest) ⓘ | 29.35% | 40.56% |
| Profit Margin (Latest) ⓘ | 38.65% | 6.43% |
| Free Cash Flow (Latest) ⓘ | $6.20B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +182.22% | +68.89% |
| 12M Return (excl. last month) ⓘ | +20.70% | +30.21% |
| 6M Return ⓘ | -27.46% | -4.16% |
| Price vs. 200-Day MA ⓘ | -15.47% | -1.27% |
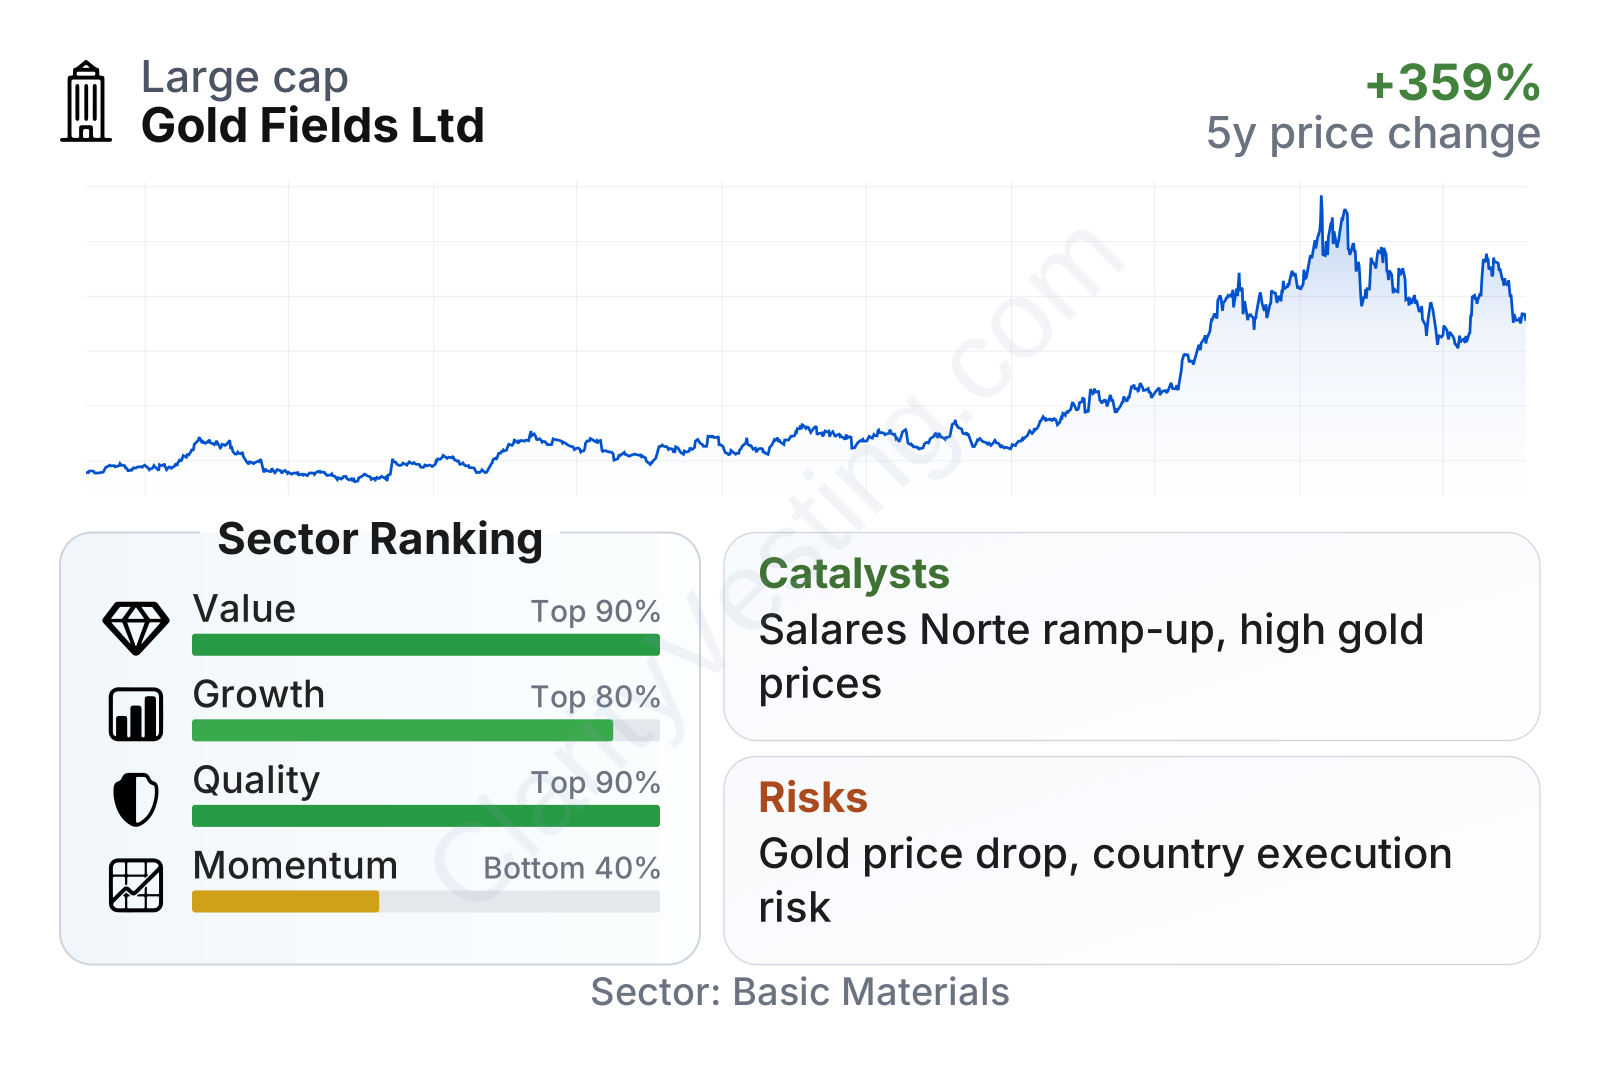
Gold Fields stands out as a large company in the gold mining industry, with a relatively low share-price volatility profile for the sector. The overall metric profile is strong in value, quality, and growth versus most peers, while recent price momentum has weakened after a very strong multi-year run. The combination of low earnings multiples, high free cash flow yield, strong margins, and limited net debt suggests a business that is currently producing unusually strong operating and cash results compared with much of the sector.
Growth
Gold mining is not a classic high-volume growth industry, because global supply is constrained by geology, permitting, capital intensity, and long development timelines. However, it is a sector that can grow in value when gold prices rise, when new mines come online, or when a company improves production and costs. In that context, Gold Fields has been operating in a favorable environment. Gold remains supported by central bank demand, geopolitical uncertainty, inflation concerns, and the metal’s role as a reserve asset.
Gold Fields’ strategy for future growth is centered on maintaining production from established mines while adding new output from development projects and extending mine lives through reserve replacement. The major strategic point in recent years has been the build-out and ramp-up of Salares Norte in Chile, which is important because a successful ramp can add meaningful production and diversify the asset base further. For a mining company, a new mine reaching stable output can materially change cash generation.
The company also benefits from having operations spread across multiple countries rather than depending on a single flagship mine. That does not remove operational risk, but it reduces the chance that one local issue alone defines the whole business. Over the last five years, the company’s growth profile has improved clearly, with revenue per share, book value per share, margins, free cash flow, and dividends all rising faster than sector medians.
Recent revenue growth has accelerated sharply after a more uneven period earlier in the cycle. That suggests the current earnings base is not only benefiting from strong gold prices, but also from improving operating contribution from the asset portfolio.
Cash generation has also become a major support for the investment case. Free cash flow has moved from solid to very strong, which matters because miners often report accounting profits without translating them into surplus cash after sustaining capital needs. Here, the recent pattern points to a company with stronger financial flexibility for dividends, debt management, and project funding.
A notable recent opportunity is the company’s exposure to a gold price environment that remains historically supportive. For a miner with high operating margins, even modest changes in realized gold prices can have a large effect on earnings and cash flow. If new production normalizes while gold remains elevated, Gold Fields could continue showing outsized cash profitability compared with its own history.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


