Stock Analysis · Griffon Corporation (GFF)
Overview
Griffon Corporation is a diversified industrial company focused mainly on home- and building-related products. Its operations are concentrated in two core segments: residential garage doors and rolling steel doors through Clopay, and tools and outdoor lifestyle products through The AMES Companies. In recent years, Griffon simplified its structure and became more focused on businesses tied to housing, repair and remodel activity, commercial building access products, and consumer lawn and garden needs.
The company’s revenue is primarily generated from the following sources:
- Home and Building Products: approximately 60% of revenue in recent fiscal years. This segment includes residential sectional garage doors, commercial rolling steel doors, and related components and services, mainly sold under the Clopay brand.
- Consumer and Professional Products: approximately 40% of revenue. This business includes lawn and garden tools, long-handled tools, snow tools, watering products, wheelbarrows, planters, and outdoor living products through The AMES Companies and related brands.
This mix matters because the garage door business tends to carry stronger margins and benefits from both new residential construction and replacement demand, while the tools and outdoor products business adds scale and broad retail exposure but is usually more seasonal and more sensitive to consumer spending patterns.
The multi-year financial flow shows a useful trend: revenue has gradually declined from the 2022 peak, but gross profit has held up comparatively well, suggesting a more favorable product mix and pricing discipline. The larger issue has been below the gross profit line, where interest expense and swings in operating costs have had an outsized effect on net income.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Building Products & Equipment | |
| Market Cap ⓘ | $4.23B | |
| Beta ⓘ | 1.44 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 19.88 | 22.10 |
| P/B Ratio ⓘ | 32.47 | 1.97 |
| FCF Yield ⓘ | 6.80% | 6.38% |
| Dividend Yield ⓘ | 0.94% | 1.94% |
| EBIT / EV ⓘ | 7.59% | 4.79% |
| PEG ⓘ | 0.54 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 7.00% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | 6.13% | 7.81% |
| EPS Growth (5Y CAGR) ⓘ | -0.43% | -13.06% |
| BVPS Growth (5Y CAGR) ⓘ | -43.11% | 6.14% |
| Margin Growth (5Y Trend) ⓘ | 1.24% | 0.88% |
| FCF Growth (5Y CAGR) ⓘ | 41.93% | 11.01% |
| DPS Growth (5Y CAGR) ⓘ | 27.56% | 9.48% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 19.07% | 10.84% |
| ROA (Latest) ⓘ | 10.34% | 5.41% |
| ROIC (5Y Median) ⓘ | 7.69% | 9.38% |
| ROA (5Y Median) ⓘ | 2.97% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | 2.81 | 2.08 |
| Net Debt / EBIT (5Y Median) ⓘ | 5.47 | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | 2.51 | 1.39 |
| Net Debt / Assets ⓘ | 66.81% | 19.28% |
| EBITDA / Interest ⓘ | 5.50 | 9.58 |
| Operating Margin (Latest) ⓘ | 19.70% | 10.50% |
| Operating Margin (5Y Median) ⓘ | 8.86% | 10.29% |
| Debt to Equity (Latest) ⓘ | 1035.18% | 65.48% |
| Profit Margin (Latest) ⓘ | 7.00% | 6.67% |
| Free Cash Flow (Latest) ⓘ | $287.78M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +139.24% | +61.68% |
| 12M Return (excl. last month) ⓘ | +22.29% | +12.58% |
| 6M Return ⓘ | +11.84% | 0.00% |
| Price vs. 200-Day MA ⓘ | +4.79% | +0.02% |
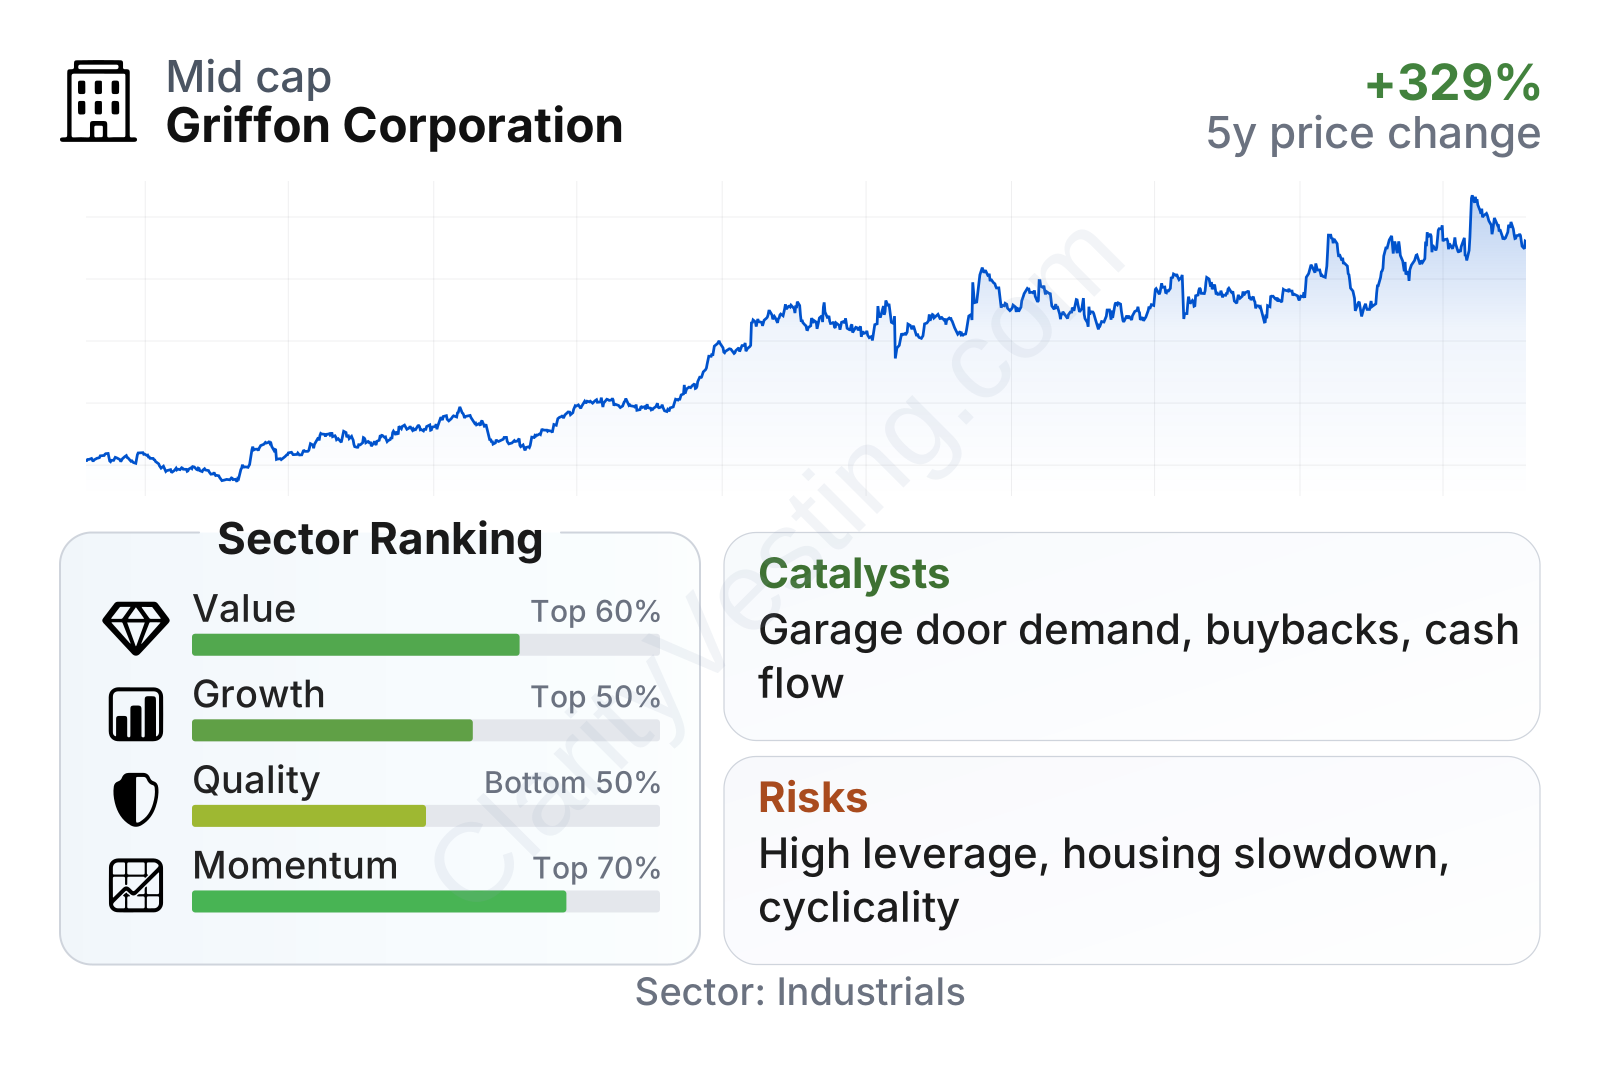
Griffon is a mid-sized industrial company with a stock that has been much stronger than the broader sector over the last several years, although that strength has come with above-average volatility. On valuation, its earnings multiple is slightly below the sector median, while free cash flow yield and EBIT relative to enterprise value look somewhat stronger than average. Growth is more mixed: recent sales growth trails the sector median, but free cash flow growth over a longer period has been notably stronger. Quality is the most complicated area. Current returns on capital and assets are solid, and operating margin is well above the sector median, but leverage remains elevated and weighs on the overall quality profile.
Growth
Griffon operates in end markets that are mature, but not stagnant. Residential garage doors, repair and remodel, commercial access products, and lawn and garden tools are not fast-growing technology niches, yet they can produce durable demand over long periods. The attractive part of this setup is that a large share of demand can come from replacement cycles and maintenance needs rather than purely from new construction, which gives the business some resilience.
Its strategy for growth is centered less on dramatic expansion and more on sharpening the portfolio, emphasizing categories with stronger brands and better margins, improving pricing, and converting earnings into cash. That approach makes sense for a company in practical product categories where operational execution matters more than disruption.
Recent revenue trends show a business that has moved through a weaker patch rather than one in uninterrupted expansion. Sales growth turned negative in several periods after the post-pandemic surge, and the most recent quarters indicate a meaningful slowdown. That said, the pattern also suggests Griffon is cycling through difficult comparisons and housing-related softness rather than facing a clearly broken business model.
Cash generation is one of the more encouraging parts of the picture. Free cash flow moved from negative territory a few years ago to a sustained positive level near the high hundreds of millions on a trailing basis, and it has stayed relatively stable even as revenue growth became uneven. For a long-term perspective, that is important because it supports debt reduction, dividends, and share repurchases without relying entirely on accounting earnings.
A major catalyst for future growth is a normalization in U.S. housing activity, especially repair and remodel demand and residential construction trends that influence garage door volumes. Another potential driver is continued margin improvement at Clopay and better execution across AMES. Griffon has also been active with capital returns and portfolio management in recent years, and that can amplify per-share results if operating performance remains stable.
Recent company communications have also highlighted ongoing share repurchases, disciplined capital allocation, and attention to higher-margin categories. None of these guarantees faster revenue growth, but they do increase the odds that modest top-line progress can still translate into stronger per-share performance over time.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


