Stock Analysis · Freightways Limited (FTWYF)
Overview
Freightways Limited is a New Zealand-based transport and business services group. Its core activity is moving parcels, documents, and freight around New Zealand, while also providing supporting information-management services such as records storage, secure document destruction, and digital solutions. The company has built its position around time-sensitive deliveries and repeat-use services for business customers, which makes its operations more recurring than a pure one-off freight operator.
The business is generally organized around two main operating areas, with express package and business mail activities contributing the larger share of revenue, and information management making up a smaller but still meaningful portion. Based on recent company reporting, the revenue mix is approximately:
- Express package and business mail: about 75% to 80% — courier deliveries, express parcels, business mail, and related logistics services across New Zealand and selected regional markets.
- Information management: about 20% to 25% — physical records storage, secure shredding, digital document services, and other business information solutions.
This mix matters because it gives Freightways exposure to both everyday parcel demand and sticky business-service contracts. The transport side benefits from e-commerce, healthcare, and business-to-business deliveries, while the records and secure destruction activities can provide steadier customer retention and cash flow.
Over the last several years, revenue has trended upward overall, and the latest annual period shows another step higher in sales, operating income, and net profit. That suggests the company has managed to expand despite a mixed economic backdrop for transport and logistics operators.
The operating picture shows a business that has been growing its top line at a solid pace, while earnings have improved more gradually. In other words, Freightways appears to be adding volume and revenue faster than it is expanding margins, which is important when assessing long-term returns from a logistics company.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Integrated Freight & Logistics | |
| Market Cap ⓘ | $1.34B | |
| Beta ⓘ | 0.66 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 24.10 | 22.10 |
| P/B Ratio ⓘ | 2.41 | 1.97 |
| FCF Yield ⓘ | N/A | 6.38% |
| Dividend Yield ⓘ | 6.02% | 1.94% |
| EBIT / EV ⓘ | 4.59% | 4.79% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 18.80% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | 11.63% | 7.81% |
| EPS Growth (5Y CAGR) ⓘ | -41.61% | -13.06% |
| BVPS Growth (5Y CAGR) ⓘ | 9.56% | 6.14% |
| Margin Growth (5Y Trend) ⓘ | -3.76% | 0.88% |
| FCF Growth (5Y CAGR) ⓘ | 12.28% | 11.01% |
| DPS Growth (5Y CAGR) ⓘ | 4.00% | 9.48% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 10.84% |
| ROA (Latest) ⓘ | N/A | 5.41% |
| ROIC (5Y Median) ⓘ | 13.89% | 9.38% |
| ROA (5Y Median) ⓘ | 6.10% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 2.08 |
| Net Debt / EBIT (5Y Median) ⓘ | 1.69 | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 1.39 |
| Net Debt / Assets ⓘ | 19.47% | 19.28% |
| EBITDA / Interest ⓘ | N/A | 9.58 |
| Operating Margin (Latest) ⓘ | N/A | 10.50% |
| Operating Margin (5Y Median) ⓘ | 11.28% | 10.29% |
| Debt to Equity (Latest) ⓘ | N/A | 65.48% |
| Profit Margin (Latest) ⓘ | 6.40% | 6.67% |
| Free Cash Flow (Latest) ⓘ | N/A | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +82.74% | +61.68% |
| 12M Return (excl. last month) ⓘ | +71.64% | +12.58% |
| 6M Return ⓘ | -7.96% | 0.00% |
| Price vs. 200-Day MA ⓘ | +0.51% | +0.02% |
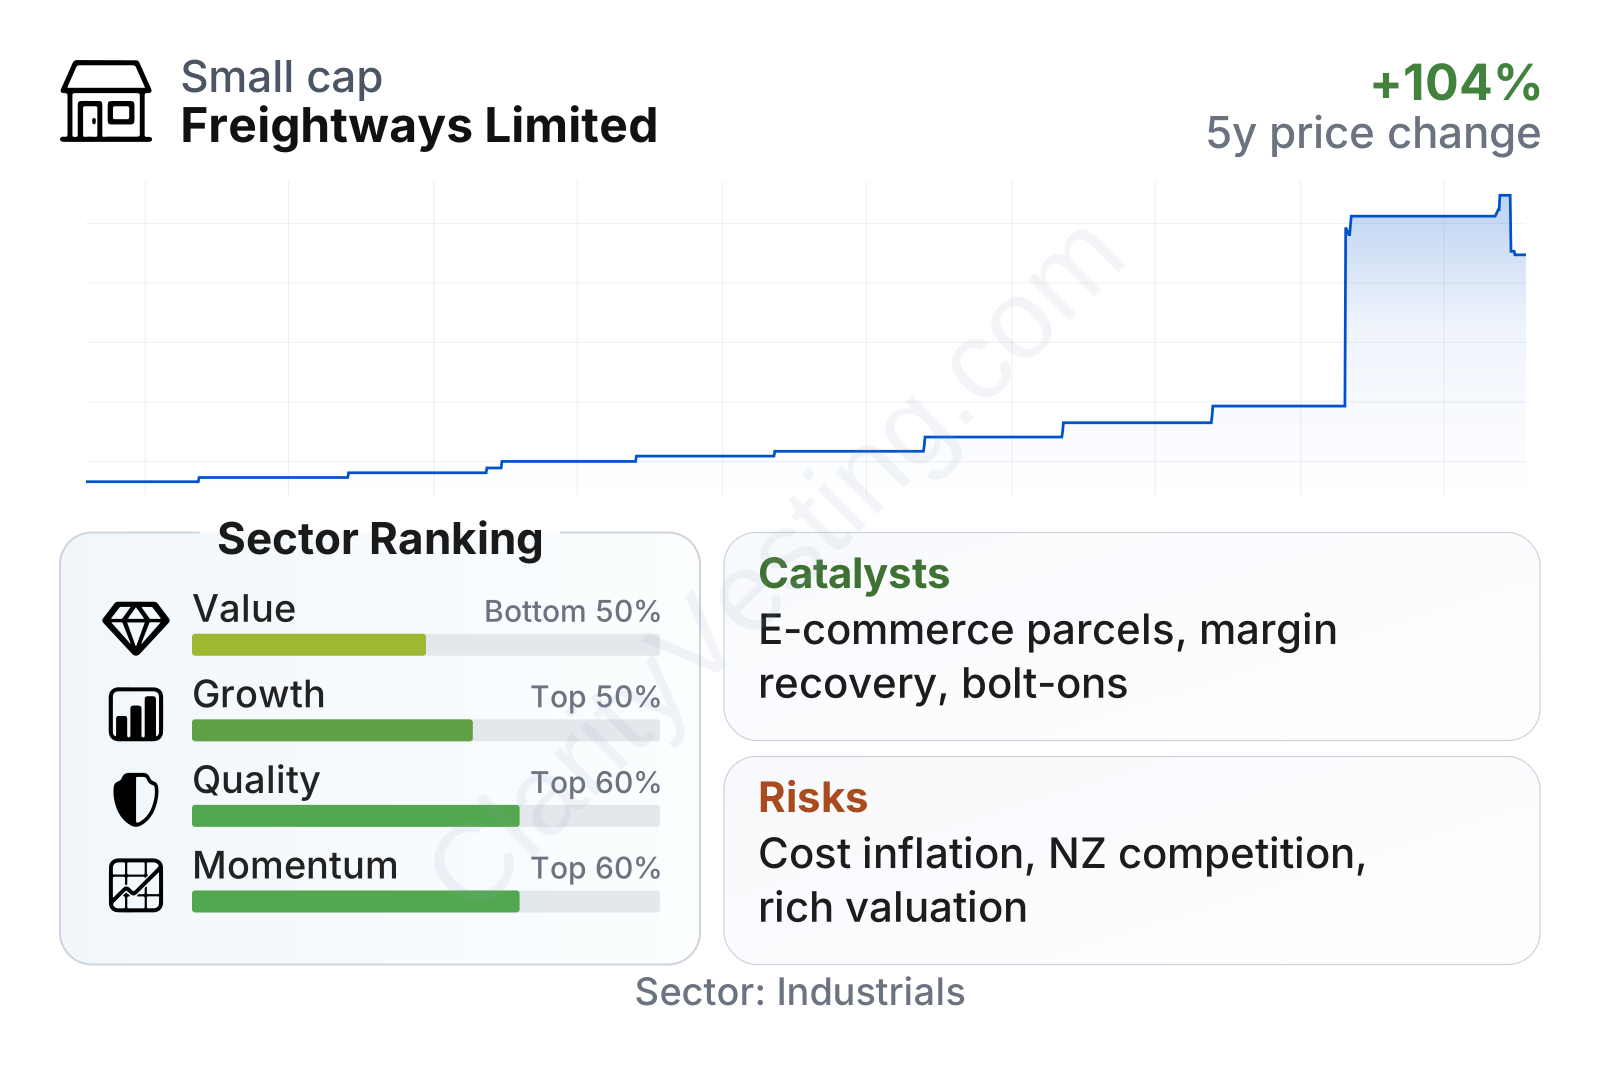
Freightways is a mid-sized industrial company with a relatively low share-price volatility profile, as shown by a beta below 1. The stock’s longer-term price trend has been strong, including a sharp re-rating in 2026, although the past six months have been softer than the broader sector. That combination often suggests the market has already recognized improving business quality, but is now weighing how much of that progress is already reflected in the share price.
On valuation, the stock screens somewhat richer than the sector median on earnings and book value multiples. At the same time, the dividend yield is clearly above the sector norm, which can make the overall profile look more balanced than the headline P/E alone would suggest.
On operating quality, Freightways stands out more favorably. Its five-year returns on invested capital and assets are above sector medians, and leverage appears controlled rather than stretched. Profitability is respectable, but not exceptional, and the main weak point in the table is that earnings growth has not kept pace with revenue growth over the last five years. That fits the broader pattern of a company with sound operations and cash generation, but some pressure on margins and earnings conversion.
Growth
Freightways operates in a sector with durable long-term demand drivers. Parcel volumes are supported by e-commerce, time-sensitive healthcare distribution, outsourced business delivery needs, and the general shift toward faster fulfillment. Information management is not a high-growth field in the same way, but it tends to be sticky, service-based, and operationally defensive. Together, those areas create a business model with both growth exposure and a stabilizing element.
The company’s strategy also makes practical sense for long-term expansion. Freightways has historically grown through a combination of network density, bolt-on acquisitions, and service specialization. In logistics, scale in a focused geography can create real advantages: better route economics, stronger service reliability, and deeper customer relationships. In New Zealand, Freightways is widely recognized as one of the key operators in express package and related services, which gives it meaningful market relevance even if it is not competing on a global scale.
A notable positive is that recent growth has been stronger than the sector median on revenue and free cash flow trends. Revenue growth near 19% year over year in the latest metrics, along with double-digit five-year revenue-per-share and free-cash-flow growth, points to an enterprise that is still expanding rather than merely defending a mature footprint.
There is also a potential operating catalyst in margin normalization. Recent annual figures show revenue, operating income, and net income all moving higher again into fiscal 2026. If management can keep volume growth while protecting pricing and costs, even modest margin improvement could have an outsized effect on earnings because the delivery network has a meaningful fixed-cost base.
Another favorable element is dividend support. Freightways offers a dividend yield materially above the sector median, and while dividend growth has been slower than some peers, the payout adds to the total-return profile and may help frame the company as a cash-generating infrastructure-like operator rather than a purely cyclical freight name.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


