Stock Analysis · Flotek Industries Inc (FTK)
Overview
Flotek Industries is a small U.S. energy technology company serving oil and gas producers, operators, and related industrial customers. The business has changed meaningfully over the last several years. It is no longer mainly a traditional oilfield chemicals supplier. Today, its identity is increasingly tied to data, chemistry, and field performance monitoring, with a particular focus on helping customers measure and reduce the environmental impact of energy operations while also improving well performance.
Based on the company’s recent filings and investor materials, revenue comes from two main operating segments, with the laboratory and analytics business now carrying much more strategic weight than its size alone might suggest.
- Chemistry Technologies: approximately 70% to 80% of revenue in recent periods. This segment includes specialty chemicals, solvents, and related products used in drilling, completion, production, and other energy applications.
- Data Analytics: approximately 20% to 30% of revenue in recent periods. This business includes water analysis, emissions and compositional testing, field sampling, and the company’s laboratory-based services that help customers monitor hydrocarbons, water, and methane-related performance.
The strategic center of gravity appears to be shifting toward higher-value analytics and recurring service work, especially after the company’s investments and transactions tied to its Verax-style testing and measurement capabilities. That matters because chemical sales can be more volume-driven and cyclical, while analytics can create stickier customer relationships if the company becomes embedded in compliance, monitoring, or optimization workflows.
The multiyear financial picture also shows a real turnaround. Revenue expanded sharply from 2021 through 2025, gross profit improved from very weak levels to much healthier levels, and the business moved from deep losses to sustained profitability. That does not remove risk, but it does show that Flotek is not the same company it was a few years ago.
The operating profile has improved considerably over time: revenue is much higher than it was in 2021, gross profit has widened, and net income turned positive after earlier losses. The more important point is not just growth, but that profit conversion is now materially better than during the company’s earlier restructuring phase.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Energy | |
| Industry | Oil & Gas Equipment & Services | |
| Market Cap ⓘ | $1.09B | |
| Beta ⓘ | 1.42 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 30.90 | 15.44 |
| P/B Ratio ⓘ | 8.35 | 1.73 |
| FCF Yield ⓘ | -0.47% | 8.20% |
| Dividend Yield ⓘ | N/A | 3.59% |
| EBIT / EV ⓘ | 3.26% | 7.46% |
| PEG ⓘ | 4.32 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 70.30% | 26.90% |
| RPS Growth (5Y CAGR) ⓘ | 16.69% | 6.90% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -15.73% |
| BVPS Growth (5Y CAGR) ⓘ | 17.30% | 6.07% |
| Margin Growth (5Y Trend) ⓘ | 80.41% | 0.58% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 1.86% |
| DPS Growth (5Y CAGR) ⓘ | -78.57% | 16.79% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 27.14% | 11.40% |
| ROA (Latest) ⓘ | 15.81% | 6.06% |
| ROIC (5Y Median) ⓘ | 10.09% | 10.30% |
| ROA (5Y Median) ⓘ | 6.40% | 5.42% |
| Net Debt / EBIT (Latest) ⓘ | 1.38 | 1.64 |
| Net Debt / EBIT (5Y Median) ⓘ | 0.69 | 1.83 |
| Net Debt / EBITDA (Latest) ⓘ | 1.22 | 1.08 |
| Net Debt / Assets ⓘ | 19.33% | 17.29% |
| EBITDA / Interest ⓘ | 7.80 | 9.64 |
| Operating Margin (Latest) ⓘ | 12.84% | 16.27% |
| Operating Margin (5Y Median) ⓘ | 6.55% | 20.39% |
| Debt to Equity (Latest) ⓘ | 43.50% | 54.76% |
| Profit Margin (Latest) ⓘ | 12.97% | 8.82% |
| Free Cash Flow (Latest) ⓘ | -$5.09M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +560.24% | +67.38% |
| 12M Return (excl. last month) ⓘ | +109.06% | +49.19% |
| 6M Return ⓘ | +85.58% | +7.07% |
| Price vs. 200-Day MA ⓘ | +31.10% | +9.56% |
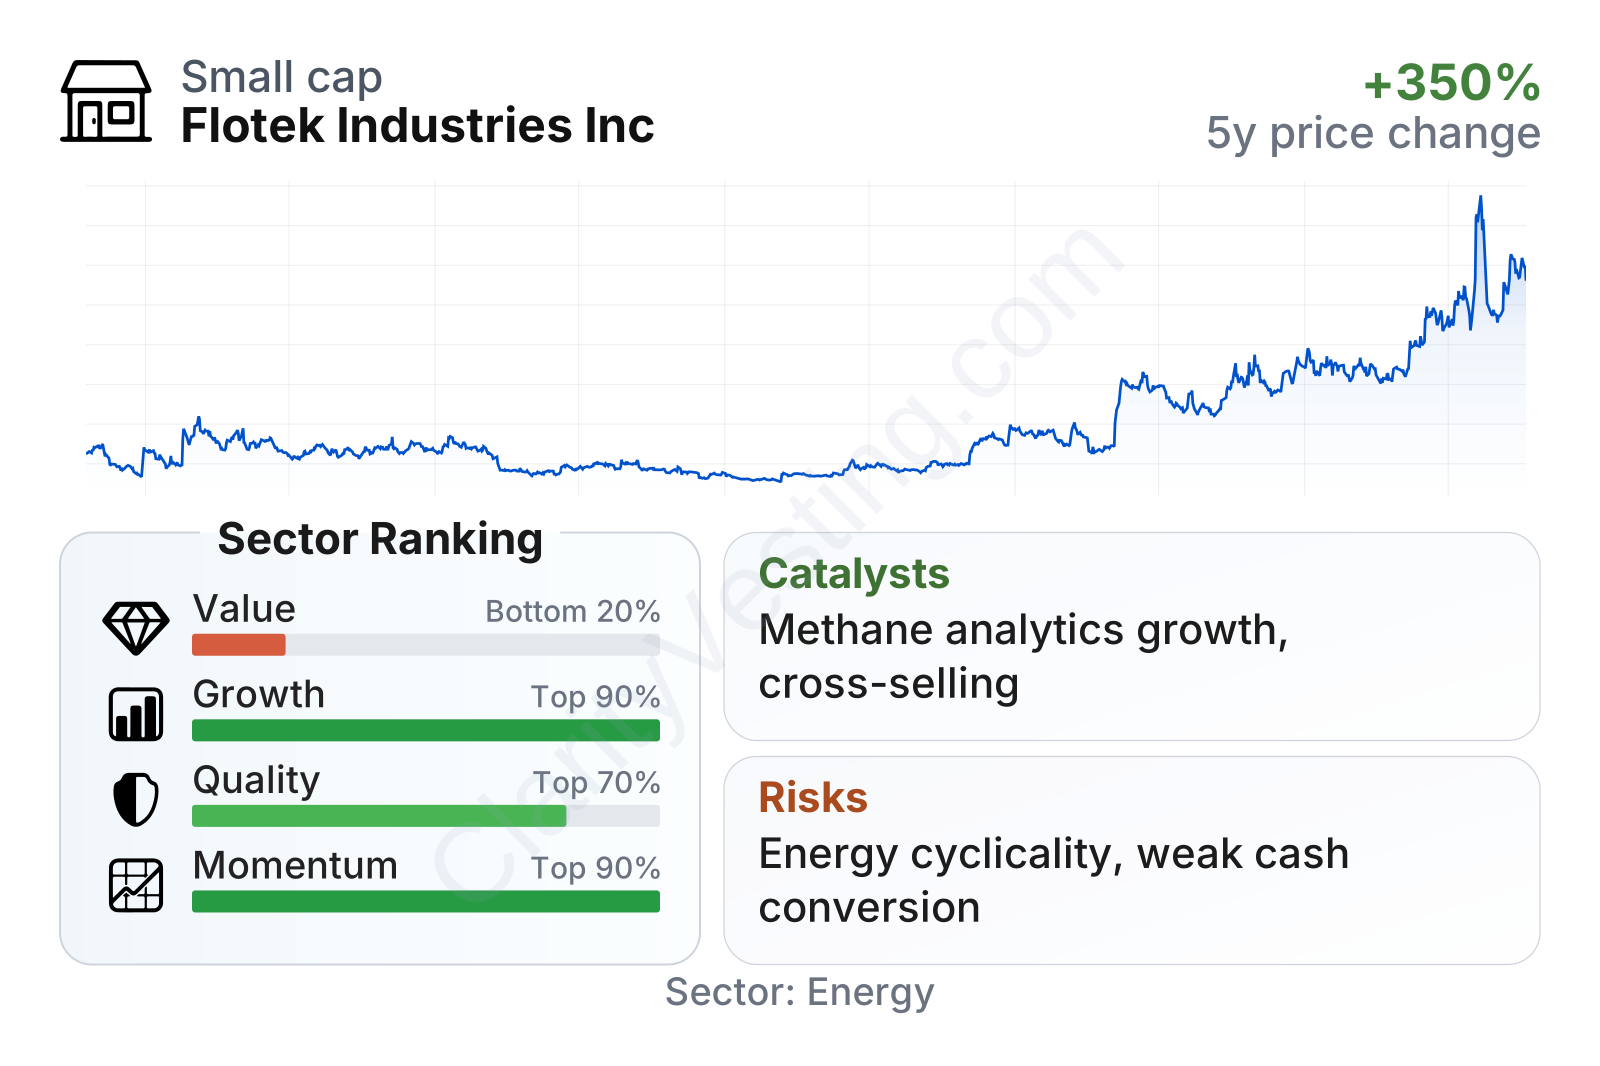
Flotek is now roughly a small-cap energy services company with a stock that has been very strong over the last three years, but also clearly volatile. The business ranks well on growth, profitability has improved versus much of its own history, and returns on capital are solid. At the same time, valuation metrics sit in the weaker part of the sector comparison, which means the market is already recognizing much of the operational progress.
Growth
Flotek operates in a part of the energy market that still has room for growth even if drilling activity itself stays cyclical. Producers increasingly need better chemical efficiency, water analysis, methane monitoring, and documented environmental measurements. Those needs come from several directions at once: tighter regulatory expectations, pressure from customers and capital providers, and the simple economic value of reducing waste and improving recovery. That gives Flotek exposure not only to oilfield activity, but also to the broader trend toward better measurement and operational transparency.
The company’s strategy broadly makes sense for future growth because it ties traditional chemistry products to data and lab services. In practical terms, that can make the offering more useful and potentially more defensible. A chemical supplier can be replaced more easily than a supplier that is also embedded in testing, monitoring, certification, and workflow data. If Flotek can keep linking chemistry performance with measurable field outcomes, it has a clearer path to differentiating itself from standard commodity-oriented service providers.
Recent revenue growth has been strong by sector standards, although not perfectly smooth. The company experienced very rapid expansion, then a cooling period, and then a reacceleration. The latest year-over-year pace stands far above the sector median, which supports the idea that Flotek is still in an active scaling phase rather than a mature, low-growth stage.
Cash generation is the main caveat inside the growth profile. Free cash flow has improved markedly from earlier deeply negative levels, briefly turned positive, and then slipped back slightly below zero on a trailing basis. That pattern suggests the company is closer to financial self-sufficiency than before, but not yet consistently there. For a smaller company pursuing expansion, that distinction matters because profitable growth is more durable when it is also cash-generative.
A meaningful catalyst is the rising commercial relevance of methane and hydrocarbon measurement. Flotek’s laboratory and field analysis capabilities may benefit if customers continue to demand verified data for emissions management, gas composition, and operational performance. Another catalyst is cross-selling: if the company can use analytics relationships to win chemistry work, or use chemistry customers to deepen testing and monitoring services, revenue per customer could rise without needing the same pace of new customer acquisition.
Recent company communications have also emphasized larger contracts, analytics adoption, and the broadening use of testing solutions across customers. For a business of Flotek’s size, even a handful of meaningful wins can have an outsized effect on growth rates and market perception.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


