Stock Analysis · TechnipFMC PLC (FTI)
Overview
TechnipFMC is an energy technology and services company focused mainly on offshore oil and gas projects. In simple terms, it helps energy producers design, build, install, and operate the equipment used on the seabed and at the surface to produce hydrocarbons, especially in deepwater environments. The company was created from the combination of FMC Technologies and Technip, and today it is best known for subsea production systems and integrated project execution.
Its business is organized around two main segments. Based on the latest annual reporting structure, revenue is primarily generated from:
- Subsea: approximately 84% of revenue. This includes subsea trees, manifolds, control systems, umbilicals, installation, and integrated engineering, procurement, construction, and installation work for offshore developments.
- Surface Technologies: approximately 16% of revenue. This business supplies wellhead systems, pressure control equipment, flowback, and related services used mainly for onshore and surface production activity.
The business mix matters because Subsea is not only the largest activity, but also the one most tied to long-cycle offshore projects that can support backlog visibility over several years. Surface Technologies is smaller and more exposed to shorter-cycle spending patterns, especially in North America.
Over the last few years, the company has moved from a weaker profitability profile to a much stronger one. Revenue has climbed from about $6.4 billion in 2021 to nearly $9.9 billion in 2025, while operating income and net income improved much faster than sales. That suggests the recent change has not been just a volume recovery, but also a margin and execution recovery.
The income flow shows a clear improvement since 2021: sales have increased steadily, operating expenses have grown much more slowly than revenue, interest expense has come down, and net income has expanded sharply after the weak 2022-2023 period. This points to a business that has become materially more efficient as activity levels recovered.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 04, 2026 | |
| Context | ||
| Sector | Energy | |
| Industry | Oil & Gas Equipment & Services | |
| Market Cap ⓘ | $26.99B | |
| Beta ⓘ | 0.74 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 24.06 | 14.57 |
| P/B Ratio ⓘ | 8.58 | 1.71 |
| FCF Yield ⓘ | 5.82% | 8.63% |
| Dividend Yield ⓘ | 0.29% | 3.77% |
| EBIT / EV ⓘ | 5.57% | 7.46% |
| PEG ⓘ | 2.59 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 9.00% | 27.35% |
| RPS Growth (5Y CAGR) ⓘ | 13.90% | 6.75% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -15.45% |
| BVPS Growth (5Y CAGR) ⓘ | 1.45% | 5.85% |
| Margin Growth (5Y Trend) ⓘ | 8.06% | 0.75% |
| FCF Growth (5Y CAGR) ⓘ | 25.17% | 3.62% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 16.85% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 32.73% | 11.33% |
| ROA (Latest) ⓘ | 11.40% | 6.03% |
| ROIC (5Y Median) ⓘ | 2.31% | 10.16% |
| ROA (5Y Median) ⓘ | 0.24% | 5.34% |
| Net Debt / EBIT (Latest) ⓘ | 0.16 | 1.62 |
| Net Debt / EBIT (5Y Median) ⓘ | 1.49 | 1.91 |
| Net Debt / EBITDA (Latest) ⓘ | 0.13 | 1.06 |
| Net Debt / Assets ⓘ | 2.42% | 17.29% |
| EBITDA / Interest ⓘ | 30.84 | 9.64 |
| Operating Margin (Latest) ⓘ | 14.98% | 16.32% |
| Operating Margin (5Y Median) ⓘ | 7.53% | 19.53% |
| Debt to Equity (Latest) ⓘ | 37.98% | 54.41% |
| Profit Margin (Latest) ⓘ | 11.28% | 8.79% |
| Free Cash Flow (Latest) ⓘ | $1.57B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +251.77% | +63.02% |
| 12M Return (excl. last month) ⓘ | +112.86% | +44.83% |
| 6M Return ⓘ | -2.97% | -1.02% |
| Price vs. 200-Day MA ⓘ | +2.89% | +5.18% |
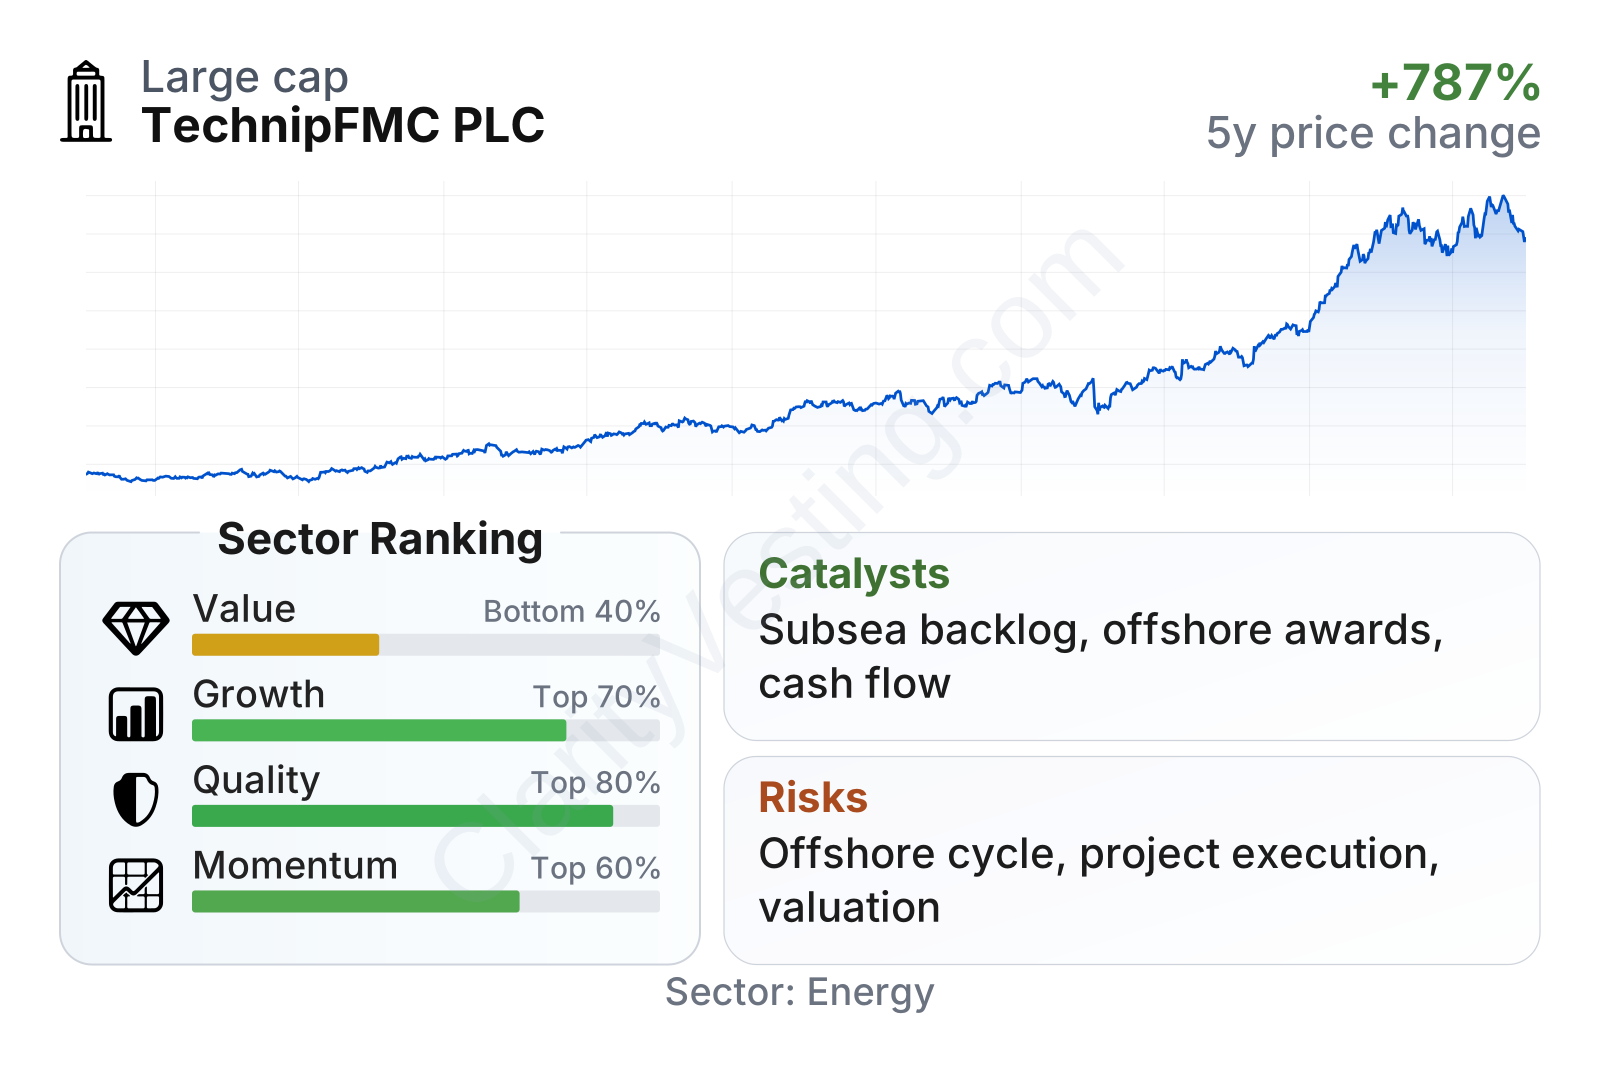
TechnipFMC is now a large energy equipment company with a market value around the upper end of its industry group and a beta below 1, which means the stock has recently been less volatile than the broader market on a statistical basis. The quality profile stands out more than the valuation profile. Profitability and returns on capital are strong versus the sector median, and leverage is relatively low. Growth is respectable, especially over a multi-year period, but the most recent year-over-year revenue pace is below the sector median. On valuation, the stock screens as less attractive than many peers, with higher earnings and book multiples and a lower cash flow yield than the sector median. In other words, the market is already recognizing much of the operational improvement.
The share price performance has been exceptionally strong over the past several years, rising many times from 2021 levels. That momentum reflects a major turnaround in earnings power, but it also means the market is no longer treating TechnipFMC like a distressed or cyclical laggard.
Growth
TechnipFMC operates in a part of the energy market that has regained importance: offshore and especially deepwater development. Large oil companies and national oil companies continue to need new supply, and offshore projects have become more competitive after years of cost reduction across the industry. Compared with shale, deepwater developments usually require more upfront engineering and equipment, but they can deliver large volumes over long periods. That fits TechnipFMC’s core capabilities well.
The company’s strategy is centered on integrated subsea development, standardization, and technology that lowers project costs and shortens development timelines for customers. Its “integrated” approach matters because operators increasingly want fewer interfaces across complex offshore projects. If TechnipFMC can provide subsea hardware together with engineering and installation coordination, it can become more embedded in customers’ project planning and potentially protect margins better than a pure equipment supplier.
Revenue growth has stayed positive for an extended period, though the pace has moderated from the stronger acceleration seen in 2023 and 2024. That is not necessarily a warning sign on its own for this kind of business: long-cycle offshore activity tends to produce steadier, less explosive growth than some shorter-cycle energy niches. The broader pattern still shows an expansion phase rather than a stalled one.
Cash generation is one of the strongest parts of the current picture. Free cash flow has risen sharply from modest levels in 2022 and 2023 to well above $1 billion on a trailing basis. For a long-term business assessment, this is important because cash flow confirms that the recent earnings improvement is not only an accounting effect. Stronger cash generation also gives the company more flexibility for debt reduction, shareholder returns, and investment in technology.
A meaningful catalyst is the sustained demand for subsea awards and the industry’s preference for projects with lower breakeven economics. TechnipFMC has highlighted a large addressable pipeline for subsea developments, and its iEPCI and integrated FEED offerings are designed to capture work earlier in the project cycle. Another favorable factor is the company’s exposure to international and offshore markets rather than relying mainly on U.S. shale, where activity can swing more abruptly.
Recent company updates have also pointed to continued order activity and strong backlog support in Subsea. For a business like this, backlog is especially relevant because it gives visibility into future revenue conversion over multiple years. As long as offshore final investment decisions remain active, TechnipFMC’s core segment appears to have a supportive demand backdrop.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


