Stock Analysis · Five Star Bancorp (FSBC)
Overview
Five Star Bancorp is a California-based regional bank. Through its banking subsidiary, Five Star Bank, it provides commercial banking services mainly to small and mid-sized businesses, professionals, real estate operators, and consumers in Northern California. In simple terms, the company makes money by gathering deposits from customers and using that funding to make loans, while also earning fees from banking services.
The business is still primarily a traditional bank, so its revenue is centered on interest income rather than a wide mix of unrelated activities. Based on the company’s recent annual reporting, the main revenue sources can be summarized as follows:
- Net interest income: approximately 85% to 90% of total revenue. This is the spread between interest earned on loans and securities and interest paid on deposits and borrowings.
- Noninterest income: approximately 10% to 15% of total revenue. This includes service charges, treasury management fees, and other banking-related fee income.
- Within lending activity, the largest loan categories are typically commercial real estate, commercial loans, and construction/land development, with consumer lending playing a much smaller role.
That concentration matters. Five Star Bancorp is not trying to be a national consumer bank or a capital markets platform. It is focused on relationship-based commercial banking in a specific geography, especially business lending and deposit gathering in California markets where local knowledge can matter.
The broader earnings picture has improved meaningfully since 2023. Revenue and net income recovered strongly in 2024 and expanded further in 2025, while operating profitability remained solid. That suggests the bank navigated the difficult regional banking environment better than many smaller peers, even though 2023 showed how quickly reported banking revenue can be pressured by funding costs and rate shifts.
The long-term direction is favorable: revenue and earnings flows are notably higher than they were a few years ago, and the business appears to be converting a larger revenue base into healthy profit. The main point to watch is not whether the bank can generate income, but whether deposit costs and credit quality stay under control as it grows.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Financial Services | |
| Industry | Banks - Regional | |
| Market Cap ⓘ | $1.04B | |
| Beta ⓘ | 0.54 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 12.65 | 12.26 |
| P/B Ratio ⓘ | 1.94 | 1.23 |
| FCF Yield ⓘ | 7.72% | 10.40% |
| Dividend Yield ⓘ | 2.22% | 3.02% |
| EBIT / EV ⓘ | 21.73% | 8.14% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 27.60% | 9.35% |
| RPS Growth (5Y CAGR) ⓘ | 19.66% | 12.19% |
| EPS Growth (5Y CAGR) ⓘ | -9.71% | -9.53% |
| BVPS Growth (5Y CAGR) ⓘ | 7.53% | 4.99% |
| Margin Growth (5Y Trend) ⓘ | -20.91% | -3.86% |
| FCF Growth (5Y CAGR) ⓘ | 26.44% | 4.81% |
| DPS Growth (5Y CAGR) ⓘ | -30.61% | 8.79% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 13.68% | 9.49% |
| ROE (Latest) ⓘ | 15.91% | 13.90% |
| ROA (Latest) ⓘ | 1.44% | 1.55% |
| ROIC (5Y Median) ⓘ | 12.44% | 7.86% |
| ROE (5Y Median) ⓘ | 17.73% | 12.17% |
| ROA (5Y Median) ⓘ | 1.40% | 1.30% |
| Net Debt / EBIT (Latest) ⓘ | 0.29 | 0.96 |
| Net Debt / EBIT (5Y Median) ⓘ | -4.64 | 0.73 |
| Net Debt / EBITDA (Latest) ⓘ | 0.28 | 0.92 |
| Operating Margin (Latest) ⓘ | 34.63% | 22.30% |
| Operating Margin (5Y Median) ⓘ | 32.78% | 24.63% |
| Debt to Equity (Latest) ⓘ | 15.64% | 58.56% |
| Profit Margin (Latest) ⓘ | 42.96% | 26.57% |
| Free Cash Flow (Latest) ⓘ | $80.49M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +139.73% | +88.33% |
| 12M Return (excl. last month) ⓘ | +41.90% | +19.38% |
| 6M Return ⓘ | +7.11% | +4.75% |
| Price vs. 200-Day MA ⓘ | +2.48% | +3.50% |
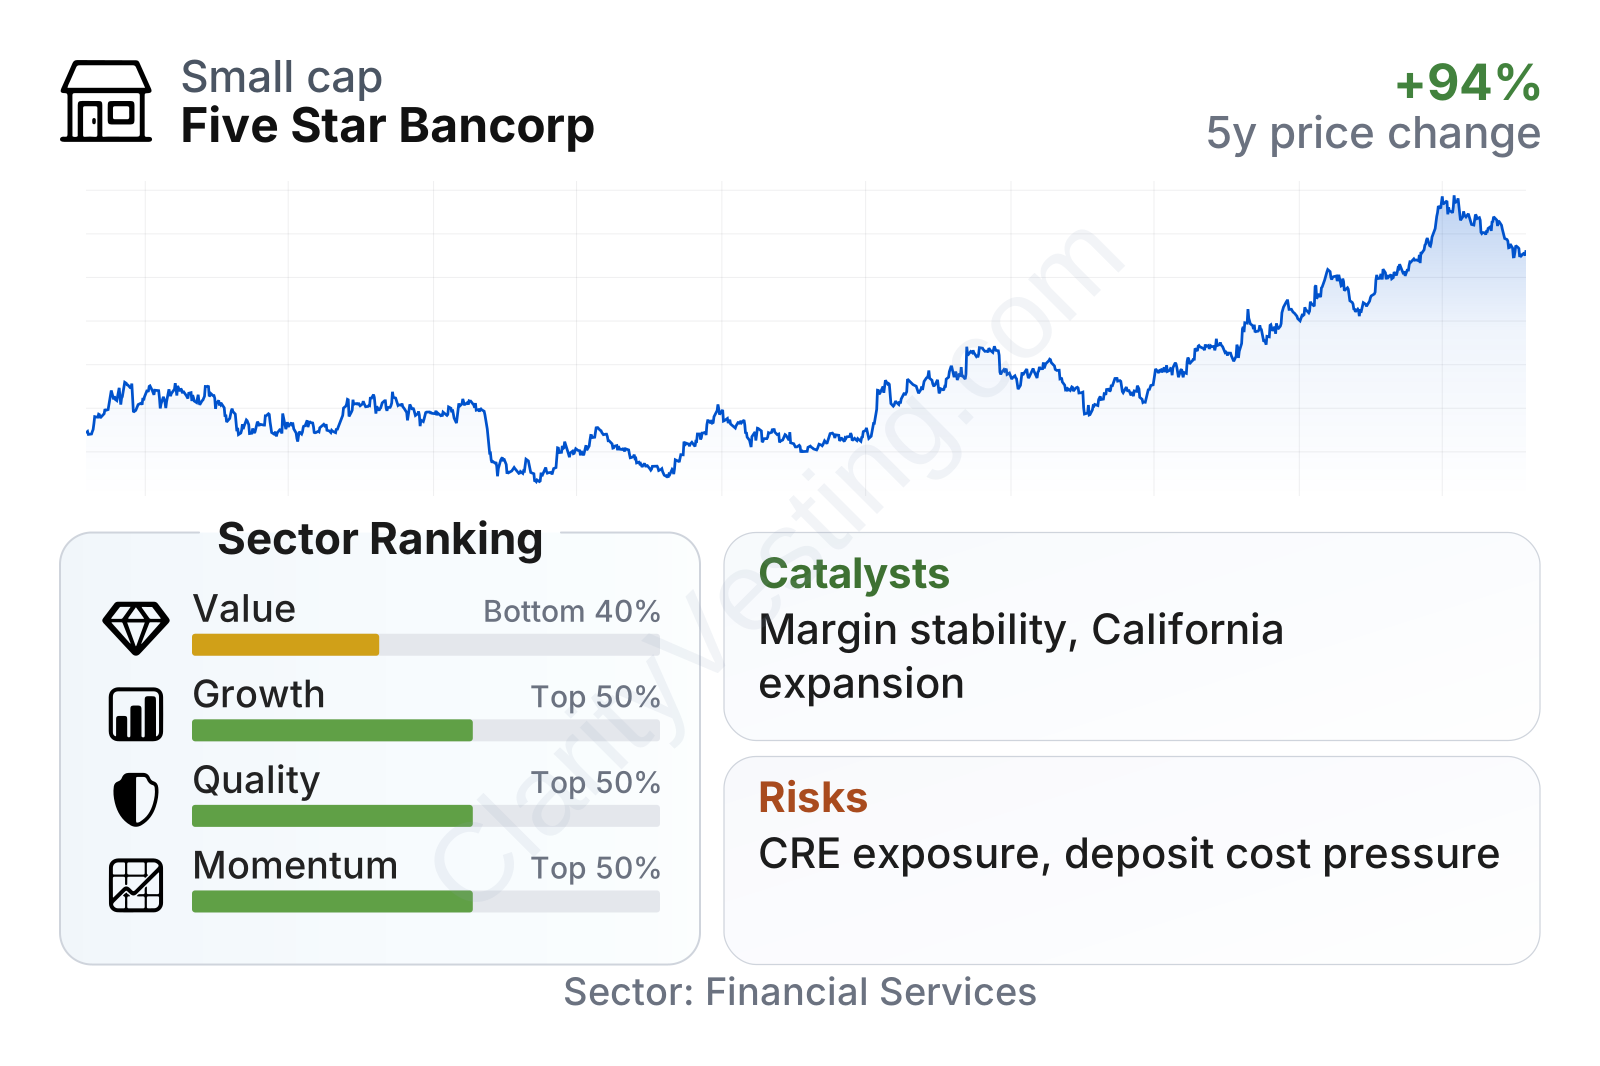
Five Star Bancorp is a smaller public bank by market value, with relatively low share-price volatility. Its overall profile stands out more for quality and growth than for deep value. Profitability metrics are generally above sector medians, revenue growth has been stronger than many regional-bank peers, and leverage looks conservative. On the other hand, the stock no longer screens as especially cheap on book value, the dividend yield is below the sector median, and recent price strength has already reflected some of the improving fundamentals.
The stock-price history also shows a pattern common in regional banks over the last several years: a sharp drop during the 2023 banking stress, followed by a strong recovery. Since then, the shares have climbed well above prior lows, indicating that the market has become more confident in the bank’s balance sheet and earnings resilience.
Growth
Five Star Bancorp operates in regional banking, which is not a fast-growing sector in the way software or semiconductors can be, but it can still offer meaningful long-term expansion when a bank gains deposits, adds lending relationships, and broadens its presence in attractive local markets. California remains one of the largest banking markets in the country, and business-oriented community and regional banks can grow if they maintain strong underwriting and local customer relationships.
The company’s strategy appears straightforward and sensible: focus on commercial clients, maintain a strong deposit franchise, and grow in selected California markets rather than stretching into unrelated businesses. That approach can work well when management is disciplined, because commercial customers often bring multiple services at once: deposits, operating accounts, treasury management, and borrowing needs.
Growth has looked better recently than the bank’s longer-term earnings trend alone might suggest. Revenue growth over the last year was well above the sector median, and five-year revenue per share growth has also outpaced many peers. Even so, earnings per share over a five-year span have been uneven, which points to the reality that bank earnings can be shaped heavily by rate cycles, funding costs, and credit provisions rather than by loan growth alone.
The earnings pattern shows that profitability has not moved in a straight line. EPS improved through 2023, dipped in 2024, and recovered in 2025. That kind of fluctuation is normal for banks, but it also means future growth depends on protecting margins rather than simply increasing asset size.
Book value per share has moved upward over time, especially after 2023. For a bank, this matters because book value is a rough measure of the underlying capital base supporting future lending and loss absorption. Steady growth here is usually a constructive sign, particularly when it is accompanied by solid returns on equity rather than being driven only by balance-sheet expansion.
A meaningful catalyst is the interest-rate environment. If deposit pricing stabilizes and loan yields remain favorable, regional banks like Five Star Bancorp can see better net interest margins and stronger earnings conversion. Another potential catalyst is continued market-share gains from customers that prefer a local commercial bank over a very large national institution. The company has also highlighted expansion in business banking and treasury management capabilities, which can help deepen relationships and make deposits stickier.
Recent company updates have pointed to continued operating momentum, with healthy profitability and capital levels. For long-term analysis, the key opportunity is not a single headline event but the possibility that Five Star Bancorp keeps compounding book value and earnings through disciplined commercial banking in its existing footprint.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


