Stock Analysis · Fervo Energy Company (FRVO)
Overview
Fervo Energy is a geothermal energy developer focused on building next-generation geothermal power projects in the United States. In simple terms, the company drills wells and uses underground heat to generate electricity. What makes Fervo different from traditional geothermal operators is its use of techniques adapted from the oil and gas industry, especially horizontal drilling, advanced well design, and real-time monitoring. The goal is to make geothermal viable in more locations than the limited areas where conventional geothermal has historically worked.
The company’s long-term business model is centered on developing, owning, and supplying geothermal power and related energy services. At this stage, however, reported revenue remains extremely small compared with the scale of its spending, which shows that Fervo is still in a build-out phase rather than a mature operating phase.
Based on public disclosures, Fervo’s economic model appears to rely on a few core sources of future revenue, although the company has not yet disclosed a stable, mature revenue mix with reliable percentages. The main sources are likely to be:
- Electricity sales under long-term power purchase agreements: expected to become the dominant source over time as projects enter operation. These contracts typically involve selling power to utilities, large corporate buyers, or grid-serving counterparties.
- Project-level development and operating income: this can include value created by developing geothermal assets, bringing them to commercial operation, and potentially retaining ownership stakes.
- Grid-support and clean energy attributes: geothermal projects may also generate additional value through capacity-style payments or environmental credits, depending on market structure and contract design.
- Technology and service-related opportunities: over the longer term, Fervo’s drilling, reservoir, and monitoring expertise could support partnerships or other commercial arrangements, but this is not yet a clearly established revenue contributor.
At the moment, the key takeaway is straightforward: Fervo is not yet a revenue-established utility. It is better understood as an early-stage infrastructure and technology-enabled energy developer working to convert promising projects into long-lived contracted cash flow.
The operating profile reflects that early-stage status. Revenue remains negligible while operating expenses and interest costs have risen sharply, producing widening losses. That pattern is common in capital-intensive project development, but it also means the investment case depends much more on future execution than on current earnings power.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Utilities | |
| Industry | Utilities - Renewable | |
| Market Cap ⓘ | $3.53B | |
| Beta ⓘ | N/A | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 17.28 |
| P/B Ratio ⓘ | 1.24 | 1.51 |
| FCF Yield ⓘ | -18.41% | 0.65% |
| Dividend Yield ⓘ | N/A | 3.77% |
| EBIT / EV ⓘ | -2.17% | 5.01% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | N/A | 6.10% |
| RPS Growth (5Y CAGR) ⓘ | N/A | 3.87% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -11.30% |
| BVPS Growth (5Y CAGR) ⓘ | N/A | 4.23% |
| Margin Growth (5Y Trend) ⓘ | N/A | 3.57% |
| FCF Growth (5Y CAGR) ⓘ | N/A | -8.84% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 4.84% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 6.53% |
| ROA (Latest) ⓘ | N/A | 3.20% |
| ROIC (5Y Median) ⓘ | N/A | 5.95% |
| ROA (5Y Median) ⓘ | N/A | 2.75% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 7.13 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 7.23 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 4.31 |
| Net Debt / Assets ⓘ | -50.02% | 38.42% |
| EBITDA / Interest ⓘ | N/A | 4.58 |
| Operating Margin (Latest) ⓘ | -38166.67% | 20.83% |
| Operating Margin (5Y Median) ⓘ | N/A | 20.08% |
| Debt to Equity (Latest) ⓘ | 12.11% | 137.69% |
| Profit Margin (Latest) ⓘ | N/A | 11.37% |
| Free Cash Flow (Latest) ⓘ | -$650.20M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | N/A | +52.37% |
| 12M Return (excl. last month) ⓘ | N/A | +8.84% |
| 6M Return ⓘ | N/A | -3.95% |
| Price vs. 200-Day MA ⓘ | N/A | -0.79% |
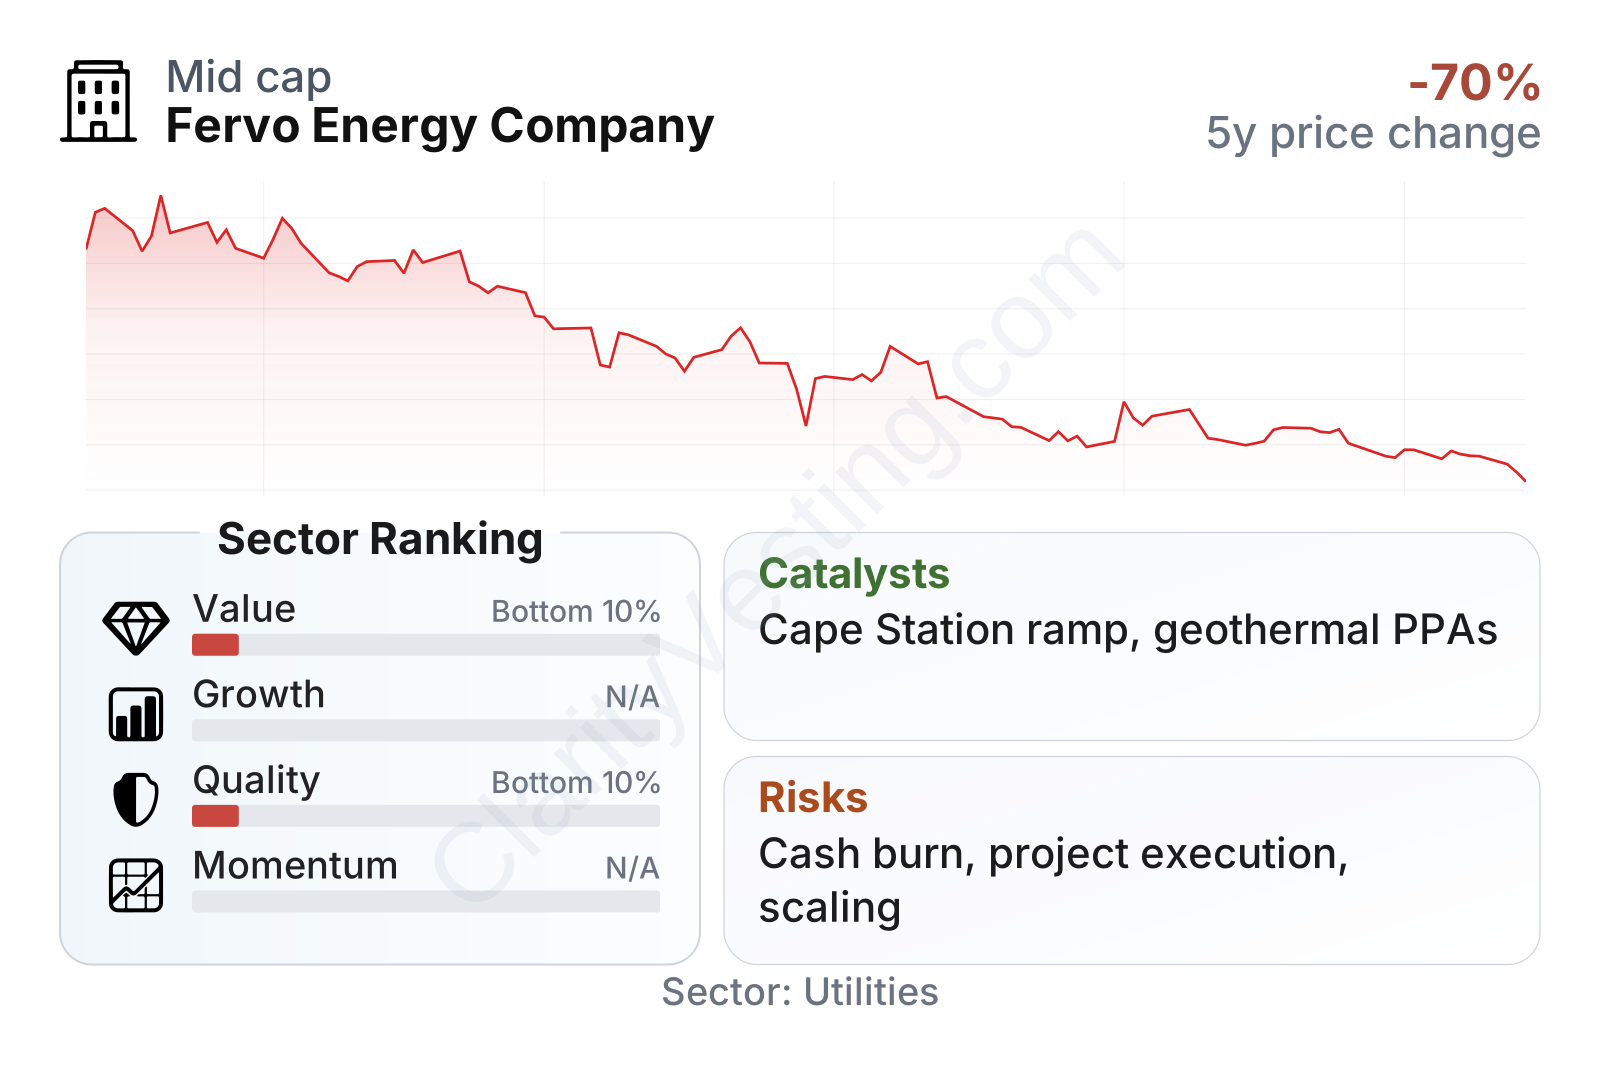
The current financial profile is weak by traditional utility standards. Relative to the broader renewable utility group, Fervo ranks near the bottom on value and quality measures, which is not surprising for a company still pre-scale and loss-making. Free cash flow is deeply negative, operating margins are far below sector norms, and profitability metrics do not yet show a functioning mature business. One notable positive is balance-sheet leverage: debt to equity is low and net debt relative to assets is unusually conservative, suggesting the company has so far relied less on heavy borrowing than many utility peers. That provides some flexibility, but it does not offset the fact that the business is still consuming large amounts of cash.
The share price has also been volatile, with a sharp decline between May and August 2026. For long-term readers, that matters less as a short-term signal than as a reminder that the market is still trying to decide how much future success to credit today.
Growth
Fervo operates in a part of the energy market with real structural tailwinds. Demand for clean electricity is rising, grid reliability has become more valuable, and policymakers and large electricity buyers increasingly want power sources that are both low-carbon and available around the clock. That last point is especially important. Unlike solar and wind, geothermal can provide continuous generation, making it attractive in a power system that needs dependable clean supply.
Fervo’s strategy is built around that gap in the market. If the company can prove that enhanced geothermal systems can be developed repeatedly and at competitive cost, it could address a much larger resource base than conventional geothermal. This is the central growth argument: not just building a few projects, but expanding geothermal from a niche technology into a broader clean power platform.
Recent company announcements and public updates have reinforced that opportunity. Fervo has highlighted progress on project development in Utah through Cape Station, which is intended to become one of the largest enhanced geothermal developments in the world. The company has also emphasized power offtake arrangements and financing milestones in recent years, both of which are critical because they help translate technical success into commercial credibility. In addition, public support for firm clean power in the United States, including Department of Energy interest in advanced geothermal, improves the backdrop for permitting, financing, and customer demand.
That said, the reported revenue trend still shows that growth has not yet reached the income statement in a meaningful way. Revenue per share remains close to zero and even moved lower in the latest annual comparison, which underlines the gap between project promise and commercial scale. In other words, the industry opportunity looks strong, but company-level financial growth still depends on projects moving from development to operation.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


