Stock Analysis · First Quantum Minerals Ltd (FQVLF)
Overview
First Quantum Minerals Ltd is a large copper mining company that develops, operates, and expands mineral assets in several countries. Copper is the core of the business, but the company also produces meaningful volumes of gold and nickel, plus smaller amounts of zinc, silver, acid, and other by-products depending on the mine. Its portfolio has historically included major operations in Zambia, Turkey, Mauritania, Finland, Australia, and, until the shutdown dispute, Panama.
For long-term analysis, the most important point is that First Quantum is not a diversified mining conglomerate with many equally sized profit centers. It is primarily a copper producer whose results are heavily shaped by a limited number of large assets. That concentration can create strong upside when mines perform well and copper prices are favorable, but it also makes setbacks at one major operation especially important for the whole company.
Based on the company’s recent annual reporting, revenue is led by copper by a wide margin, with gold clearly second and the rest much smaller. A practical breakdown is:
- Copper: approximately 80% to 85% of revenue. This comes from copper concentrate, copper anode, and copper cathode sold from the group’s major mines and processing facilities.
- Gold: approximately 10% to 15% of revenue. Gold is mainly produced alongside copper at some operations and helps offset mining costs.
- Nickel: approximately 3% to 7% of revenue. This is mainly tied to the Ravensthorpe operation in Australia.
- Other products: generally below 5% combined. This can include zinc, silver, sulfuric acid, and other by-products depending on the year and asset mix.
The recent financial flow also shows a business that still generates solid gross profit and operating income, but where interest expense and taxes have absorbed a large share of earnings. That helps explain why accounting profit has remained weak even as operating performance improved from the 2023 low.
Over the last several years, revenue fell sharply after the Panama disruption, while operating income recovered better than net income. In simple terms, the mines still have earning power, but debt costs and the loss of a major asset have made it harder for that operating strength to turn into bottom-line profit.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Copper | |
| Market Cap ⓘ | $21.46B | |
| Beta ⓘ | 2.06 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 16.92 |
| P/B Ratio ⓘ | 1.95 | 1.66 |
| FCF Yield ⓘ | 0.31% | 5.83% |
| Dividend Yield ⓘ | N/A | 2.07% |
| EBIT / EV ⓘ | 3.42% | 6.38% |
| PEG ⓘ | 3.83 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 24.10% | 11.25% |
| RPS Growth (5Y CAGR) ⓘ | -11.48% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -15.24% |
| BVPS Growth (5Y CAGR) ⓘ | -2.72% | 5.49% |
| Margin Growth (5Y Trend) ⓘ | -15.35% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | -29.65% | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 5.91% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 9.59% |
| ROA (Latest) ⓘ | -0.33% | 4.92% |
| ROIC (5Y Median) ⓘ | 0.67% | 7.91% |
| ROA (5Y Median) ⓘ | 0.01% | 3.92% |
| Net Debt / EBIT (Latest) ⓘ | 4.79 | 1.36 |
| Net Debt / EBIT (5Y Median) ⓘ | 4.87 | 1.69 |
| Net Debt / EBITDA (Latest) ⓘ | 2.79 | 0.93 |
| Net Debt / Assets ⓘ | 21.57% | 13.69% |
| EBITDA / Interest ⓘ | 3.16 | 12.38 |
| Operating Margin (Latest) ⓘ | 19.71% | 13.24% |
| Operating Margin (5Y Median) ⓘ | 20.02% | 11.82% |
| Debt to Equity (Latest) ⓘ | 54.66% | 40.30% |
| Profit Margin (Latest) ⓘ | -1.44% | 6.38% |
| Free Cash Flow (Latest) ⓘ | $67.41M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +17.66% | +73.47% |
| 12M Return (excl. last month) ⓘ | +64.20% | +27.59% |
| 6M Return ⓘ | -3.76% | -4.02% |
| Price vs. 200-Day MA ⓘ | -8.21% | -0.65% |
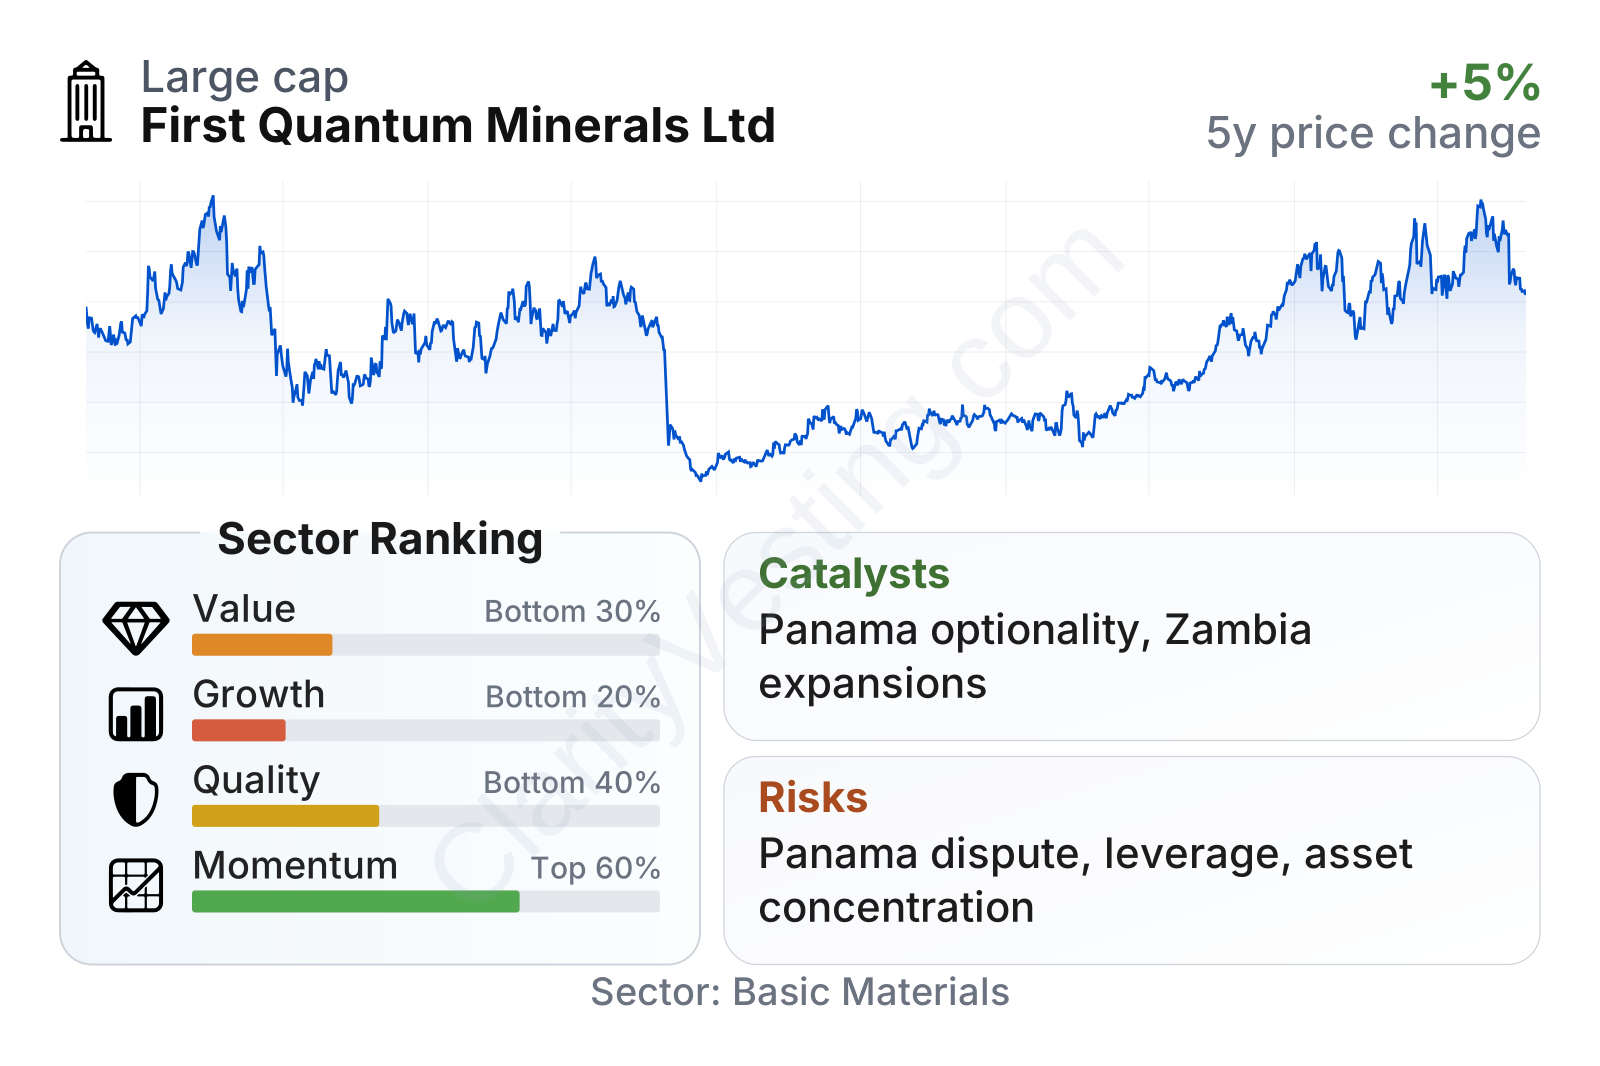
First Quantum is a large mining company with a stock that has been highly volatile, which fits its high beta of roughly 2.0. The market has rewarded the recent operational rebound, and price momentum has been much stronger than the sector over the last 6 to 12 months. At the same time, the broader profile remains mixed: growth rankings are weak on a multi-year view, quality sits below the sector median, and value metrics do not screen as especially cheap compared with other materials companies. In short, the market appears to be pricing in recovery, but the underlying balance sheet and profitability still lag stronger peers.
Growth
First Quantum operates in a sector with favorable long-term demand drivers. Copper is essential for power grids, electric vehicles, renewable energy systems, data centers, and general electrification. Industry supply growth is also difficult because new mines take many years to permit, finance, and build. That combination gives established producers with long-life assets an important strategic position.
The company’s strategy broadly matches that backdrop. It has focused on large-scale copper assets, expansion projects, and processing improvements rather than small, scattered operations. The strongest part of the growth case is not complexity but scale: if a few large sites perform well and one stalled asset eventually returns, production and cash generation can move meaningfully.
Recent revenue growth has turned positive again after a period of severe contraction. That matters because it suggests the business has moved out of its deepest disruption phase. Even so, the longer-term record is still uneven, so the recent rebound should be read as recovery from a damaged base rather than proof of smooth compounding.
Cash generation has also improved sharply from the very weak levels seen around 2024 and 2025. That is one of the most constructive developments in the current picture. Mining companies ultimately need operating cash to fund sustaining capital, debt service, and expansion. A return to positive free cash flow gives the company more flexibility, especially after a period when financial breathing room looked tight.
The biggest catalyst remains the suspended Cobre Panamá mine. Before operations stopped, it was one of the company’s most important assets and one of the world’s larger copper mines. Any durable legal or political resolution that allows a restart, asset preservation agreement, or compensation framework would be highly significant. A second catalyst is continued operational improvement in Zambia, where the Kansanshi S3 expansion and the Enterprise nickel project have been central parts of the company’s production plan. Stronger copper prices would amplify both of those company-specific developments.
Recent company updates have continued to emphasize preserving optionality around Panama while advancing the Zambian growth pipeline. That combination creates a two-part growth setup: internal improvement from the current asset base, plus the possibility of a much larger step-change if Panama returns in some form.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


