Stock Analysis · 5N Plus Inc (FPLSF)
Overview
5N Plus Inc is a Canadian specialty materials company that refines and manufactures high-purity metals, compounds, and engineered materials used in markets where performance matters more than volume. Its products are found in terrestrial renewable energy, space-based solar power, medical imaging, semiconductor applications, security, and industrial technologies. In simple terms, 5N Plus sits in a niche part of the supply chain: it does not sell finished consumer products, but rather the critical materials that allow other companies to build them.
The business is organized around two main segments. Based on the latest annual reporting, revenue is primarily generated from:
- Specialty Semiconductors: approximately 70% to 80% of revenue. This segment includes semiconductor and compound materials used in thin-film solar, space solar cells, infrared technologies, security applications, and certain electronic uses.
- Performance Materials: approximately 20% to 30% of revenue. This segment includes bismuth, tellurium, cadmium, selenium, and related products used in healthcare, pharmaceuticals, industrial chemicals, and other specialty applications.
The revenue mix matters because the higher-growth part of the company is tied to advanced technology and energy-related applications rather than bulk commodity chemicals. Over the last few years, the business has also shown a meaningful improvement in converting sales into operating profit, which suggests the mix is becoming more favorable.
The financial flow over the last five years points to a clear turnaround. Revenue has risen from about $210 million in 2021 to nearly $400 million in 2025, while operating income moved from modest profitability, to a loss in 2022, and then to a much stronger level by 2025. Gross profit expanded faster than sales, which usually signals better pricing, improved product mix, or more efficient operations.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Specialty Chemicals | |
| Market Cap ⓘ | $1.94B | |
| Beta ⓘ | 1.66 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 31.29 | 16.90 |
| P/B Ratio ⓘ | 8.05 | 1.65 |
| FCF Yield ⓘ | -0.24% | 5.76% |
| Dividend Yield ⓘ | N/A | 2.13% |
| EBIT / EV ⓘ | 4.74% | 6.30% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 28.40% | 11.10% |
| RPS Growth (5Y CAGR) ⓘ | 14.90% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -13.47% |
| BVPS Growth (5Y CAGR) ⓘ | 7.60% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | 13.37% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | 82.39% | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.08% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 9.26% |
| ROA (Latest) ⓘ | 12.81% | 4.91% |
| ROIC (5Y Median) ⓘ | 8.18% | 7.70% |
| ROA (5Y Median) ⓘ | 4.04% | 3.86% |
| Net Debt / EBIT (Latest) ⓘ | 0.57 | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | 3.88 | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | 0.47 | 0.95 |
| Net Debt / Assets ⓘ | 10.13% | 13.69% |
| EBITDA / Interest ⓘ | 12.73 | 12.34 |
| Operating Margin (Latest) ⓘ | 20.76% | 13.20% |
| Operating Margin (5Y Median) ⓘ | 11.23% | 11.80% |
| Debt to Equity (Latest) ⓘ | 45.47% | 40.56% |
| Profit Margin (Latest) ⓘ | 14.14% | 6.43% |
| Free Cash Flow (Latest) ⓘ | -$4.73M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +820.61% | +68.89% |
| 12M Return (excl. last month) ⓘ | +66.98% | +30.21% |
| 6M Return ⓘ | -16.81% | -4.16% |
| Price vs. 200-Day MA ⓘ | -7.52% | -1.27% |
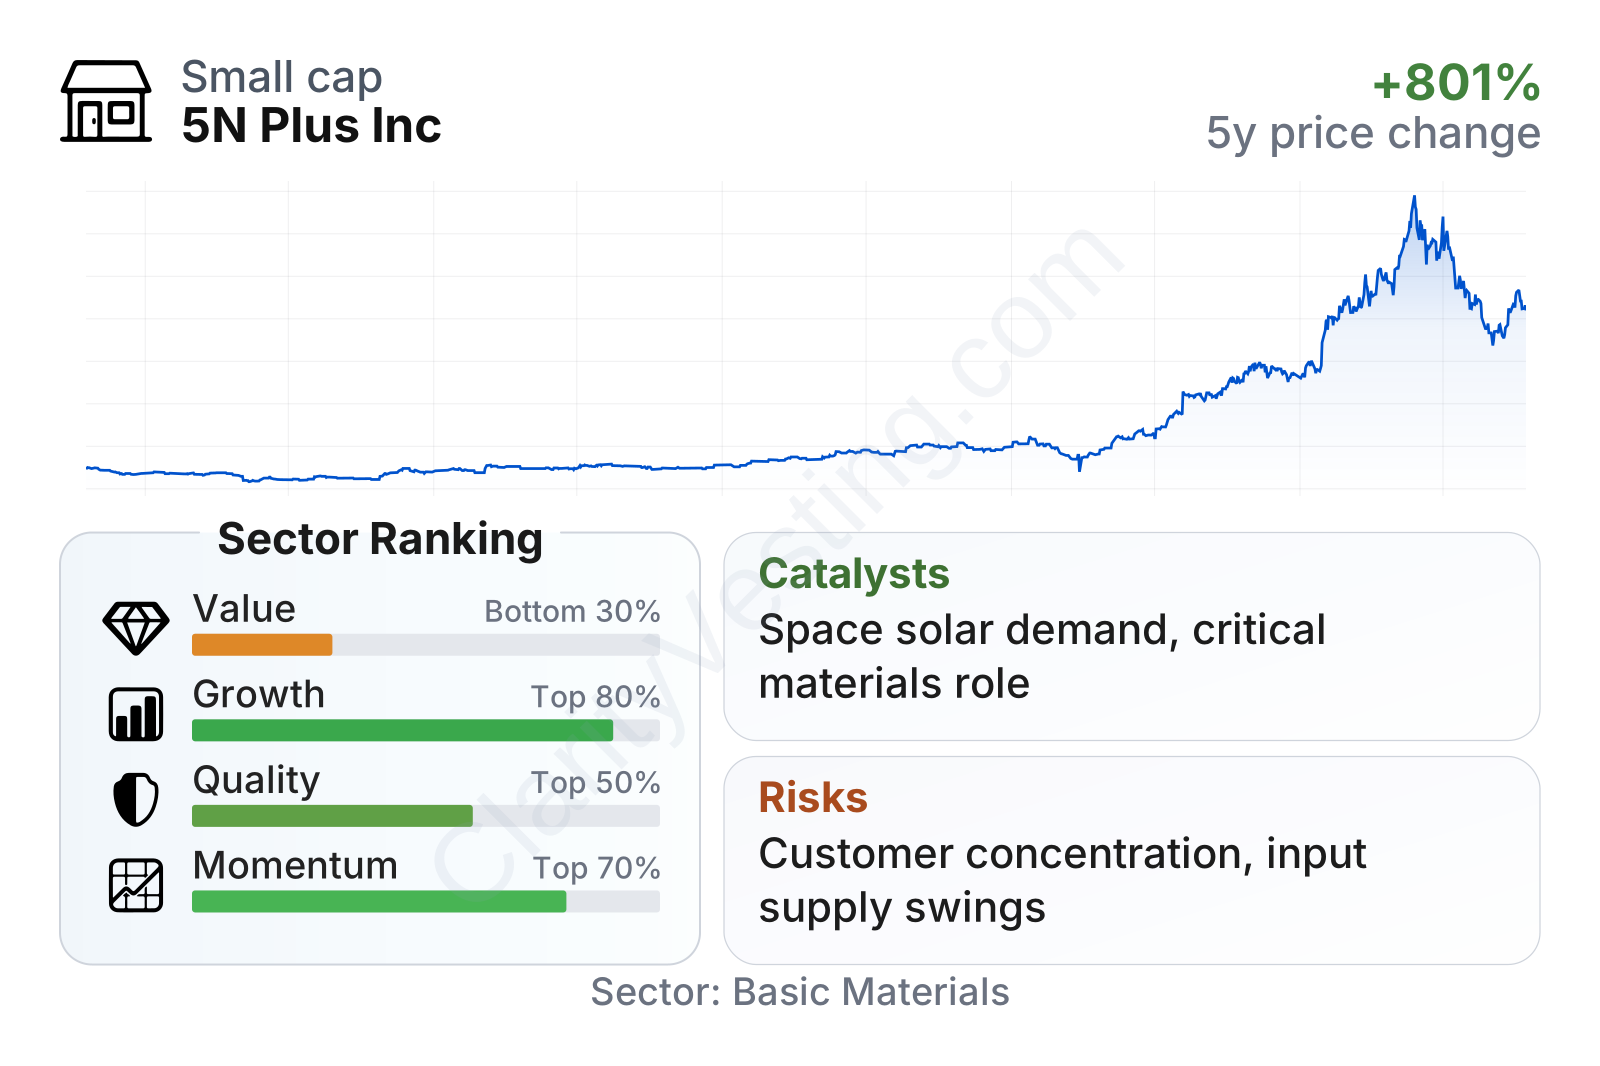
5N Plus is now a mid-sized company by market value, but its stock still behaves more like a smaller, more volatile name, as shown by its elevated beta. The company ranks well on growth and sits around the middle of the pack on quality, supported by solid profitability and much better balance-sheet leverage than in earlier years. The weaker point is valuation: multiples are above sector norms, while free cash flow remains uneven, which makes the current pricing more demanding than the operating profile alone might suggest.
The stock chart highlights how dramatic the re-rating has been. After trading near $1 to $3 during 2022 and 2023, the shares moved sharply higher through 2024 and especially 2025 into 2026. That kind of rise usually means the market is already recognizing better fundamentals and future expectations, so long-term analysis has to focus less on whether the company has improved and more on how much of that improvement is already reflected in the price.
Growth
5N Plus operates in several areas with attractive long-term demand drivers. The strongest themes are solar energy, space infrastructure, semiconductor materials, and specialized healthcare applications. These are not short-lived trends. Space solar and advanced semiconductor materials benefit from growing satellite deployment, defense-related demand, and the broader need for high-performance electronics. At the same time, the company’s exposure to renewable energy materials adds another structural tailwind.
The strategy appears coherent. Rather than competing in large-scale, low-margin commodity markets, 5N Plus focuses on niche products where purification know-how, customer qualification, and reliability create higher barriers to entry. That approach can support better margins and more stable customer relationships over time, especially in regulated or mission-critical applications.
Revenue growth has not been perfectly smooth, but the broader pattern is favorable. After a softer period in 2023, growth re-accelerated through 2024 and remained strong into 2025 and the first half of 2026, with recent year-over-year expansion still running well above the sector median. The five-year revenue-per-share growth rate also stands comfortably ahead of many peers, reinforcing the idea that this is more than a one-quarter improvement.
Cash generation has been less linear than revenue growth. Free cash flow moved between negative and positive territory as the company invested in working capital and expansion, then turned strongly positive by early 2026 before slipping back to slightly negative on a trailing basis in the latest snapshot. For a growth-oriented materials company, that pattern is not unusual, but it does mean investors need to watch whether higher profits consistently translate into cash over a full cycle.
A meaningful catalyst is the company’s positioning in strategic materials outside China-centered supply chains. Governments and industrial customers in North America and Europe increasingly want resilient sourcing for critical materials used in energy, aerospace, and electronics. 5N Plus has been highlighting that role in public communications, and this positioning could support new contracts, stronger pricing, and closer ties with large industrial and governmental customers.
Another important catalyst is the company’s exposure to space solar cell materials. This is a small market in volume but a high-value one, and qualification requirements can make supplier relationships durable. Recent company updates have continued to emphasize demand visibility in this area, which helps explain why the market has become more optimistic about the earnings outlook.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


