Stock Analysis · First Pacific Company Ltd (FPAFY)
Overview
First Pacific Company Ltd is a Hong Kong-based investment holding company that owns major operating businesses across Southeast Asia. For U.S. investors using the FPAFY ticker, it is not a single-brand food company in the usual sense. Instead, it is a diversified group with controlling or significant stakes in consumer foods, telecommunications, infrastructure, and healthcare assets, with the Philippines and Indonesia at the center of the portfolio.
The biggest earnings driver is Indofood, one of Indonesia’s largest food groups. First Pacific also has a major stake in PLDT, a leading telecom operator in the Philippines, as well as MPIC, which is active in toll roads, water, power, hospitals, rail, and logistics. In healthcare, the group has exposure through Philex and related healthcare investments, while Philex itself is better known as a mining company. This mix makes First Pacific closer to a regional conglomerate than a pure consumer staples business.
Based on the company’s latest annual reporting, contribution from operating companies to recurring profit was led by food and telecom, with infrastructure also meaningful. Approximate recurring-profit contribution was:
- Food (Indofood): about 39% — packaged foods, noodles, dairy, flour milling, edible oils, beverages, and agribusiness.
- Telecommunications (PLDT): about 34% — mobile, broadband, enterprise connectivity, and data services in the Philippines.
- Infrastructure (MPIC): about 24% — toll roads, water utilities, power, healthcare facilities, rail, and logistics.
- Mining and other contributions: about 3% — mainly exposure through Philex and smaller corporate items.
This structure matters for long-term analysis. The company is not dependent on one product cycle alone. Its underlying cash generation is spread across essential everyday demand: food consumption, internet access, transport links, utilities, and healthcare.
Over the last several years, the business mix has also shown improving profitability. Revenue has stayed around the same broad level, but gross profit, operating income, and net income have all trended upward, suggesting better margins and stronger earnings quality rather than growth coming only from size.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Consumer Defensive | |
| Industry | Packaged Foods | |
| Market Cap ⓘ | $2.69B | |
| Beta ⓘ | 0.78 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 4.70 | 17.88 |
| P/B Ratio ⓘ | N/A | 1.29 |
| FCF Yield ⓘ | 111.42% | 12.39% |
| Dividend Yield ⓘ | 5.47% | 2.85% |
| EBIT / EV ⓘ | 42.84% | 6.43% |
| PEG ⓘ | 0.11 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 5.70% | 4.10% |
| RPS Growth (5Y CAGR) ⓘ | 3.30% | 6.18% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -13.59% |
| BVPS Growth (5Y CAGR) ⓘ | N/A | 3.20% |
| Margin Growth (5Y Trend) ⓘ | 9.29% | -0.15% |
| FCF Growth (5Y CAGR) ⓘ | 82.49% | 4.10% |
| DPS Growth (5Y CAGR) ⓘ | 12.42% | 6.79% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 20.93% | 12.34% |
| ROA (Latest) ⓘ | 4.34% | 6.30% |
| ROIC (5Y Median) ⓘ | 10.69% | 10.49% |
| ROA (5Y Median) ⓘ | 1.90% | 5.44% |
| Net Debt / EBIT (Latest) ⓘ | 1.91 | 1.96 |
| Net Debt / EBIT (5Y Median) ⓘ | 4.48 | 2.35 |
| Net Debt / EBITDA (Latest) ⓘ | 1.59 | 1.38 |
| Net Debt / Assets ⓘ | 28.24% | 21.51% |
| EBITDA / Interest ⓘ | 3.96 | 9.46 |
| Operating Margin (Latest) ⓘ | 21.93% | 8.87% |
| Operating Margin (5Y Median) ⓘ | 21.68% | 9.53% |
| Debt to Equity (Latest) ⓘ | 294.46% | 72.35% |
| Profit Margin (Latest) ⓘ | 5.43% | 5.40% |
| Free Cash Flow (Latest) ⓘ | $2.99B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +90.98% | +20.92% |
| 12M Return (excl. last month) ⓘ | -21.08% | +2.13% |
| 6M Return ⓘ | -7.77% | +1.26% |
| Price vs. 200-Day MA ⓘ | -7.97% | +1.39% |
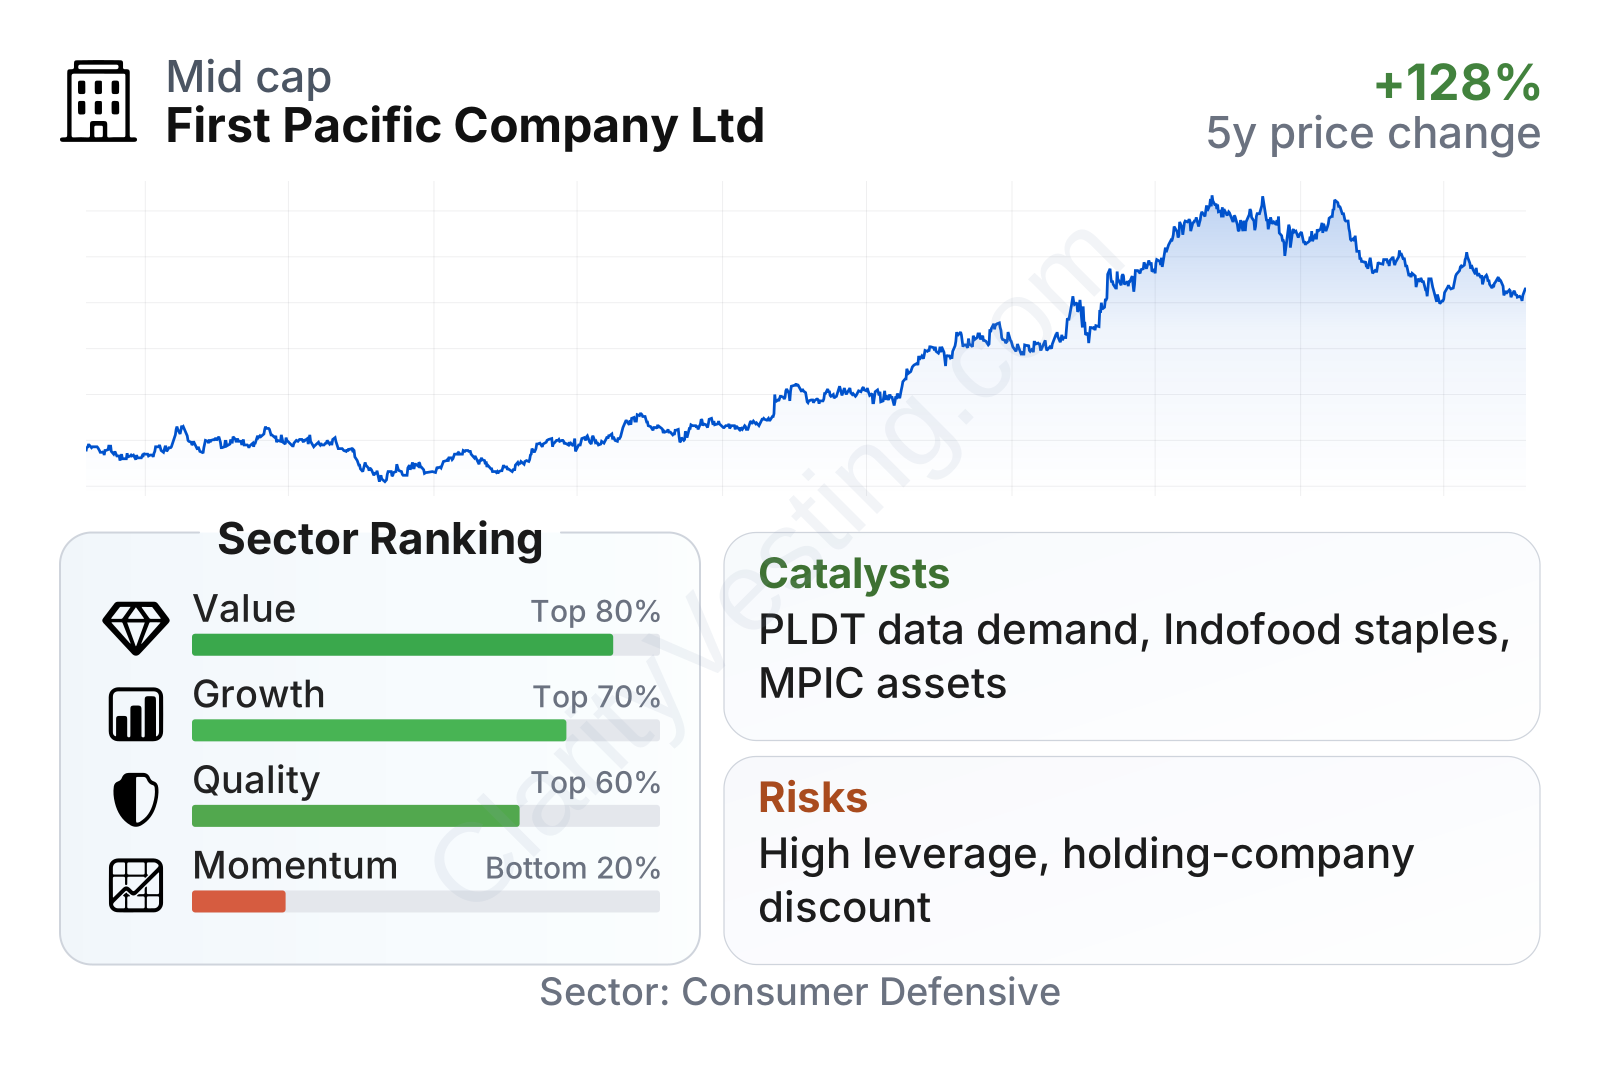
First Pacific is a mid-sized company by market value, and its share price has been much less volatile than the broader market, with a beta below 1. The stock had a very strong multi-year run through 2025, but shorter-term momentum has weakened in recent months. In the fundamentals table, the clearest message is that valuation looks unusually low compared with the sector, while profitability and cash generation appear strong. The weaker point is balance-sheet structure: debt-related ratios remain noticeably heavier than the typical consumer defensive company, even though some leverage measures have improved from older levels.
The company also stands out for cash generation and shareholder distributions. The dividend yield is above the sector median, and free cash flow metrics are exceptionally high. At the same time, the business is not screening as a fast structural grower on every measure. Recent year-over-year sales growth has been positive, but the longer five-year revenue-per-share trend is more moderate.
Growth
First Pacific operates in sectors that are generally supportive for long-term demand. Food consumption in Indonesia is backed by population scale and rising household spending over time. Telecom and broadband demand in the Philippines continues to benefit from data usage, digital services, and network dependence. Infrastructure and healthcare also tend to grow alongside urbanization, traffic demand, public service needs, and income growth. These are not speculative markets; they are tied to basic daily activity.
The group’s strategy also makes practical sense. Rather than chasing unrelated expansion, it has stayed focused on large essential-service platforms where scale matters. Indofood has broad reach across staple food categories. PLDT has an established market position in Philippine connectivity. MPIC is linked to long-duration infrastructure assets that can provide recurring cash flow. That combination can support resilience even when one division faces temporary pressure.
Growth has not been perfectly linear, but the recent direction has been constructive. Revenue growth has remained positive, and margin improvement has done much of the heavy lifting. Over five years, free cash flow growth has been especially strong, which is important for a holding company because cash supports debt service, dividends, and reinvestment.
A notable catalyst is the continued development of digital and infrastructure demand in the Philippines. PLDT’s network monetization, enterprise connectivity, and broadband base remain important areas to watch. Another is the long-run consumption outlook in Indonesia, where Indofood’s staple products are deeply embedded in everyday spending. In infrastructure, MPIC’s portfolio can benefit from tariff adjustments, traffic normalization, project expansion, and healthcare capacity growth.
Recent corporate moves also support a more focused portfolio. First Pacific has continued to emphasize value creation from core holdings rather than broad diversification for its own sake. That can help make capital allocation clearer and improve market understanding of the business mix over time.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


