Stock Analysis · Franco-Nevada Corporation (FNV)
Overview
Franco-Nevada Corporation is a royalty and streaming company focused mainly on gold, with additional exposure to other metals as well as oil and gas. That business model is very different from a traditional miner. Instead of operating mines itself, Franco-Nevada provides upfront capital to mining or energy companies and, in return, receives either a percentage of future production revenue or the right to buy part of production at a fixed low price. This usually gives it exposure to commodity prices and mine expansion without having to directly manage construction, labor, or day-to-day operating costs.
The company’s portfolio is broad, with hundreds of assets and a smaller group of core contributors. Its revenue is still led by precious metals, especially gold, which remains the central driver of results. Based on recent company disclosures, the main revenue sources can be summarized approximately as follows:
- Gold: about 70% to 80% of revenue. This includes royalties and streams tied to producing gold mines and development-stage projects.
- Other precious metals: about 5% to 10%. This mainly includes silver and platinum group metals linked to the same type of agreements.
- Base metals and iron ore: about 5% to 10%. These are royalties tied to assets producing materials such as copper, nickel, and iron ore.
- Oil and gas: about 10% to 15%. This comes from royalty interests in energy properties, giving the company some diversification outside mining.
One important point for long-term readers is that Franco-Nevada is not simply a bet on one mine or one operator. It is a portfolio business. That reduces single-asset risk compared with many mining companies, although a few large assets still matter a lot. The financial flow also shows why the model is attractive: operating costs stay low relative to revenue, so a large share of sales can turn into operating profit and cash flow. There was a notable earnings disruption in 2023 because of non-cash impairments, but by 2025 revenue and earnings had rebounded strongly.
The company’s cost structure remains unusually light for the sector. Revenue dipped from roughly $1.3 billion in 2021-2022 to a little above $1.1 billion in 2024, then climbed sharply to about $1.8 billion in 2025, while operating expenses stayed relatively small. That gap between revenue and overhead is a defining feature of the business model.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Gold | |
| Market Cap ⓘ | $47.03B | |
| Beta ⓘ | 0.94 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 32.13 | 16.90 |
| P/B Ratio ⓘ | 5.51 | 1.65 |
| FCF Yield ⓘ | 1.90% | 5.76% |
| Dividend Yield ⓘ | 0.67% | 2.13% |
| EBIT / EV ⓘ | 3.82% | 6.30% |
| PEG ⓘ | 11.81 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 58.20% | 11.10% |
| RPS Growth (5Y CAGR) ⓘ | 8.61% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | 4.13% | -13.47% |
| BVPS Growth (5Y CAGR) ⓘ | 5.84% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | 11.69% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | 66.24% | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | 11.03% | 6.08% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 19.08% | 9.26% |
| ROA (Latest) ⓘ | 17.99% | 4.91% |
| ROIC (5Y Median) ⓘ | 12.58% | 7.70% |
| ROA (5Y Median) ⓘ | 10.92% | 3.86% |
| Net Debt / EBIT (Latest) ⓘ | -0.54 | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | -1.03 | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | -0.46 | 0.95 |
| Net Debt / Assets ⓘ | -11.37% | 13.69% |
| EBITDA / Interest ⓘ | 720.30 | 12.34 |
| Operating Margin (Latest) ⓘ | 81.36% | 13.20% |
| Operating Margin (5Y Median) ⓘ | 66.01% | 11.80% |
| Debt to Equity (Latest) ⓘ | N/A | 40.56% |
| Profit Margin (Latest) ⓘ | 64.23% | 6.43% |
| Free Cash Flow (Latest) ⓘ | $891.40M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +74.27% | +68.89% |
| 12M Return (excl. last month) ⓘ | +31.53% | +30.21% |
| 6M Return ⓘ | -8.30% | -4.16% |
| Price vs. 200-Day MA ⓘ | -1.35% | -1.27% |
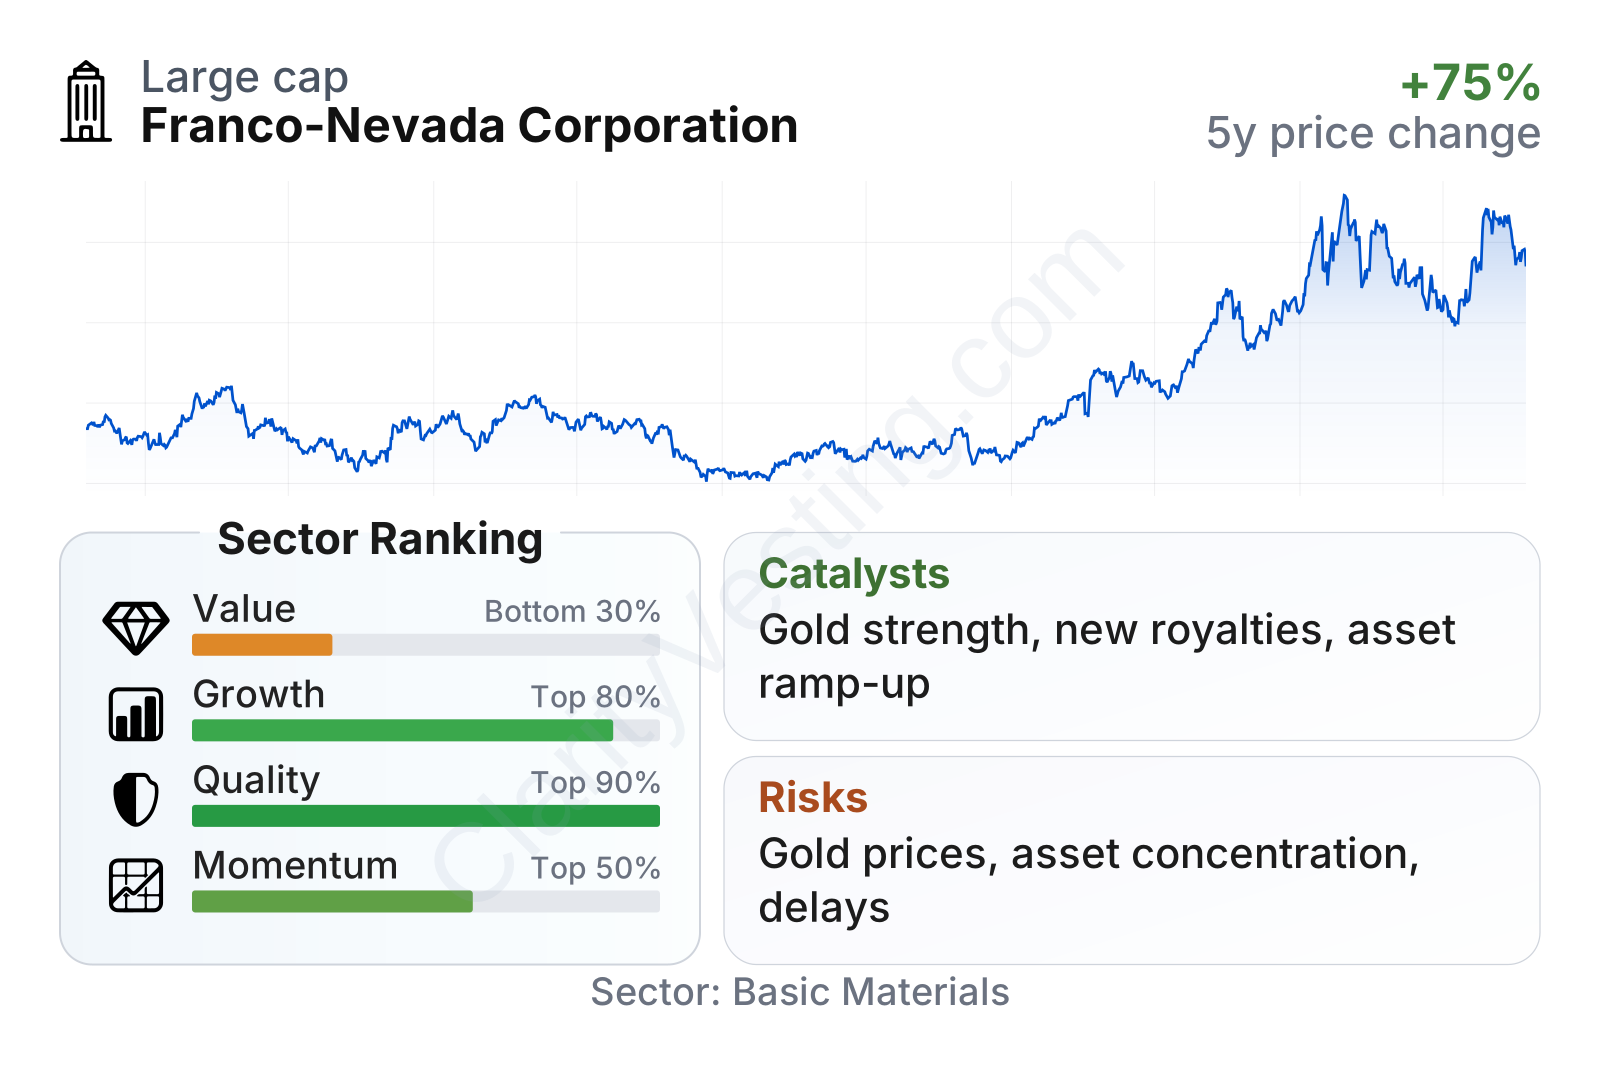
Franco-Nevada is a very large company within the gold space, with share-price volatility close to the broader market rather than the extreme swings often seen in miners. The overall profile shown in the metrics is clear: quality is exceptionally strong, growth is above most peers, while valuation looks demanding. Profitability, returns on capital, and balance-sheet strength all stand far above the sector median. By contrast, common valuation ratios such as P/E and price-to-book sit well above sector norms, which means the market is already assigning a premium to the business model.
Growth
Franco-Nevada operates in a sector that still has long-term relevance. Gold remains important as a store of value, central-bank reserve asset, and portfolio hedge during inflation or geopolitical stress. At the same time, mining finance remains structurally attractive for royalty companies because many miners prefer funding sources that do not require issuing more equity or taking on too much debt. That creates recurring opportunities for well-capitalized groups like Franco-Nevada to sign new deals.
The company’s strategy also makes sense for future expansion. It can grow in three ways without having to build mines itself: by acquiring new royalties and streams, by benefiting when existing mines expand production, and by gaining from higher commodity prices. This is one of the strongest aspects of the model because future upside can come from exploration success and mine-life extensions funded by operators rather than by Franco-Nevada.
Recent growth has accelerated sharply. After a weaker period in 2023 and much of 2024, year-over-year revenue turned strongly positive and moved into very high growth territory through 2025 and into 2026. That rebound suggests the business is benefiting from a combination of improved asset contributions and stronger commodity conditions, especially in gold.
Cash generation has also stepped up materially. Free cash flow was much lower and more uneven a few years ago, but the latest trailing period shows a major increase to above $3 billion. For a royalty company, that matters because cash flow is what finances new deals, supports dividends, and protects the balance sheet during weaker commodity periods.
A key catalyst in recent years has been the gradual normalization of contributions from important assets and the rising value of gold. Another notable opportunity is the long pipeline embedded in the portfolio: if more development-stage projects move into production, Franco-Nevada can add revenue without a similar rise in overhead. In simple terms, the company already owns claims on future output that could become more valuable over time.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


