Stock Analysis · Fresnillo PLC (FNLPF)
Overview
Fresnillo plc is a Mexico-focused precious metals miner best known for silver and gold production. The company operates several underground and open-pit mines, and it also develops new mining projects intended to replace depleted reserves and extend production over time. Its business is relatively easy to understand: it extracts ore, processes it, and sells the contained metals into global commodity markets. Revenue therefore depends mainly on how much metal it produces and the prices it can obtain for silver, gold, zinc, and lead.
Based on the company’s recent annual reporting, Fresnillo’s revenue mix is led by precious metals, with silver and gold clearly dominating total sales, while base metals provide a smaller but still useful contribution.
- Gold: approximately 50% to 55% of revenue. This reflects doré bars and concentrates produced mainly from mines with stronger gold exposure.
- Silver: approximately 35% to 40% of revenue. This includes silver contained in doré and concentrates and remains the company’s defining product category.
- Zinc: approximately 5% to 7% of revenue. Zinc is mainly a by-product from polymetallic deposits.
- Lead: approximately 3% to 5% of revenue. Lead also comes largely from polymetallic operations.
This mix matters for long-term analysis because Fresnillo is not a diversified industrial company with many unrelated income streams. It is primarily an operating bet on precious metals, especially silver, with gold adding balance and by-products helping unit economics. The financial flow over the last several years also shows how strongly profits can expand when metal prices and mine performance improve at the same time: revenue rose materially in 2024 and again in 2025, while operating income improved even faster.
The company’s recent financial progression suggests meaningful operating leverage. Costs did not rise at the same pace as revenue, which allowed gross profit and operating income to recover sharply after a weaker period in 2022 and 2023. That is one of the central features of mining businesses: when execution and commodity prices line up, earnings can move much faster than sales.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Other Precious Metals & Mining | |
| Market Cap ⓘ | $26.53B | |
| Beta ⓘ | 0.74 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 11.50 | 16.90 |
| P/B Ratio ⓘ | 4.91 | 1.65 |
| FCF Yield ⓘ | 14.52% | 5.76% |
| Dividend Yield ⓘ | 4.16% | 2.13% |
| EBIT / EV ⓘ | 17.55% | 6.30% |
| PEG ⓘ | 1.56 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 74.70% | 11.10% |
| RPS Growth (5Y CAGR) ⓘ | 14.30% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | 2.55% | -13.47% |
| BVPS Growth (5Y CAGR) ⓘ | 3.79% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | 24.43% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | 59.99% | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | 28.47% | 6.08% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 9.26% |
| ROA (Latest) ⓘ | 40.85% | 4.91% |
| ROIC (5Y Median) ⓘ | 10.06% | 7.70% |
| ROA (5Y Median) ⓘ | 4.66% | 3.86% |
| Net Debt / EBIT (Latest) ⓘ | -0.35 | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | 0.06 | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | -0.29 | 0.95 |
| Net Debt / Assets ⓘ | -22.11% | 13.69% |
| EBITDA / Interest ⓘ | 63.37 | 12.34 |
| Operating Margin (Latest) ⓘ | 47.43% | 13.20% |
| Operating Margin (5Y Median) ⓘ | 20.96% | 11.80% |
| Debt to Equity (Latest) ⓘ | 16.67% | 40.56% |
| Profit Margin (Latest) ⓘ | 37.96% | 6.43% |
| Free Cash Flow (Latest) ⓘ | $3.85B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +475.12% | +68.89% |
| 12M Return (excl. last month) ⓘ | +37.66% | +30.21% |
| 6M Return ⓘ | -28.65% | -4.16% |
| Price vs. 200-Day MA ⓘ | -20.45% | -1.27% |
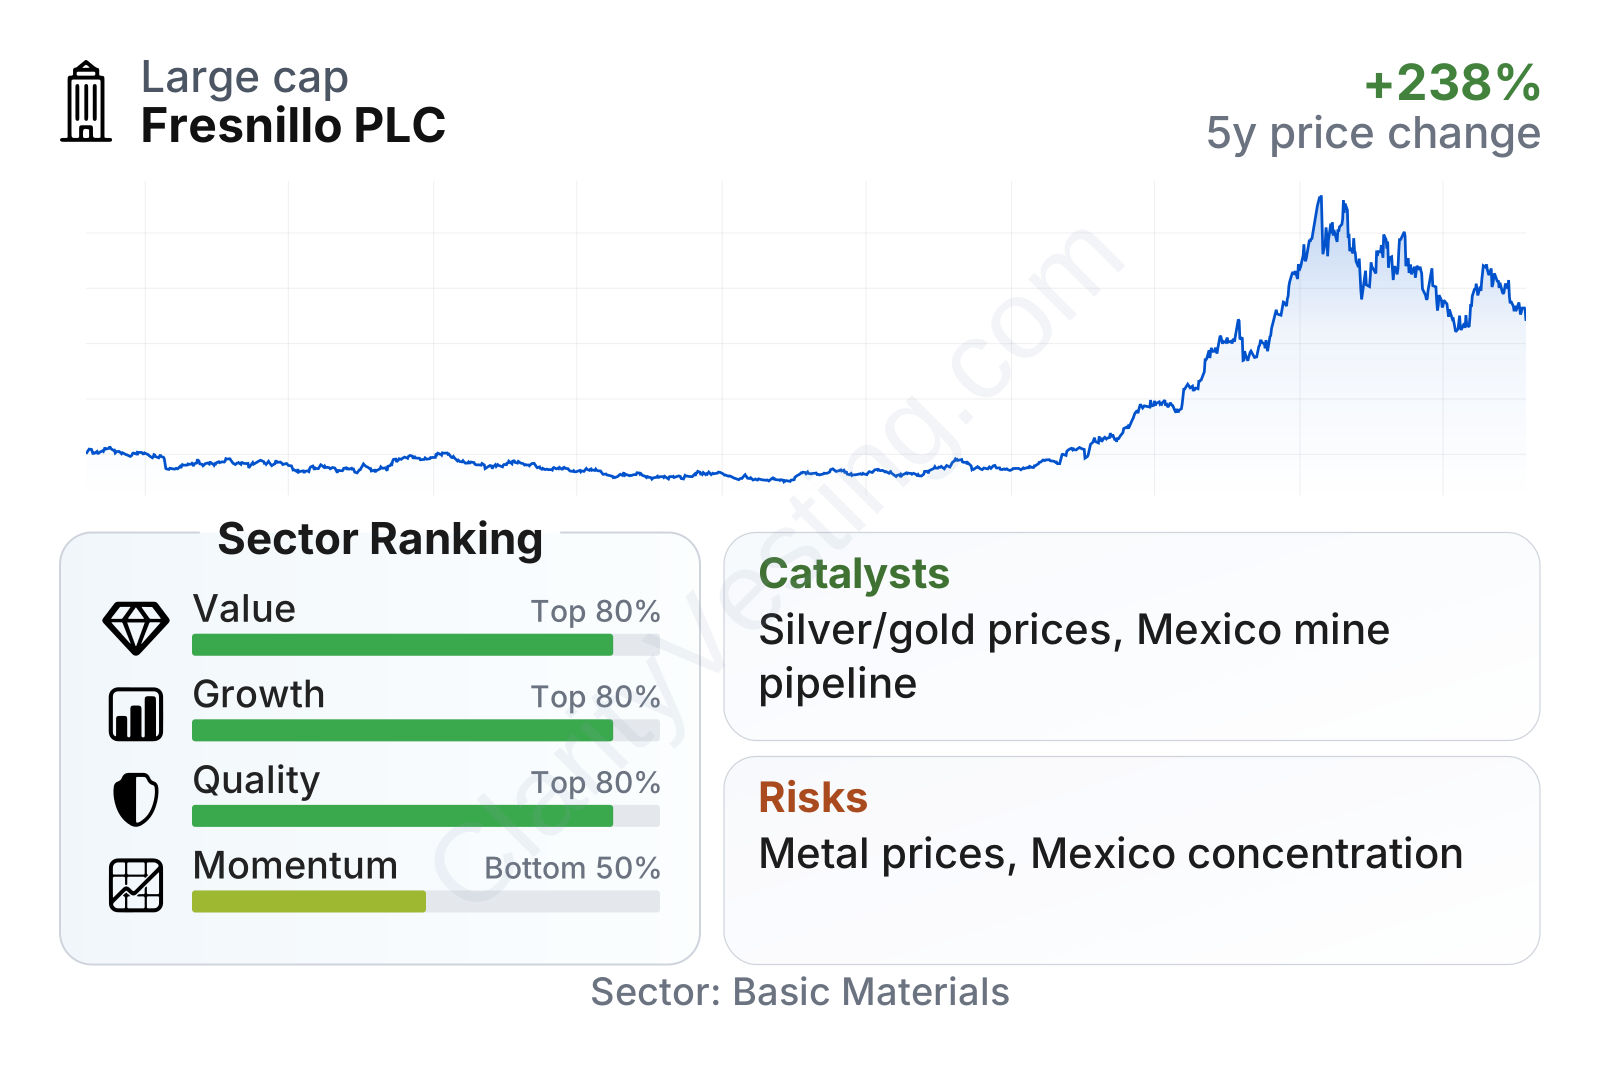
Fresnillo currently stands out as a large precious-metals miner with unusually strong profitability, low balance-sheet pressure, and fast recent growth relative to much of the materials sector. The table points to a mixed but interesting valuation profile: earnings-based multiples are below the sector median, free cash flow yield is high, and dividend yield is above the sector norm, while price-to-book is much richer than peers. That combination usually signals a business the market views as high quality but also highly exposed to favorable commodity conditions.
The quality metrics are particularly notable. Operating margin and profit margin are far above sector medians, leverage is low, and net debt metrics are better than many mining peers. Momentum is less straightforward: the stock had a very strong multi-year run, but more recent trading has cooled after a sharp rise, which is not unusual for a cyclical miner after a powerful move.
Growth
Fresnillo operates in a sector with credible long-term demand support, even though near-term results can be volatile. Silver has a dual role: it is both a precious metal and an industrial input used in electronics, solar panels, and other applications linked to electrification. Gold demand is supported by jewelry, investment demand, and central bank buying. That does not guarantee steady growth every year, but it does mean Fresnillo sits in a part of mining with both financial and industrial demand drivers.
The company’s strategy also makes sense for future growth. Fresnillo has long emphasized reserve replacement, mine development, exploration, and operational improvements across its Mexican asset base. For a miner, that is critical. Production growth without reserve renewal is not durable, and reserve renewal without disciplined execution does not create value. Fresnillo’s established operating footprint in Mexico gives it infrastructure, technical experience, and local knowledge that smaller entrants may struggle to replicate.
Recent revenue growth has been strong, with year-over-year expansion accelerating well above the broader sector. That improvement appears to reflect a better mix of production recovery and stronger realized prices, rather than simple cost inflation being passed through. Over a five-year view, revenue per share growth has also been solid, indicating that the latest rebound is not only a one-quarter event.
Cash generation is another important part of the growth picture. Free cash flow was uneven during the softer period, including a temporary dip into negative territory, but the broader profile has improved substantially. The latest trailing figures imply that the company is now converting favorable market conditions into real cash at a far better rate than many peers. For a capital-intensive business, that matters more than accounting profit alone because mine development, sustaining capital, and exploration all require ongoing funding.
A major catalyst is the combination of silver and gold price strength with Fresnillo’s operating leverage. When production normalizes and prices rise together, earnings can expand rapidly, as recent results suggest. Another catalyst is project execution: if the company advances development assets on time and keeps reserve life healthy, it can support production visibility beyond the current cycle. In addition, Mexico remains one of the world’s key silver-producing regions, so a well-established operator there can benefit disproportionately when the silver market tightens.
Recent company updates have also pointed to improving operating performance and stronger financial results, which reinforce the idea that Fresnillo is currently in a more favorable phase than it was in 2022 and 2023. For a cyclical miner, the distinction between weak and strong phases can be dramatic.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


