Stock Analysis · Filtronic plc (FLTCF)
Overview
Filtronic plc is a small U.K.-based communications equipment company focused on high-performance radio frequency, microwave, and millimeter-wave products. In simple terms, it makes specialized hardware that helps wireless networks and other advanced communications systems send signals more efficiently, especially at very high frequencies. Its products are used in areas such as telecom infrastructure, aerospace and defense, space, and critical communications applications where performance, size, and reliability matter more than low cost.
The business is centered on engineered components and subsystems rather than mass-market electronics. That makes Filtronic more of a specialist supplier than a broad equipment vendor. Its role is usually inside a larger customer system, such as a radio unit, backhaul link, satellite payload, or defense communication platform.
Based on the company’s recent annual reporting, revenue is mainly generated from product sales and engineering-related activity tied to a relatively small number of programs and customers. Public disclosures point to the following broad mix:
- Telecoms and communications infrastructure: approximately 60% to 75% of revenue. This includes E-band and other high-frequency modules, transceivers, filters, and power-related components used in backhaul, fronthaul, and advanced wireless systems.
- Aerospace, defense, and space: approximately 20% to 35% of revenue. This includes high-reliability radio frequency components and subsystems for defense electronics, electronic warfare, and satellite-related applications.
- Engineering services and other programs: a smaller share, generally below 10% where disclosed separately. This can include non-recurring development work, design support, and early-stage customer-funded projects.
One important point for long-term readers is that Filtronic’s sales mix can shift materially from year to year because contract timing is uneven and the company is not yet diversified across hundreds of end customers. The business has recently grown into a much larger revenue base than it had a few years ago, but it remains dependent on a limited number of meaningful programs.
The income flow over the last five fiscal years shows a clear step-up in scale: revenue rose sharply from 2024 to 2025, margins expanded strongly in that period, and 2026 held onto much of that larger base even though profitability eased from the prior year’s peak. That pattern suggests the company has moved beyond its earlier subscale phase, but also shows how earnings can swing when the mix of contracts changes.
The financial progression highlights a company that has become much larger in a short period. Revenue is still far above 2022-2024 levels, and gross profit remains healthy, but operating income and net income pulled back in 2026 after an unusually strong 2025. That points to a business with real operating leverage, but also with results that can move sharply depending on program timing and product mix.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Nov 21, 2026 | |
| Context | ||
| Sector | Technology | |
| Industry | Communication Equipment | |
| Market Cap ⓘ | $697.22M | |
| Beta ⓘ | 1.02 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 158.50 | 26.18 |
| FCF Yield ⓘ | 2.22% | 3.74% |
| Dividend Yield ⓘ | N/A | 1.32% |
| EBIT / EV ⓘ | N/A | 3.92% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | -1.50% | 17.95% |
| RPS Growth (5Y CAGR) ⓘ | 28.63% | 8.44% |
| EPS Growth (5Y CAGR) ⓘ | -58.96% | -6.06% |
| Margin Growth (5Y Trend) ⓘ | -5.08% | 0.56% |
| FCF Growth (5Y CAGR) ⓘ | -10.71% | 9.84% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 7.96% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 10.05% |
| ROIC (5Y Median) ⓘ | 15.87% | 8.19% |
| Net Debt / EBIT (Latest) ⓘ | -0.48 | 0.61 |
| Net Debt / EBIT (5Y Median) ⓘ | -1.16 | 0.48 |
| Net Debt / EBITDA (Latest) ⓘ | -0.40 | 0.33 |
| Net Debt / Assets ⓘ | -11.14% | 4.20% |
| EBITDA / Interest ⓘ | N/A | 13.53 |
| Operating Margin (Latest) ⓘ | 14.79% | 10.59% |
| Operating Margin (5Y Median) ⓘ | 12.23% | 8.53% |
| Debt to Equity (Latest) ⓘ | 13.80% | 34.34% |
| Profit Margin (Latest) ⓘ | 8.21% | 7.54% |
| Free Cash Flow (Latest) ⓘ | $15.50M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +1332.23% | +26.20% |
| 12M Return (excl. last month) ⓘ | +78.84% | +11.65% |
| 6M Return ⓘ | -50.00% | -4.21% |
| Price vs. 200-Day MA ⓘ | -16.81% | -4.34% |
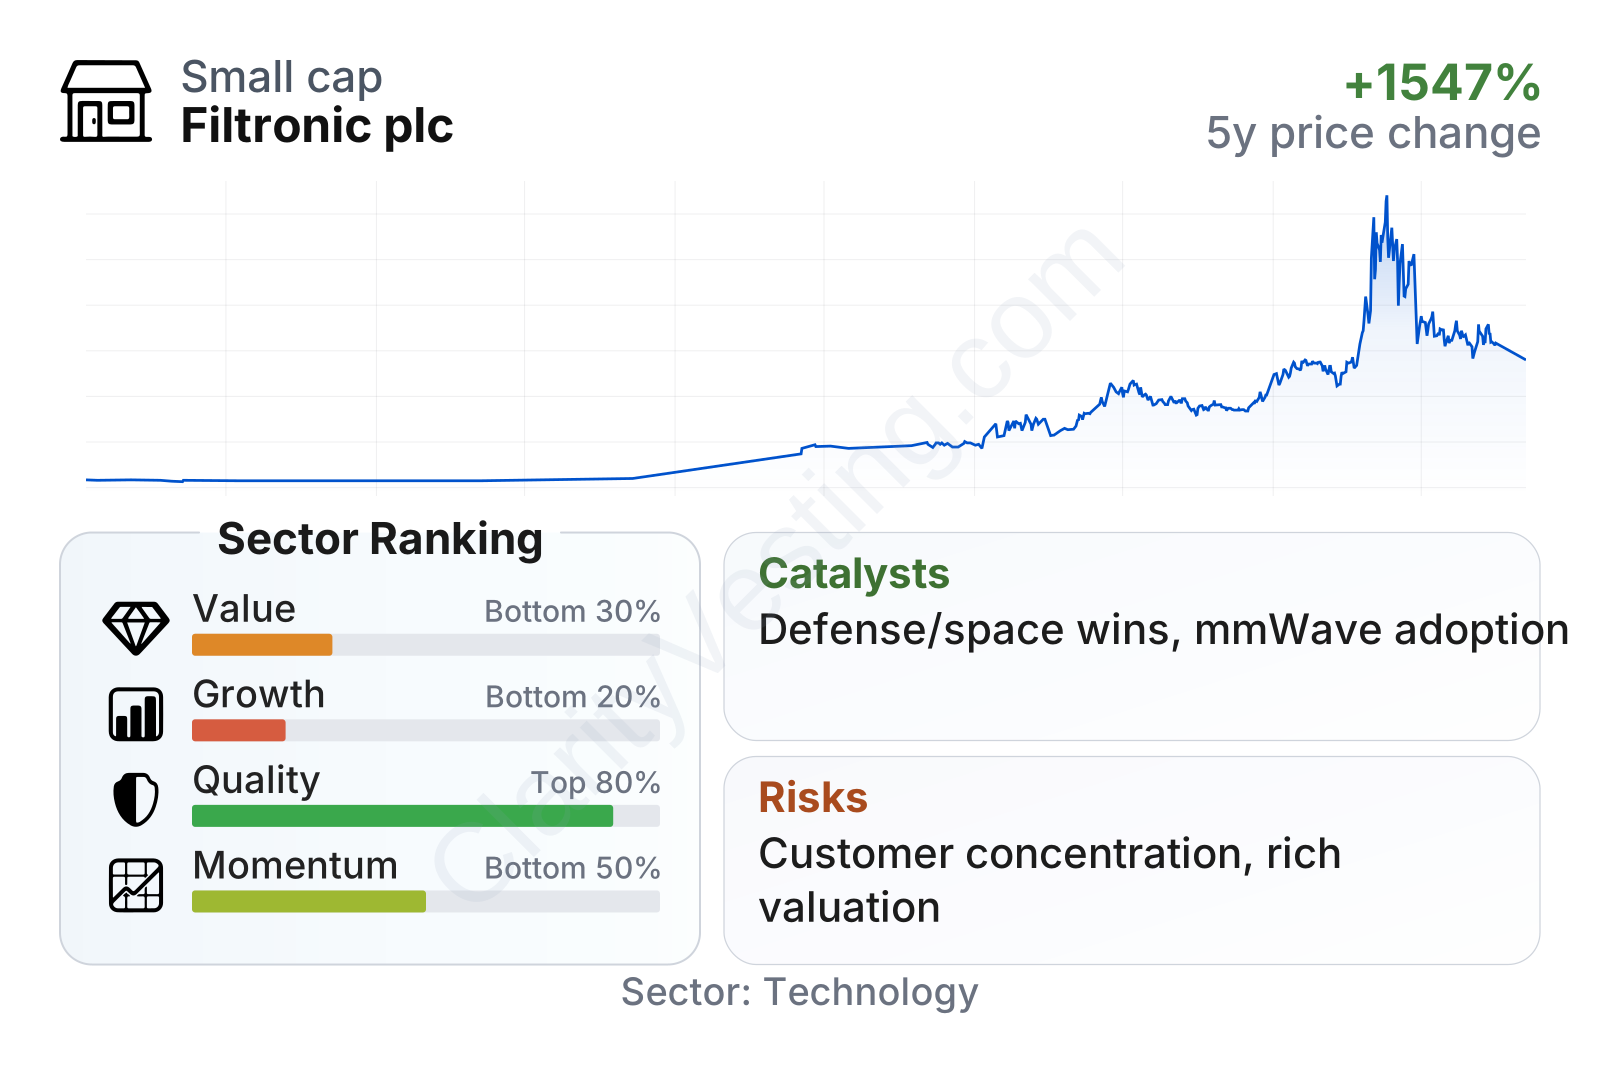
Filtronic is still a relatively small public company by market value, which often means more volatility and less room for operational mistakes. Share-price performance has been exceptionally strong over the last three years, far ahead of the broader technology sector median, although the stock has also been volatile, including a meaningful pullback after reaching a recent high in 2026.
On operating quality, the picture is better than the valuation multiples suggest at first glance. The company has been running with modest balance-sheet leverage, and current net debt metrics indicate a net cash position rather than financial strain. Operating margin and profit margin are also above typical sector medians, which is notable for a smaller communications hardware supplier. Free cash flow is positive as well.
The weaker area is consistency of growth in the most recent period. Year-over-year revenue was slightly down, and five-year trends for earnings, cash flow, and margin progression are less impressive than the sharp stock move might imply. In other words, Filtronic looks financially sound today, but not yet like a smooth compounder. The valuation metrics reflect that tension: profitability and balance-sheet quality are solid, while the earnings multiple is very elevated and cash flow yield is below the sector median.
Growth
Filtronic operates in parts of the communications equipment market that should remain relevant for years: high-frequency wireless links, advanced telecom architecture, satellite communications, and defense electronics. These are not commodity segments. They benefit from long-term demand for faster data transmission, denser networks, more capable radar and sensing systems, and higher-performance links for both terrestrial and space-based communications.
The strategic logic is straightforward. As wireless systems move to higher frequencies, the technical difficulty rises, and customers often prefer proven specialist suppliers rather than trying to develop every component internally. Filtronic’s focus on radio frequency and millimeter-wave engineering fits that need. This niche positioning gives the company a chance to participate in growth areas without competing head-on with the largest end-to-end telecom vendors.
A visible catalyst in recent years has been the company’s exposure to fast-growing high-frequency applications, particularly those tied to next-generation wireless infrastructure and space-related communications. Management has also emphasized defense and aerospace opportunities, which can provide longer product cycles and higher barriers to entry than standard telecom hardware. If Filtronic can turn development wins into repeat production programs, the business could keep a larger revenue base than it historically had.
Recent company updates have also pointed to continued customer engagement in advanced communications programs and to a stronger industry profile than the company had several years ago. The key opportunity is not just headline sector growth, but the possibility that Filtronic is moving from a small niche component vendor into a more established partner on higher-value programs. That would matter because it could improve revenue visibility and help smooth some of the past volatility.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


