Stock Analysis · Flowserve Corporation (FLS)
Overview
Flowserve Corporation is an industrial equipment company that makes products used to move, control, and protect the flow of liquids and gases. Its core offerings include pumps, valves, seals, automation systems, and related aftermarket services. These products are used in industries where reliability matters a great deal, such as oil and gas, chemicals, power generation, water management, mining, and general industrial processing.
The business is not built only on selling equipment once. A large part of its model comes from servicing installed equipment over many years. That matters because customers often operate critical facilities where downtime is expensive, so maintenance, repair, replacement parts, and upgrades can become recurring sources of business.
Based on recent company reporting, revenue is mainly organized this way:
- Flow Control segment: approximately 56% of revenue. This includes engineered valves, valve automation, actuation, controls, and related services used to regulate flow in industrial systems.
- Flowserve Pumps Division: approximately 44% of revenue. This includes engineered and industrial pumps, pump systems, mechanical seals, and associated aftermarket support.
Looking at revenue by customer mix rather than by product, aftermarket activity has been an important contributor and tends to carry better margins than original equipment. The business also has broad geographic exposure, which helps reduce dependence on one single country or end market, although energy-related industries remain highly important to overall demand.
Over the last several years, the company has expanded revenue from about $3.5 billion to roughly $4.7 billion, while profitability improved faster than sales. Gross profit and operating income have risen meaningfully, showing that recent execution has been about more than just volume growth.
The financial flow also shows a clear improvement in earnings quality since 2021: revenue has increased, but operating income and net income have risen even faster. That points to better pricing, mix, and operating discipline rather than growth driven purely by higher activity.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Specialty Industrial Machinery | |
| Market Cap ⓘ | $9.38B | |
| Beta ⓘ | 1.26 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 25.81 | 22.45 |
| P/B Ratio ⓘ | 4.28 | 1.98 |
| FCF Yield ⓘ | 4.39% | 6.31% |
| Dividend Yield ⓘ | 1.16% | 1.96% |
| EBIT / EV ⓘ | 5.57% | 4.81% |
| PEG ⓘ | 1.65 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | -1.60% | 9.10% |
| RPS Growth (5Y CAGR) ⓘ | 7.48% | 7.75% |
| EPS Growth (5Y CAGR) ⓘ | 14.32% | -13.59% |
| BVPS Growth (5Y CAGR) ⓘ | 4.68% | 6.22% |
| Margin Growth (5Y Trend) ⓘ | 7.35% | 0.72% |
| FCF Growth (5Y CAGR) ⓘ | 22.18% | 10.98% |
| DPS Growth (5Y CAGR) ⓘ | 1.16% | 9.48% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 9.58% | 10.92% |
| ROA (Latest) ⓘ | 6.11% | 5.41% |
| ROIC (5Y Median) ⓘ | 8.51% | 9.21% |
| ROA (5Y Median) ⓘ | 3.96% | 4.94% |
| Net Debt / EBIT (Latest) ⓘ | 2.50 | 2.07 |
| Net Debt / EBIT (5Y Median) ⓘ | 2.95 | 2.28 |
| Net Debt / EBITDA (Latest) ⓘ | 2.17 | 1.43 |
| Net Debt / Assets ⓘ | 25.11% | 19.27% |
| EBITDA / Interest ⓘ | 8.66 | 9.53 |
| Operating Margin (Latest) ⓘ | 13.70% | 10.50% |
| Operating Margin (5Y Median) ⓘ | 6.73% | 10.27% |
| Debt to Equity (Latest) ⓘ | 102.60% | 65.48% |
| Profit Margin (Latest) ⓘ | 8.01% | 6.62% |
| Free Cash Flow (Latest) ⓘ | $411.44M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +92.40% | +58.56% |
| 12M Return (excl. last month) ⓘ | +49.29% | +15.63% |
| 6M Return ⓘ | +0.05% | +4.19% |
| Price vs. 200-Day MA ⓘ | -3.64% | +0.93% |
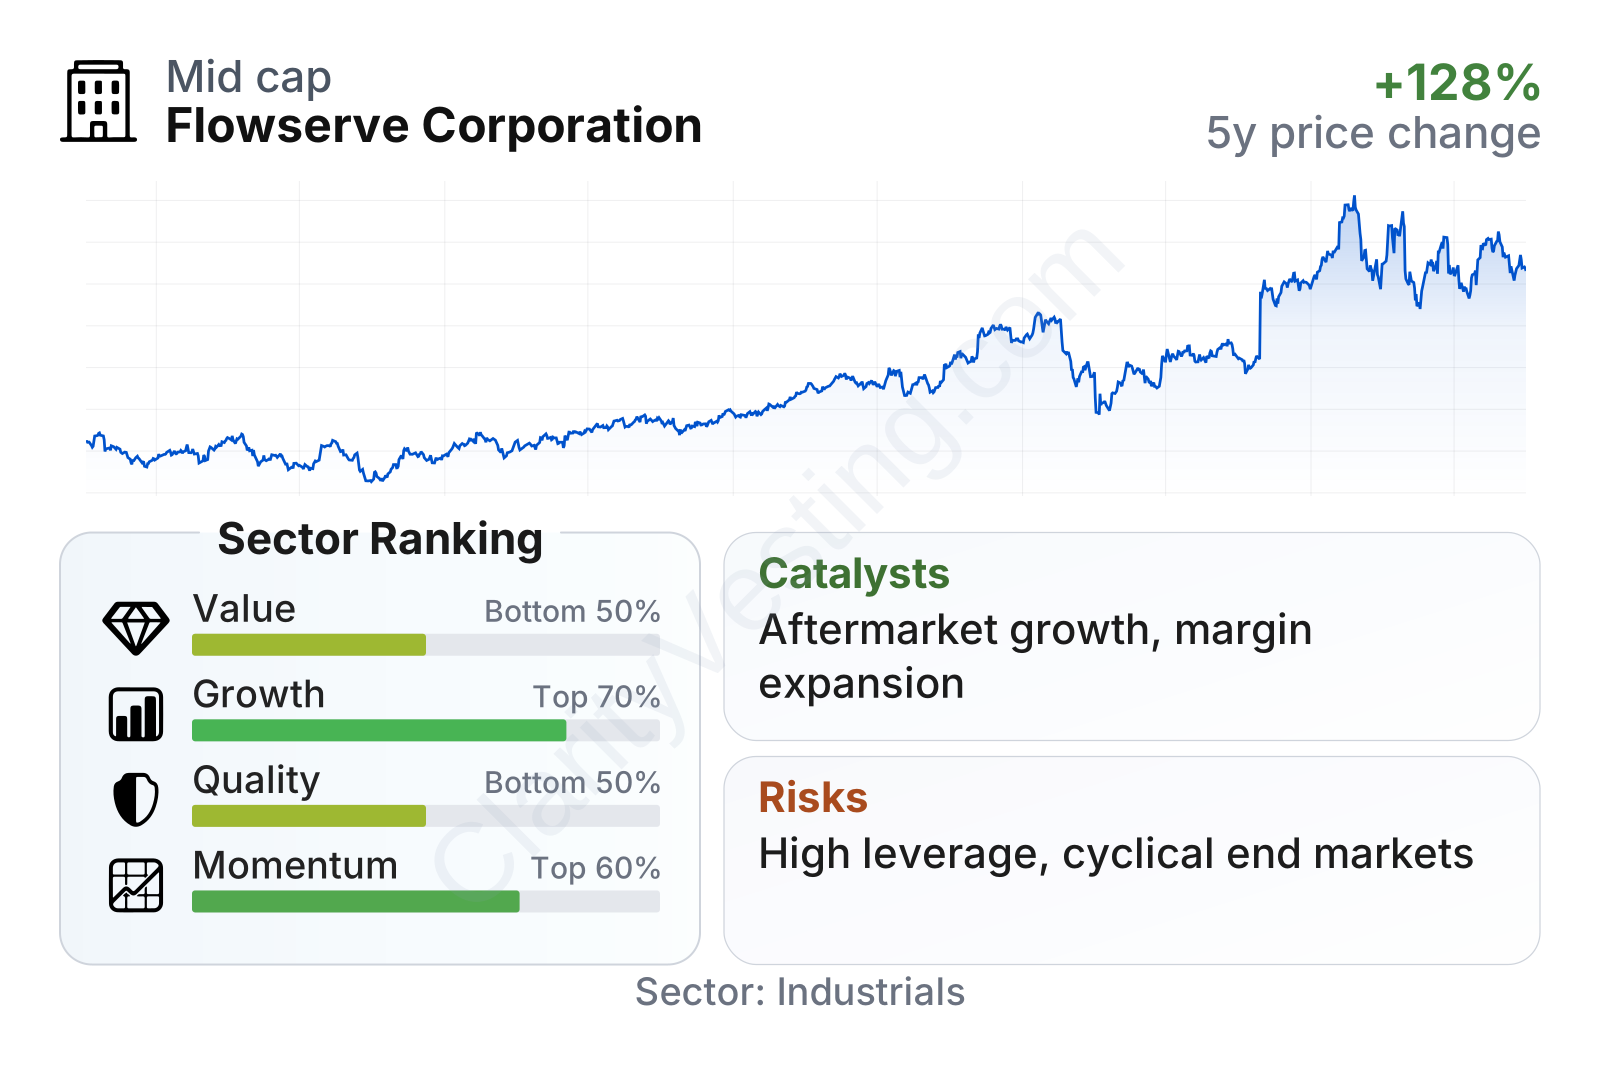
Flowserve is a mid-to-large industrial company with a market value around the high single-digit billions of dollars. Its recent profile looks mixed but improving. Growth and market momentum rank somewhat above the middle of its sector, while value and balance-sheet quality are less attractive. Profitability has strengthened noticeably, with operating margin around 14% and net margin near 8%, both better than earlier years. At the same time, leverage is higher than the sector median, and the stock’s valuation multiples are not especially low. Overall, the numbers describe a business that has been executing better, but no longer looks obviously cheap.
Growth
Flowserve operates in areas that should remain relevant for a long time. Many of its end markets need constant investment in safety, efficiency, emissions control, water handling, and energy infrastructure. Even when industrial spending slows, customers still need replacement parts and maintenance for installed systems. That gives the company some resilience compared with businesses that depend entirely on new project orders.
The company’s strategy also fits these long-term trends. Management has been emphasizing operational improvement, product simplification, better pricing, aftermarket expansion, and digital tools that help monitor equipment performance. This approach makes sense because it can raise margins without requiring unusually fast economic growth. It also increases the value of Flowserve’s installed base, which is one of the most important assets in this type of business.
Revenue growth has not been perfectly smooth. After a strong acceleration through 2023, the pace slowed through 2024 and turned slightly negative in the most recent periods. That soft patch matters, but it does not erase the broader trend: over five years, revenue per share has still grown at a high-single-digit annual pace, while earnings growth has been much stronger. In other words, the company has recently become better at converting sales into profit, even as top-line growth has cooled.
Cash generation is another supportive point. Free cash flow was weak and even negative at one point, but it has rebounded sharply and recently moved into the low hundreds of millions of dollars on a trailing basis. A recovery like that can be meaningful for an industrial company because it creates more flexibility for debt management, dividends, restructuring, and selective investment.
Recent company updates have also highlighted order activity tied to energy, nuclear, liquefied natural gas, general industrial projects, and water infrastructure. These are important markets because they involve long-lived assets where customers often prefer proven suppliers. If global capital spending in these categories remains healthy, Flowserve has a credible path to continued order support. Another notable catalyst is the company’s margin expansion effort: if management continues to improve pricing and manufacturing efficiency, earnings can grow faster than revenue for some time.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


