Stock Analysis · Forum Energy Technologies Inc (FET)
Overview
Forum Energy Technologies is an oilfield equipment and services company. It designs, manufactures, and supplies products used across the energy industry, especially in drilling, well construction, artificial lift, subsea operations, and offshore handling. The company also has exposure to industrial and defense-related applications through some of its specialized product lines. In simple terms, it sells the tools and equipment that energy producers and service companies need to find, drill, complete, and maintain wells, with a particularly important presence in offshore and international markets.
Based on its latest annual reporting structure, Forum Energy Technologies generates revenue from two main operating segments.
- Drilling and Completions: approximately 55% to 60% of revenue. This segment includes products used in drilling, downhole work, coiled tubing, stimulation, cementing, and well completion operations.
- Artificial Lift and Downhole: approximately 40% to 45% of revenue. This segment includes equipment used after a well is drilled, such as pumps, downhole components, and related products that help keep wells producing.
Geographically, the business is more diversified than many smaller U.S. oilfield suppliers. Recent company commentary has highlighted a meaningful international and offshore mix, which matters because those markets often move on longer project cycles than North American shale activity.
The long-term operating pattern has been mixed but improving in some areas. Revenue rose from roughly $540 million in 2021 to around $790 million in 2025. Gross profit improved over that period, and interest expense came down from earlier levels, showing some progress in the underlying business. At the same time, profitability has remained uneven, with losses reappearing in some years because this is still a cyclical and operationally sensitive company.
The business mix shows a company that has rebuilt sales meaningfully since the post-downturn period, but it has not yet converted that recovery into consistently strong bottom-line earnings. That gap between better revenue and still-fragile profitability is central to the long-term investment debate.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 31, 2026 | |
| Context | ||
| Sector | Energy | |
| Industry | Oil & Gas Equipment & Services | |
| Market Cap ⓘ | $1.02B | |
| Beta ⓘ | 0.68 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 15.08 |
| P/B Ratio ⓘ | 3.69 | 1.73 |
| FCF Yield ⓘ | 5.21% | 8.21% |
| Dividend Yield ⓘ | N/A | 3.46% |
| EBIT / EV ⓘ | 3.12% | 7.46% |
| PEG ⓘ | 2.05 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 13.20% | 26.85% |
| RPS Growth (5Y CAGR) ⓘ | -8.71% | 6.98% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -13.45% |
| BVPS Growth (5Y CAGR) ⓘ | -19.49% | 6.27% |
| Margin Growth (5Y Trend) ⓘ | 13.65% | 0.61% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 3.35% |
| DPS Growth (5Y CAGR) ⓘ | -40.24% | 16.79% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 4.87% | 11.53% |
| ROA (Latest) ⓘ | -0.21% | 6.01% |
| ROIC (5Y Median) ⓘ | -4.35% | 10.35% |
| ROA (5Y Median) ⓘ | -2.28% | 5.46% |
| Net Debt / EBIT (Latest) ⓘ | 5.07 | 1.61 |
| Net Debt / EBIT (5Y Median) ⓘ | 6.05 | 1.82 |
| Net Debt / EBITDA (Latest) ⓘ | 2.80 | 1.03 |
| Net Debt / Assets ⓘ | 25.14% | 16.57% |
| EBITDA / Interest ⓘ | 4.06 | 9.67 |
| Operating Margin (Latest) ⓘ | 4.59% | 15.60% |
| Operating Margin (5Y Median) ⓘ | 1.42% | 20.44% |
| Debt to Equity (Latest) ⓘ | 78.51% | 51.18% |
| Profit Margin (Latest) ⓘ | -0.19% | 8.82% |
| Free Cash Flow (Latest) ⓘ | $53.22M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +316.06% | +73.65% |
| 12M Return (excl. last month) ⓘ | +188.46% | +36.08% |
| 6M Return ⓘ | +42.92% | +6.58% |
| Price vs. 200-Day MA ⓘ | +45.46% | +11.74% |
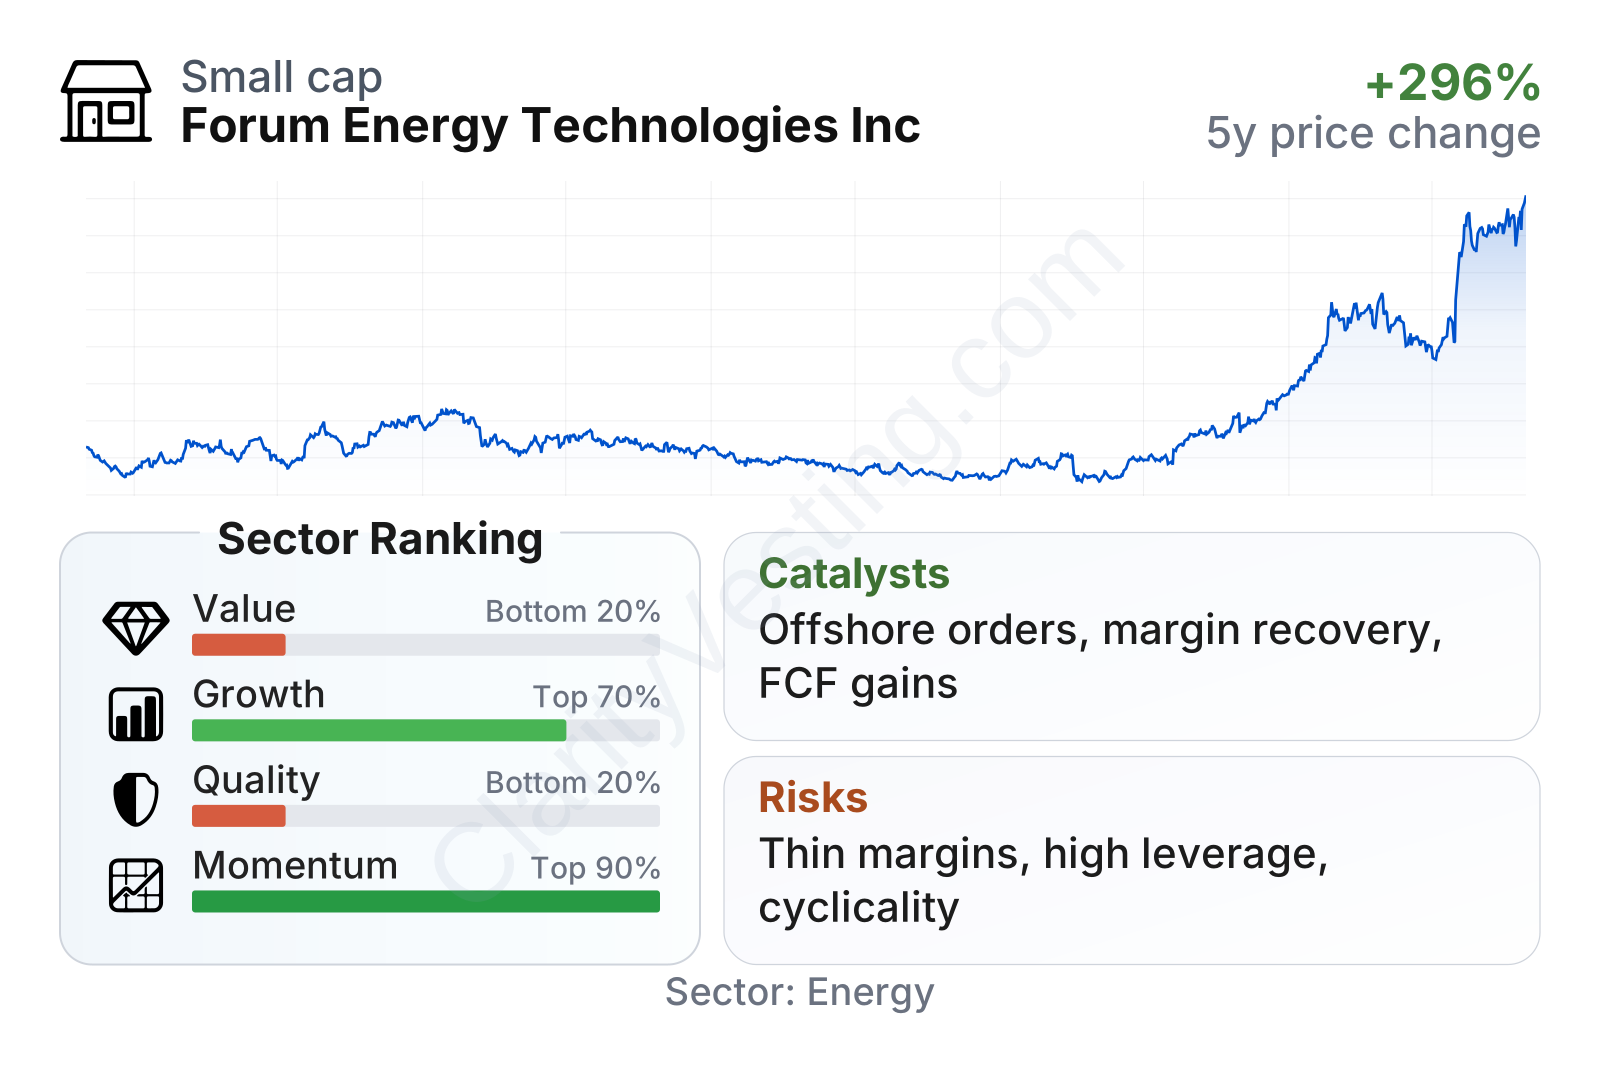
Forum Energy Technologies is a small-cap energy equipment company with a market value around $1 billion and a beta below 1, which suggests its share-price sensitivity has recently been lower than the overall market. The factor profile is unusual: momentum is very strong relative to the sector, growth is middle-of-the-pack, while quality and value rank weakly. In plain language, the market has rewarded the stock price strongly, but the business still trails many peers on profitability, returns on capital, and balance-sheet efficiency.
The balance of metrics points to a company in transition rather than one already operating at top-tier performance. Recent revenue growth has returned to positive territory and free cash flow is positive, but leverage remains elevated and margins are still thin compared with sector norms. That combination often leads to a stock that can move sharply when operating results improve, but also one that leaves less room for disappointment.
Growth
The company operates in a sector that should remain relevant for years, even as the energy system changes. Oil and gas equipment demand is still tied to global production needs, and offshore investment has become an important area because many large projects require long lead times and substantial equipment content. Forum’s positioning in offshore, subsea, and international markets gives it exposure to parts of the industry that are often less dependent on short-cycle U.S. land drilling.
Its strategy also has a reasonable industrial logic. Management has emphasized higher-value product lines, aftermarket opportunities, operational efficiency, and selective acquisitions. For a company of this size, that approach makes sense: it is difficult to outspend larger rivals, so growth has to come from niche product strength, better execution, and focus on categories where specialized engineering matters more than sheer scale.
Revenue growth has been volatile, which is normal in oilfield equipment, but the more recent trend has turned positive again after a weak 2025 period. That matters because it suggests the business is still finding demand despite uneven industry conditions. However, the pace remains below the sector median, so the company is recovering rather than leading the industry on growth.
Cash generation is one of the more encouraging points. Free cash flow moved from negative territory a few years ago to clearly positive levels more recently, even though it eased from its peak. For a cyclical manufacturer, positive cash flow is important because it supports debt service, operational flexibility, and targeted investment without relying as heavily on outside capital.
A notable catalyst is the company’s exposure to offshore and international spending, where project cycles can stay active for several years once awards are made. If offshore equipment demand remains healthy, Forum may benefit from steadier order flow than businesses tied mainly to U.S. shale. Another potential support is continued margin recovery if management keeps reducing manufacturing complexity and shifting the portfolio toward products with better pricing and service content.
Recent company updates have also pointed to contract wins and demand linked to offshore handling systems, subsea technologies, and defense-adjacent applications. Those opportunities are important because they broaden the company beyond purely domestic drilling cycles and can improve the durability of revenue over time.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


