Stock Analysis · First Advantage Corp (FA)
Overview
First Advantage Corp is a provider of employment background screening, identity, and verification services. In simple terms, it helps employers decide who they are hiring by checking a candidate’s criminal records, employment and education history, driving records, identity details, drug screening results, and other compliance-related information. The company sells mainly to businesses that hire at scale, and its services are built into recruiting and human resources workflows so that screening becomes part of the hiring process rather than a separate manual task.
Its business is largely recurring and transaction-driven: when customers hire more people, order more screenings, or add more verification modules, revenue tends to rise. First Advantage also benefits from the fact that screening is often a regulated and operationally important step for employers in industries such as transportation, healthcare, financial services, retail, and staffing.
Based on company disclosures, revenue is primarily generated from screening and verification services sold across a broad set of verticals and geographies. Public filings indicate a business mix centered on the following categories:
- Employment background screening and verification services: the clear majority of revenue. This includes criminal checks, employment and education verification, identity solutions, drug testing administration, fingerprinting, and compliance tools delivered to employers.
- Transportation-related screening: an important specialized portion of revenue, including commercial driver monitoring, Department of Transportation compliance support, and ongoing driver-related checks.
- Adjacent identity and fraud-related solutions: a smaller but strategically relevant portion, including identity verification and tools that can be used earlier in digital onboarding.
- Geographic mix: North America remains the largest contributor, with international operations providing a meaningful secondary stream through screening programs for multinational employers.
While exact percentages by service line are not always broken out in a precise way in recent filings, the company’s economics show a business where gross profit remains substantial, but bottom-line earnings have been more volatile because of acquisition-related costs, operating expenses, and interest expense. Revenue expanded sharply in 2025, pointing to a much larger operating base than a few years earlier.
The multiyear operating flow also shows an important shift: revenue has grown materially since 2021, operating income recovered in 2025 after a weak 2024, and cash generation has remained more resilient than net income. That gap matters because it suggests the business is more stable operationally than headline earnings alone might imply.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Specialty Business Services | |
| Market Cap ⓘ | $3.36B | |
| Beta ⓘ | 1.14 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 139.71 | 22.29 |
| P/B Ratio ⓘ | 2.63 | 1.98 |
| FCF Yield ⓘ | 7.17% | 6.26% |
| Dividend Yield ⓘ | N/A | 1.92% |
| EBIT / EV ⓘ | 3.41% | 4.83% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 14.90% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | 18.19% | 7.76% |
| EPS Growth (5Y CAGR) ⓘ | -13.81% | -13.17% |
| BVPS Growth (5Y CAGR) ⓘ | 0.60% | 6.13% |
| Margin Growth (5Y Trend) ⓘ | 1.00% | 0.74% |
| FCF Growth (5Y CAGR) ⓘ | 3.06% | 10.79% |
| DPS Growth (5Y CAGR) ⓘ | -21.74% | 9.41% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 4.27% | 10.75% |
| ROA (Latest) ⓘ | 0.66% | 5.41% |
| ROIC (5Y Median) ⓘ | 3.49% | 9.37% |
| ROA (5Y Median) ⓘ | 0.88% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | 10.10 | 2.04 |
| Net Debt / EBIT (5Y Median) ⓘ | 4.68 | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | 4.22 | 1.39 |
| Net Debt / Assets ⓘ | 48.12% | 19.27% |
| EBITDA / Interest ⓘ | 3.03 | 9.58 |
| Operating Margin (Latest) ⓘ | 10.74% | 10.49% |
| Operating Margin (5Y Median) ⓘ | 8.35% | 10.30% |
| Debt to Equity (Latest) ⓘ | 157.74% | 64.82% |
| Profit Margin (Latest) ⓘ | 1.51% | 6.67% |
| Free Cash Flow (Latest) ⓘ | $240.87M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +49.39% | +67.77% |
| 12M Return (excl. last month) ⓘ | +33.75% | +12.05% |
| 6M Return ⓘ | +48.38% | 0.00% |
| Price vs. 200-Day MA ⓘ | +21.92% | +0.67% |
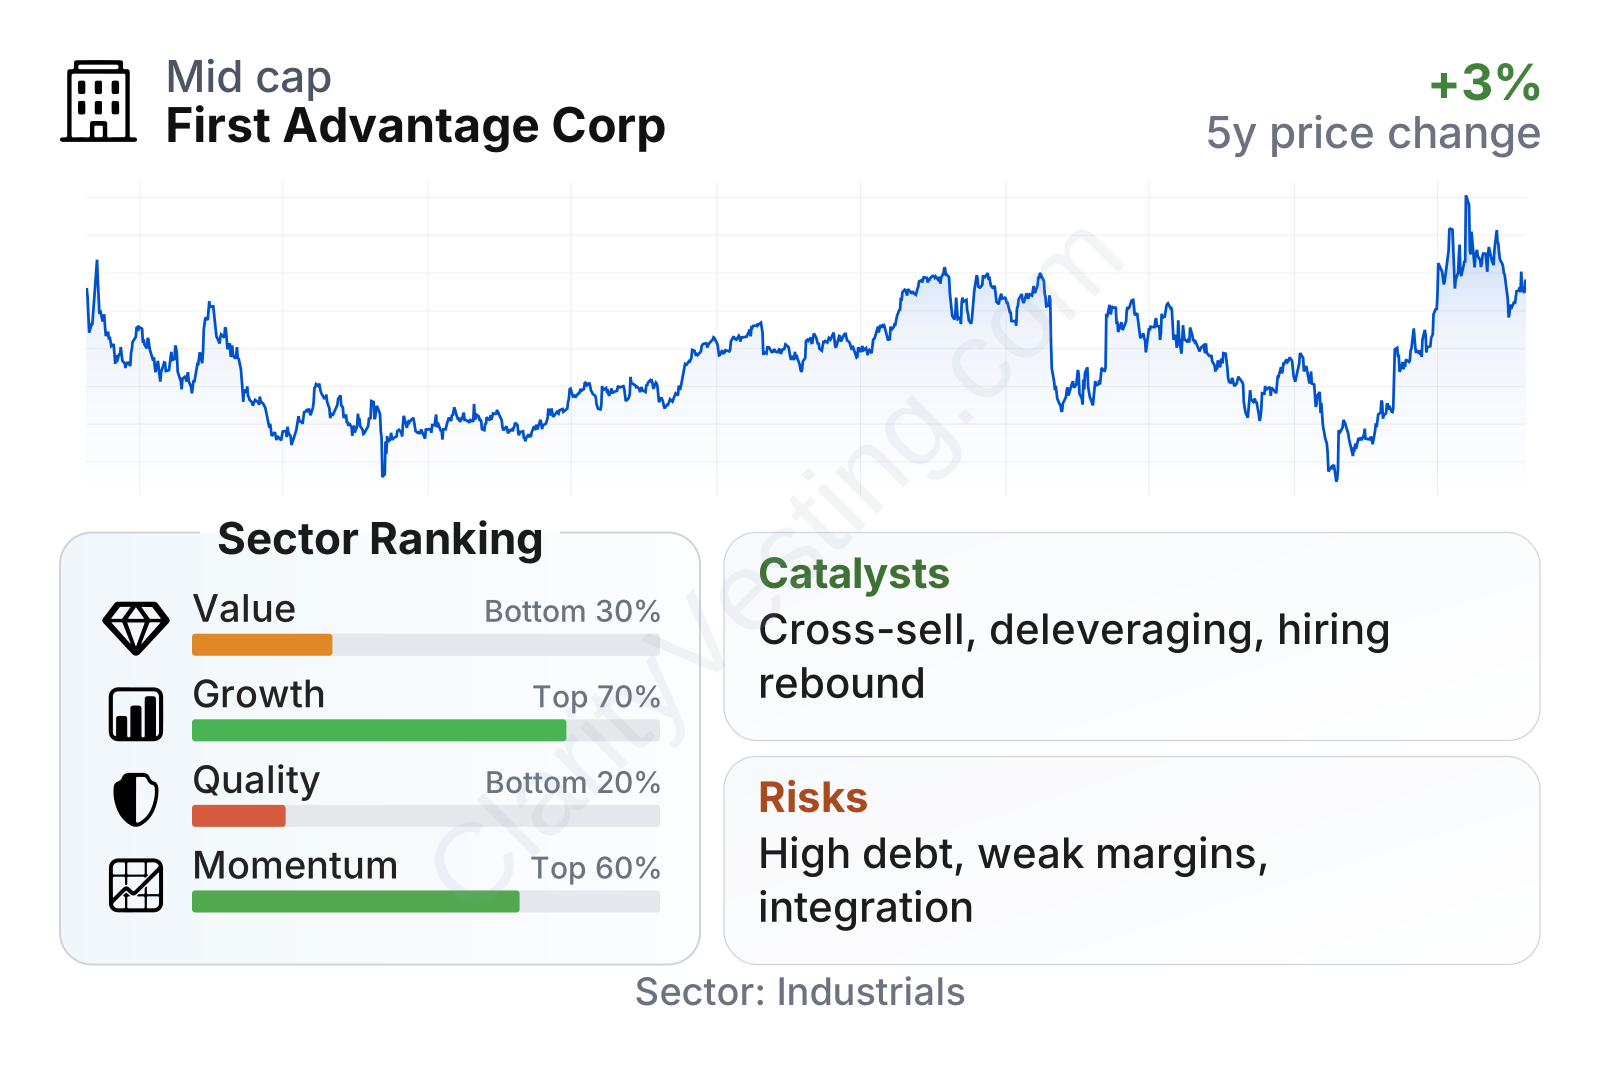
First Advantage sits in the mid-cap range, large enough to have global reach and enterprise customers, but still small compared with the biggest information and HR workflow platforms. The table points to a mixed profile: growth ranks better than much of the sector, momentum has recently improved, but quality metrics remain weak. The most striking contradictions are a very high earnings multiple alongside a healthy free cash flow yield and low accounting profitability. That usually means the market is looking through depressed earnings and focusing more on normalization potential and cash generation.
The share price history reflects that uncertainty. The stock has gone through deep swings since listing, including a major rebound in 2026 after a sharp drop earlier in the year. That kind of move often signals that the market is reassessing the company after major integration steps, changes in leverage expectations, or improving operating trends rather than assigning it a simple steady-growth profile.
Growth
The company operates in a sector with favorable long-term drivers. Hiring compliance is not a temporary trend: employers continue to face regulation, reputational risk, fraud concerns, and pressure to make recruiting faster and more automated. As hiring processes become more digital and more global, the need for integrated screening and identity verification tends to increase. This gives First Advantage exposure to both employment activity and the broader modernization of HR and onboarding systems.
Its strategy also makes industrial sense. Background screening is a scale business: large databases, workflow integrations, compliance know-how, and customer relationships all become more valuable as volume rises. Employers generally prefer vendors that can handle multiple check types across many locations, which favors platforms with broad capabilities. First Advantage has been building that type of platform, and recent revenue acceleration suggests the company has added meaningful scale.
Recent growth has been anything but linear. After contracting in 2023 and much of 2024, revenue growth turned sharply positive, with 2025 showing exceptionally strong expansion before moderating back to more normal levels in 2026. That pattern usually points to a major business change rather than simple organic demand alone, such as acquisition effects, customer additions, or a broader expansion of service scope. Even after the surge faded, year-over-year growth in 2026 remained ahead of the sector median.
Cash generation adds an important layer to the growth case. Free cash flow fell dramatically at one point, then recovered to more than $200 million on a trailing basis. For a company in a service-heavy business, that rebound matters because it indicates the enlarged platform can still convert a good share of revenue into cash, even when reported earnings are under pressure. That cash can support debt reduction, integration work, product development, and selective acquisitions.
A meaningful catalyst is the company’s ability to cross-sell more services into existing employer accounts. A customer that starts with a criminal background check may later add drug testing, identity verification, ongoing monitoring, or international screening. Another catalyst is workflow integration: once a screening provider is embedded into hiring software and compliance processes, switching becomes more disruptive. In addition, demand for identity-related checks can grow even outside traditional hiring volumes as digital onboarding and fraud controls become more important.
Recent company communications and filings have also highlighted strategic expansion through acquisitions and platform breadth. If integration proceeds well, the combined business could benefit from better scale, broader product coverage, and stronger relevance with multinational customers that want fewer vendors.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


