Stock Analysis · EZCORP Inc (EZPW)
Overview
EZCORP Inc is a specialty financial services company best known for pawn lending. It operates pawn stores in the United States and Latin America, where customers can borrow money using personal items as collateral or sell merchandise directly to the store. If a loan is not repaid, the pledged item can be sold through the retail channel inside the stores. This makes EZCORP a hybrid business: part short-term lender, part secondhand retailer.
The company’s revenue is mainly tied to activity inside its pawn operations. Based on recent annual reporting, the largest sources of revenue are:
- Merchandise sales: approximately 56% of total revenue. This is the sale of forfeited collateral and other secondhand goods through EZCORP stores.
- Pawn service charges: approximately 36% of total revenue. These are fees and finance charges earned on pawn loans.
- Other revenue: approximately 8%. This includes smaller activities such as jewelry scrapping and other ancillary sources.
That mix matters because merchandise sales bring volume, while pawn service charges are usually the more structurally attractive earnings driver. As loan balances grow, fee income can rise without the company needing to add revenue lines outside its core expertise. Over the last few years, total revenue, gross profit, operating income, and net income have all moved higher overall, showing that growth has not come only from store traffic but also from improving profitability.
The business profile is also relatively straightforward for non-specialists: customers often use pawn loans when they need quick access to cash and may not want, or may not qualify for, traditional bank credit. That gives EZCORP exposure to a part of consumer finance that tends to remain relevant across different economic conditions.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 10, 2026 | |
| Context | ||
| Sector | Financial Services | |
| Industry | Credit Services | |
| Market Cap ⓘ | $1.87B | |
| Beta ⓘ | 0.71 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 15.53 | 12.38 |
| P/B Ratio ⓘ | 2.24 | 1.23 |
| FCF Yield ⓘ | 7.51% | 10.23% |
| Dividend Yield ⓘ | N/A | 3.01% |
| EBIT / EV ⓘ | 10.17% | 8.08% |
| PEG ⓘ | 0.28 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 34.70% | 9.50% |
| RPS Growth (5Y CAGR) ⓘ | 4.05% | 12.21% |
| EPS Growth (5Y CAGR) ⓘ | 20.86% | -9.62% |
| BVPS Growth (5Y CAGR) ⓘ | 0.58% | 4.98% |
| Margin Growth (5Y Trend) ⓘ | 8.08% | -4.07% |
| FCF Growth (5Y CAGR) ⓘ | 48.29% | 4.76% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 8.79% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 11.05% | 9.35% |
| ROE (Latest) ⓘ | 14.48% | 13.91% |
| ROA (Latest) ⓘ | 7.69% | 1.53% |
| ROIC (5Y Median) ⓘ | 5.93% | 7.86% |
| ROE (5Y Median) ⓘ | 7.35% | 12.22% |
| ROA (5Y Median) ⓘ | 3.84% | 1.29% |
| Net Debt / EBIT (Latest) ⓘ | 2.09 | 0.99 |
| Net Debt / EBIT (5Y Median) ⓘ | 4.38 | 0.73 |
| Net Debt / EBITDA (Latest) ⓘ | 1.81 | 0.93 |
| Operating Margin (Latest) ⓘ | 15.10% | 22.19% |
| Operating Margin (5Y Median) ⓘ | 8.77% | 24.30% |
| Debt to Equity (Latest) ⓘ | 69.62% | 60.24% |
| Profit Margin (Latest) ⓘ | 9.99% | 26.49% |
| Free Cash Flow (Latest) ⓘ | $140.44M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +274.19% | +88.52% |
| 12M Return (excl. last month) ⓘ | +93.74% | +19.65% |
| 6M Return ⓘ | +11.20% | +6.00% |
| Price vs. 200-Day MA ⓘ | +8.37% | +3.61% |
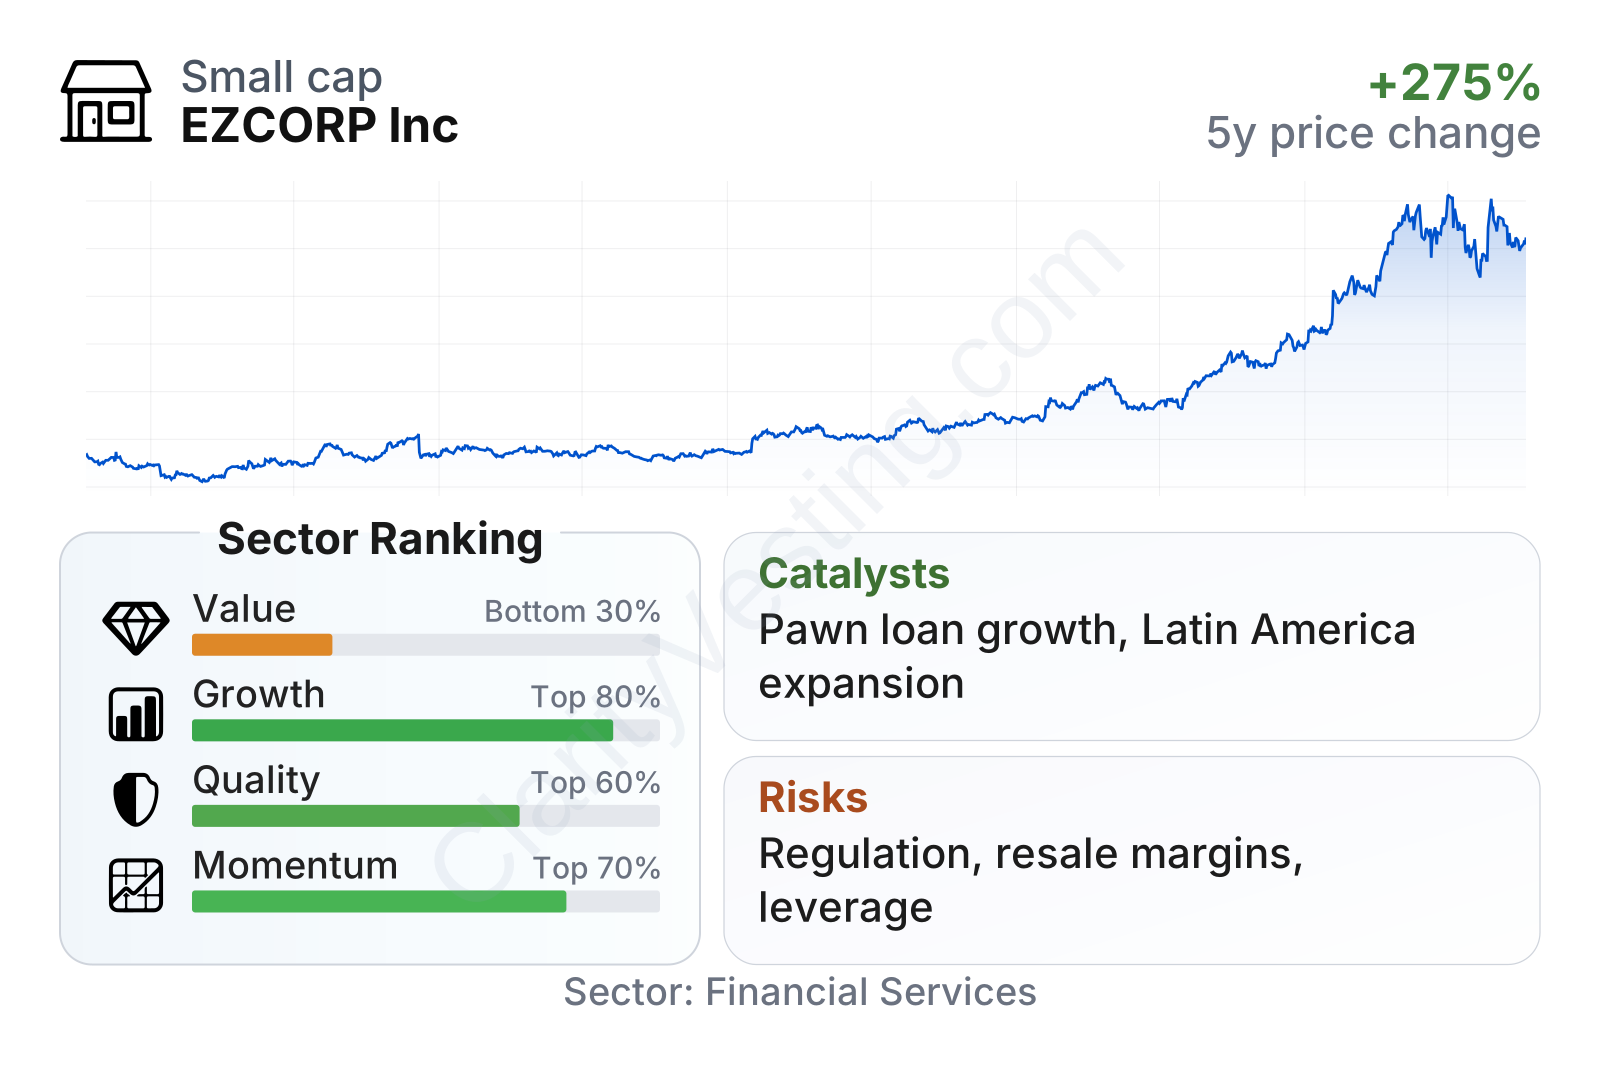
EZCORP is a mid-sized company within financial services, and its recent market performance has been very strong, with the share price rising several times over the last three years. In the factor breakdown, growth and momentum look notably stronger than the sector median, while value looks less attractive because the stock now trades above typical sector multiples on price-to-book and slightly above on earnings. Quality is mixed: returns on capital and assets are solid, but margins remain below many peers and leverage is somewhat heavier than the sector norm.
One notable point is the combination of strong earnings expansion and healthy free cash flow generation. That helps explain why the market has re-rated the stock upward. At the same time, the absence of a dividend and a valuation no longer sitting near distressed levels suggest the stock is now being judged more on execution than on recovery potential alone.
Growth
EZCORP operates in a niche that can still expand over time. Pawn lending is part of the broader non-bank consumer credit market, a segment supported by customers seeking small-dollar, fast-turnaround liquidity. In many regions, especially where banking access is limited or uneven, pawn remains a practical product. The company’s presence in both the United States and Latin America gives it exposure to markets where demand for collateral-based lending can stay durable.
Its strategy appears coherent for long-term expansion because it focuses on the core pawn model rather than spreading into too many unrelated businesses. Growth can come from opening stores, improving loan balances per store, increasing merchandise turnover, and expanding in underpenetrated markets. The economics of the model also improve when pledged inventories are managed well and retail sell-through remains efficient.
Earnings per share have moved up steadily over the last several fiscal years, rising from roughly $0.75 in fiscal 2022 to around $1.60 on a trailing basis in 2026. That kind of progression suggests the business has been scaling with better operating performance, not just generating sales growth without profit conversion. The company’s five-year EPS growth rate is well ahead of the sector median, which supports the view that recent progress is more than a short-lived rebound.
Book value per share has also increased, with a sharper step-up in the latest annual period. That matters for a pawn operator because the balance sheet supports the loan book and inventory base. The longer-term growth rate in book value is not especially high versus the sector, but the recent acceleration suggests that retained earnings are beginning to translate more visibly into shareholder equity.
A recent positive catalyst is the company’s continued operating momentum through fiscal 2025 and into 2026, reflected in stronger returns, higher earnings, and a rising market valuation. Another supportive element is that pawn demand can remain resilient when consumers face budget pressure, creating a business environment where loan demand may stay firm even if the broader economy slows.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


