Stock Analysis · Extra Space Storage Inc (EXR)
Overview
Extra Space Storage Inc. is a self-storage real estate investment trust, or REIT. In simple terms, it owns, operates, and manages storage properties where individuals and businesses rent space to store furniture, household goods, vehicles, inventory, and other items. The company is one of the largest self-storage operators in the United States, with a national footprint that combines wholly owned stores, joint venture properties, and stores managed for third parties.
Its business model is relatively easy to understand: it earns recurring rental income from customers who pay monthly for storage units, and it also collects management and other fees from stores it runs on behalf of other owners. Because storage leases are usually short-term, the company can adjust pricing more quickly than many other real estate landlords.
The main revenue sources are concentrated in property operations, with a smaller but still meaningful contribution from ancillary activities.
- Rental income from self-storage properties: approximately 85% to 90% of total revenue. This is the core business and includes rent from units at owned and consolidated properties.
- Tenant reinsurance and related tenant services: approximately 5% to 10%. This generally includes tenant insurance-related income and other customer-related service revenue.
- Management fees and other property-related income: approximately 3% to 7%. This comes from managing stores for third-party owners and from other operational fees.
Over the last several years, revenue expanded strongly, but the earnings flow shows a familiar REIT pattern: operating profit stayed robust while interest expense rose as debt costs increased. That matters because self-storage operations themselves appear highly profitable, while financing conditions have become a larger part of the investment debate.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Real Estate | |
| Industry | REIT - Industrial | |
| Market Cap ⓘ | $30.87B | |
| Beta ⓘ | 1.17 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 31.15 | 17.85 |
| P/B Ratio ⓘ | 2.38 | 0.87 |
| FCF Yield ⓘ | 5.71% | 7.30% |
| Dividend Yield ⓘ | 4.59% | 4.83% |
| EBIT / EV ⓘ | 5.79% | 3.78% |
| PEG ⓘ | 5.32 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 3.80% | 5.35% |
| RPS Growth (5Y CAGR) ⓘ | 8.52% | 6.02% |
| EPS Growth (5Y CAGR) ⓘ | -15.70% | -10.65% |
| BVPS Growth (5Y CAGR) ⓘ | 27.71% | 0.43% |
| Margin Growth (5Y Trend) ⓘ | -3.58% | -0.69% |
| FCF Growth (5Y CAGR) ⓘ | 17.83% | 5.40% |
| DPS Growth (5Y CAGR) ⓘ | 10.88% | 5.07% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 5.69% |
| ROE (Latest) ⓘ | 7.36% | 7.37% |
| ROA (Latest) ⓘ | 3.25% | 2.85% |
| ROIC (5Y Median) ⓘ | 7.00% | 4.26% |
| ROE (5Y Median) ⓘ | 9.65% | 6.04% |
| ROA (5Y Median) ⓘ | 4.05% | 2.45% |
| Net Debt / EBIT (Latest) ⓘ | 5.64 | 7.55 |
| Net Debt / EBIT (5Y Median) ⓘ | 8.64 | 8.26 |
| Net Debt / EBITDA (Latest) ⓘ | 4.34 | 5.26 |
| Net Debt / Assets ⓘ | 46.25% | 37.45% |
| EBITDA / Interest ⓘ | 2.11 | 4.11 |
| Operating Margin (Latest) ⓘ | 70.97% | 33.86% |
| Operating Margin (5Y Median) ⓘ | 50.31% | 37.49% |
| Debt to Equity (Latest) ⓘ | 108.72% | 88.76% |
| Profit Margin (Latest) ⓘ | 27.28% | 18.94% |
| Free Cash Flow (Latest) ⓘ | $1.76B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +51.00% | +36.33% |
| 12M Return (excl. last month) ⓘ | +2.00% | +4.32% |
| 6M Return ⓘ | +3.65% | -1.74% |
| Price vs. 200-Day MA ⓘ | +2.65% | -1.42% |
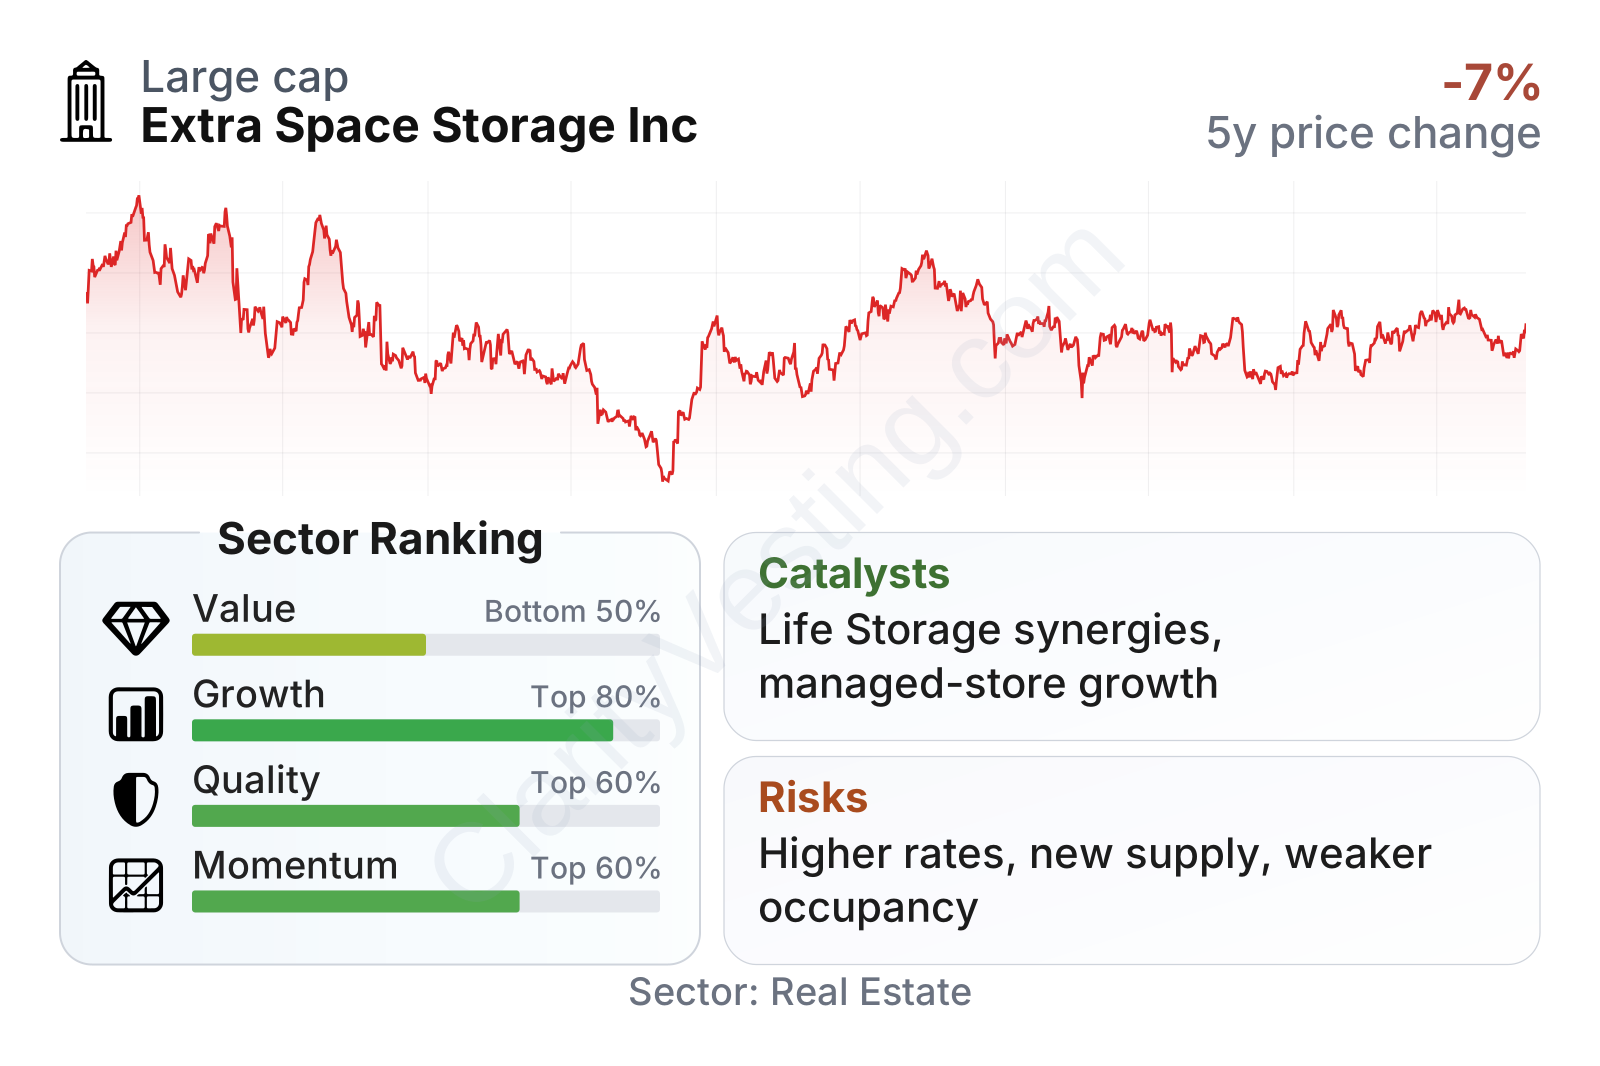
Extra Space Storage is a large publicly traded REIT with a market value around the large-cap range for real estate. The overall picture from the metrics is mixed but understandable. Growth and quality look stronger than many peers, helped by solid multi-year expansion in revenue per share, free cash flow, and book value per share. Profitability is also healthy for the sector, with margins and asset returns above many real estate companies.
At the same time, valuation is not especially cheap on common measures. The stock trades above sector medians on both earnings and book value multiples, while recent share-price momentum has been less impressive than the broader real estate group. In other words, the market is still assigning a premium to the company’s scale and operating strength, even though financing costs and growth normalization have reduced some of the enthusiasm seen earlier in the cycle.
Growth
Self-storage is a niche within real estate that has shown durable demand over time. The sector benefits from life events that keep happening in all economic environments: moving, downsizing, marriage, divorce, death, college transitions, military relocation, and small business inventory needs. Demand is not perfectly recession-proof, but it is more diversified than many other property types because it is linked to many small customer decisions rather than a handful of large tenants.
Extra Space Storage’s strategy for future growth is logical. It combines three levers: increasing rent at existing stores, acquiring additional properties when returns make sense, and expanding its third-party management platform. That management business is important because it gives the company market intelligence, brand reach, and acquisition opportunities without always requiring immediate balance-sheet spending.
The company’s scale also supports growth. A national platform can spread marketing, technology, and administrative costs across a very large store base. This can help occupancy, pricing, and customer acquisition over time. In self-storage, operational execution matters a lot because small differences in occupancy and rent can translate into meaningful changes in property income.
Revenue per share has trended upward over the past five years, although the pace has slowed recently after a period of stronger expansion. That suggests the company is still growing on a per-share basis, but it is now operating in a more mature phase than during the post-pandemic surge in storage demand.
The dividend per share also rose materially over the last five years, then flattened more recently. For a REIT, that pattern often signals that management still sees healthy cash generation, but is being more measured while the sector works through higher interest rates and more moderate rent growth.
A major recent catalyst has been the integration and optimization work following the large Life Storage combination announced in 2023 and absorbed into operating results afterward. The merger significantly increased scale, market density, and the managed-store platform. If the company continues to improve pricing, occupancy, and operating efficiency across the combined portfolio, that could remain an important contributor to medium-term growth.
Another opportunity comes from industry structure. Self-storage is still fragmented despite the presence of large public operators. That leaves room for national leaders like Extra Space Storage to keep gaining share through branding, revenue management tools, digital leasing, and selective acquisitions of independent properties.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


