Stock Analysis · Exponent Inc (EXPO)
Overview
Exponent Inc is a specialized consulting company that helps clients solve complicated technical, scientific, engineering, and health-related problems. Its work often starts when something has gone wrong or could go wrong: a product failure, an accident, a chemical exposure question, a construction dispute, a cybersecurity issue, or a regulatory challenge. The company is best known for providing independent analysis, testing, expert reports, and testimony for corporations, law firms, insurers, and government agencies.
Unlike many industrial companies, Exponent does not mainly sell physical products. It sells expert time and judgment. That makes the business relatively asset-light and allows a large share of revenue to turn into profit and cash when utilization is strong.
Based on recent company reporting, Exponent organizes revenue into two main segments:
- Engineering and Other Scientific: about 82% of revenue. This includes failure analysis, biomechanics, electrical engineering, construction consulting, data sciences, thermal sciences, materials and corrosion, vehicle engineering, and work tied to litigation, product safety, and insurance claims.
- Environmental and Health: about 18% of revenue. This includes chemical regulation, toxicology, epidemiology, ecological and environmental services, occupational health, and support for clients facing public health, contamination, or compliance questions.
Revenue is also diversified by client need rather than by one single end market. In its filings, Exponent regularly points to demand linked to litigation support, regulatory review, product design and safety, recall matters, insurance claims, and increasingly complex technology questions across transportation, consumer products, life sciences, utilities, and industrial systems.
The business model is attractive in simple terms: recruit highly qualified experts, build a reputation for independence, and use that reputation to win high-value assignments where clients care more about credibility than low price. Over the last several years, revenue has moved upward while profitability has remained well above most companies in its broader sector, even though accounting presentation changes make some line items less comparable across years.
The overall picture is a company with modest size, very high gross economics for a services firm, and a revenue base spread across many types of technical problems rather than one large contract stream.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Engineering & Construction | |
| Market Cap ⓘ | $3.07B | |
| Beta ⓘ | 0.69 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 28.94 | 22.45 |
| P/B Ratio ⓘ | 11.10 | 1.98 |
| FCF Yield ⓘ | 3.54% | 6.31% |
| Dividend Yield ⓘ | 1.90% | 1.96% |
| EBIT / EV ⓘ | 4.58% | 4.81% |
| PEG ⓘ | 2.03 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 12.00% | 9.10% |
| RPS Growth (5Y CAGR) ⓘ | 5.12% | 7.75% |
| EPS Growth (5Y CAGR) ⓘ | -12.46% | -13.59% |
| BVPS Growth (5Y CAGR) ⓘ | 7.70% | 6.22% |
| Margin Growth (5Y Trend) ⓘ | -0.75% | 0.72% |
| FCF Growth (5Y CAGR) ⓘ | 0.96% | 10.98% |
| DPS Growth (5Y CAGR) ⓘ | 10.35% | 9.48% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 28.89% | 10.92% |
| ROA (Latest) ⓘ | 15.81% | 5.41% |
| ROIC (5Y Median) ⓘ | 27.41% | 9.21% |
| ROA (5Y Median) ⓘ | 15.33% | 4.94% |
| Net Debt / EBIT (Latest) ⓘ | 0.10 | 2.07 |
| Net Debt / EBIT (5Y Median) ⓘ | -1.17 | 2.28 |
| Net Debt / EBITDA (Latest) ⓘ | 0.09 | 1.43 |
| Net Debt / Assets ⓘ | 2.16% | 19.27% |
| EBITDA / Interest ⓘ | N/A | 9.53 |
| Operating Margin (Latest) ⓘ | 22.62% | 10.50% |
| Operating Margin (5Y Median) ⓘ | 25.32% | 10.27% |
| Debt to Equity (Latest) ⓘ | 27.97% | 65.48% |
| Profit Margin (Latest) ⓘ | 19.71% | 6.62% |
| Free Cash Flow (Latest) ⓘ | $108.56M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | -20.08% | +58.56% |
| 12M Return (excl. last month) ⓘ | +1.25% | +15.63% |
| 6M Return ⓘ | +1.23% | +4.19% |
| Price vs. 200-Day MA ⓘ | -0.86% | +0.93% |
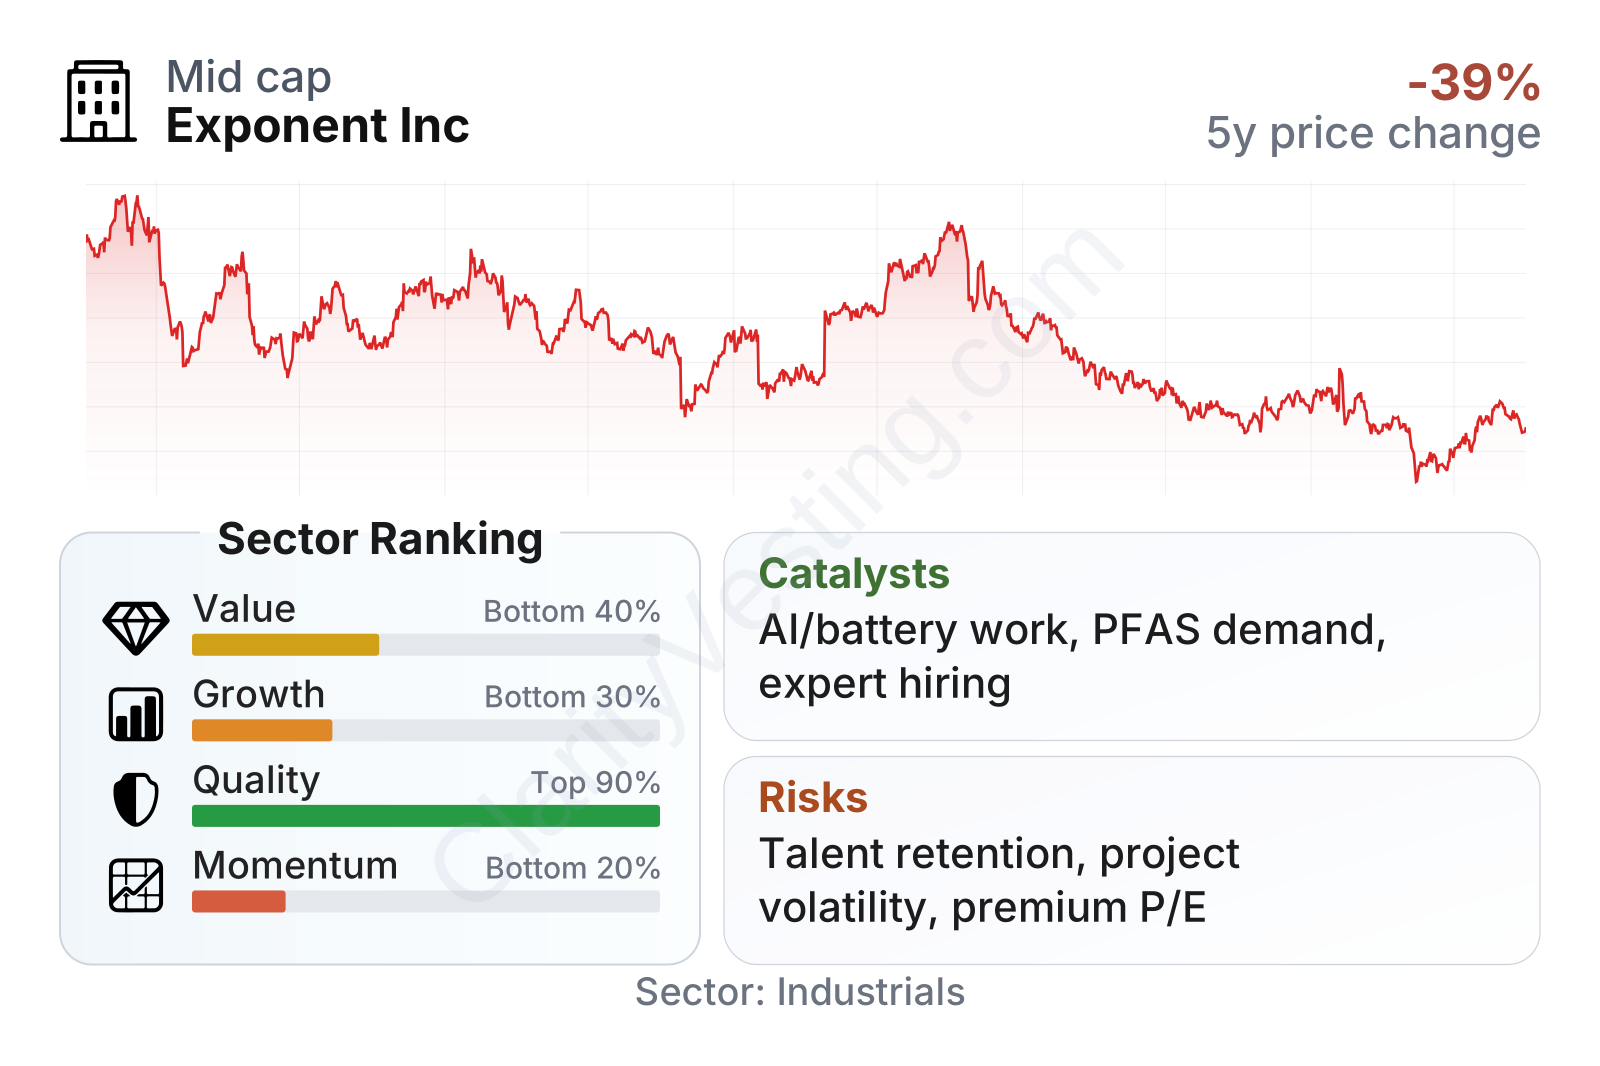
Exponent stands out more for quality than for cheapness or stock momentum. Returns on capital and assets are far above sector medians, margins are unusually strong, and leverage remains low. On the other hand, the valuation still sits above the sector on earnings and far above it on book value, while recent share price performance has lagged much of the industrial universe. In short, the company looks financially strong, but the market has not recently treated it like a fast-growing cyclical winner.
Growth
Exponent operates in areas with durable long-term demand drivers. Product complexity is increasing across autos, medical devices, electronics, chemicals, utilities, and infrastructure. Regulation is also getting heavier in many industries, especially where safety, environmental exposure, and health outcomes matter. On top of that, litigation and insurance-related work tends to persist through different economic environments, because accidents, disputes, and product issues do not disappear when growth slows.
The company’s strategy also makes sense for steady long-term expansion. Exponent adds senior talent in targeted practice areas, then builds multidisciplinary teams around them. That approach is not as flashy as acquiring large businesses, but it fits a reputation-based expert firm. It can widen the menu of services without adding much balance-sheet risk.
Recent revenue trends look constructive. Year-over-year growth has generally stayed positive and has recently accelerated into the low-double-digit to above-20% range, which is strong for a consulting business of this type. That does not automatically mean a new long-term growth rate has been established, but it does suggest healthy demand and good execution in the near term.
Cash generation remains solid, although not perfectly smooth from period to period. Free cash flow has stayed comfortably positive, which matters because this is a people-driven business with limited need for heavy capital spending. That gives Exponent flexibility to fund hiring, office needs, dividends, and occasional share repurchases without depending heavily on debt.
A notable opportunity area is the spread of new technical risk categories. Artificial intelligence systems, battery technologies, connected devices, autonomous features, cyber-physical systems, PFAS and other chemical concerns, and grid modernization all create more situations where clients need independent scientific and engineering analysis. Exponent has been highlighting demand in areas such as data sciences, biomechanics, vehicle systems, utilities, and chemical regulation, which fits these broader trends.
Recent company updates have also pointed to continued investment in expert hiring and selected high-demand disciplines. For a firm like Exponent, that is important: future growth depends less on factories or equipment and more on whether it can attract respected specialists whose credentials can support premium billing rates and long client relationships.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


