Stock Analysis · Endeavour Silver Corp (EXK)
Overview
Endeavour Silver Corp is a precious-metals mining company focused mainly on silver, with gold as an important by-product. The company operates producing mines in Mexico and has also been advancing a larger development project in Jalisco called Terronera, which is expected to become a major part of its future production profile. In simple terms, Endeavour Silver explores for mineral deposits, develops mines, extracts ore, processes it, and sells the resulting silver and gold.
Its revenue comes overwhelmingly from metal sales. Based on the company’s recent annual reporting and operating disclosures, the business can be understood through the following main revenue streams:
- Silver sales: approximately 50% to 60% of revenue in a typical year. This is the company’s core exposure and includes silver produced from its operating mines.
- Gold sales: approximately 40% to 50% of revenue. Gold is not the main corporate identity, but it makes a major contribution to cash flow because it is produced alongside silver.
- Lead and zinc or other by-product sales: generally 0% to 5%, depending on mine mix and reporting period.
Geographically, Endeavour Silver is highly concentrated. Its producing assets and near-term growth pipeline are centered in Mexico, so the company’s operating performance depends heavily on mine execution, local permitting, labor availability, and the Mexican regulatory environment.
The recent financial flow also shows an important shift: revenue expanded sharply in 2025, but costs rose even faster, pushing operating results and net income deeply negative that year. That pattern suggests the company was in a transition phase, with growth spending and ramp-related pressure weighing on near-term profitability rather than a simple steady-state mining business.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Silver | |
| Market Cap ⓘ | $2.43B | |
| Beta ⓘ | 2.48 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 41.00 | 16.92 |
| P/B Ratio ⓘ | 3.82 | 1.66 |
| FCF Yield ⓘ | -1.69% | 5.83% |
| Dividend Yield ⓘ | N/A | 2.07% |
| EBIT / EV ⓘ | 4.22% | 6.38% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 139.40% | 11.25% |
| RPS Growth (5Y CAGR) ⓘ | 14.33% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | 54.79% | -15.24% |
| BVPS Growth (5Y CAGR) ⓘ | 10.07% | 5.49% |
| Margin Growth (5Y Trend) ⓘ | -39.44% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 5.91% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 11.16% | 9.59% |
| ROA (Latest) ⓘ | 5.60% | 4.92% |
| ROIC (5Y Median) ⓘ | 1.76% | 7.91% |
| ROA (5Y Median) ⓘ | 1.40% | 3.92% |
| Net Debt / EBIT (Latest) ⓘ | 0.09 | 1.36 |
| Net Debt / EBIT (5Y Median) ⓘ | -2.63 | 1.69 |
| Net Debt / EBITDA (Latest) ⓘ | 0.05 | 0.93 |
| Net Debt / Assets ⓘ | 0.80% | 13.69% |
| EBITDA / Interest ⓘ | 9.05 | 12.38 |
| Operating Margin (Latest) ⓘ | 15.80% | 13.24% |
| Operating Margin (5Y Median) ⓘ | 9.28% | 11.82% |
| Debt to Equity (Latest) ⓘ | 34.64% | 40.30% |
| Profit Margin (Latest) ⓘ | 8.91% | 6.38% |
| Free Cash Flow (Latest) ⓘ | -$40.96M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +239.18% | +73.47% |
| 12M Return (excl. last month) ⓘ | +49.85% | +27.59% |
| 6M Return ⓘ | -11.41% | -4.02% |
| Price vs. 200-Day MA ⓘ | -15.75% | -0.65% |
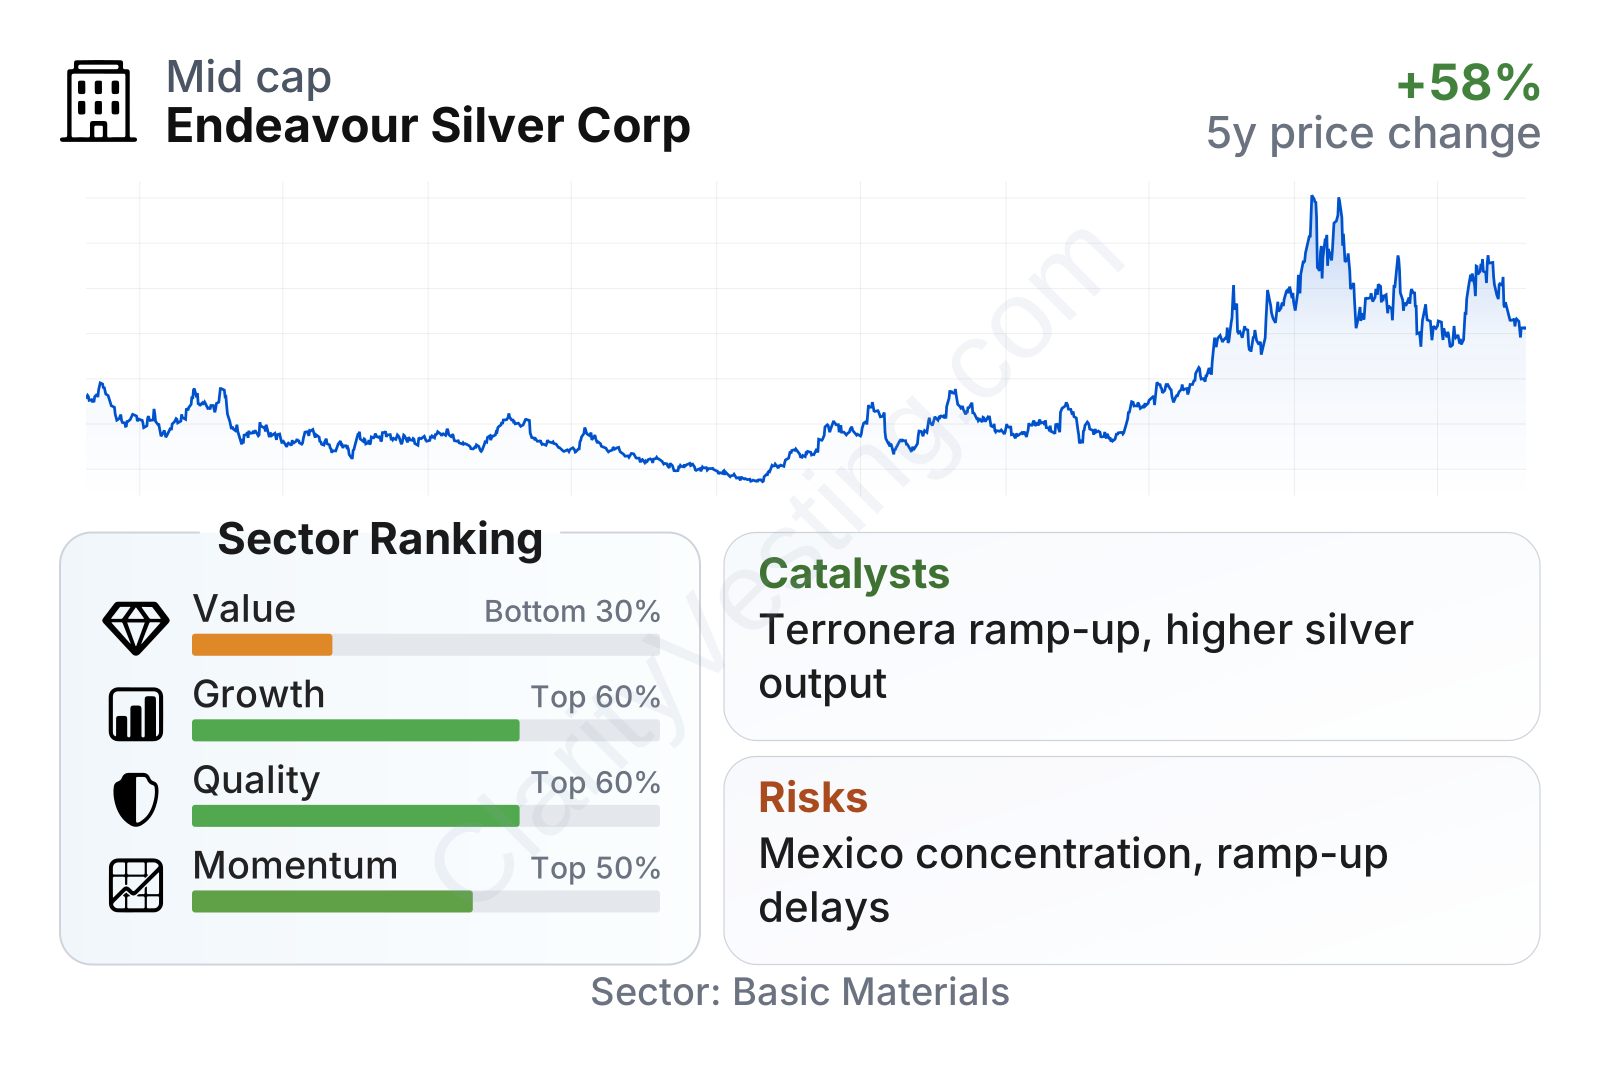
Endeavour Silver is now a mid-sized silver miner with a stock that has been highly volatile. Over the last several years, the share price has moved through large swings, which is common for smaller precious-metals producers but still notable here given the company’s beta above 2.4. In the factor breakdown, growth and quality land around the better half of the sector, while value ranks weaker. That combination usually points to a company priced for improving operations rather than one trading at a clear discount. The balance sheet remains a relative strength, but free cash flow is still negative, which limits financial flexibility while projects are being built and ramped up.
Growth
Endeavour Silver operates in a sector that has long-term support from both investment demand and industrial use. Silver has a dual role: it is a precious metal, often benefiting from inflation concerns and monetary uncertainty, and it is also an industrial input used in electronics, solar applications, and electrical systems. That gives the broader sector an attractive demand backdrop, although prices remain cyclical and can change quickly.
For company-specific growth, the central driver is the transition from a smaller producer with aging operations into one with a larger, newer asset base. Terronera is the most important piece of that plan. Management has presented it as a lower-cost, higher-grade mine intended to lift production and improve margins once commercial operations stabilize. If the project performs close to expectations, Endeavour Silver could emerge with a meaningfully different earnings profile than it had during the last several years.
Revenue growth has been unusually strong recently, including year-over-year increases far above the sector median. However, that strength should be read carefully. In mining, sudden growth can come from higher metal prices, changes in production mix, acquisitions, or project-related transitions rather than a smooth, repeatable trend. Endeavour’s recent surge looks more like a step-change period than a stable growth pattern.
Free cash flow gives the clearest reality check. It has remained negative, although the deficit has improved from earlier lows. That is consistent with a miner investing heavily in development. Negative free cash flow is not automatically a red flag for a growing mining company, but it does mean the business still needs successful execution before revenue growth fully translates into lasting financial benefits.
Recent company updates have kept attention on construction progress, commissioning milestones, and the path toward stronger production from Terronera. For Endeavour Silver, those milestones matter more than broad industry headlines. A successful ramp-up could reshape output, unit costs, and cash generation much more than small moves in legacy operations.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


