Stock Analysis · Establishment Labs Holdings Inc (ESTA)
Overview
Establishment Labs Holdings Inc is a medical device company focused on aesthetic and reconstructive breast surgery. Its best-known product family is Motiva, a premium silicone breast implant platform sold outside the United States for many years and now increasingly tied to its U.S. expansion effort. The company also sells complementary products used before, during, and after surgery, and it is building a broader ecosystem around breast aesthetics, including minimally invasive and digital tools.
The business model is centered on selling devices to plastic surgeons, clinics, hospitals, and distributors across international markets. In recent filings, the company has emphasized its strategy of pairing premium implants with supporting technologies, training, and physician engagement rather than competing only on price.
Revenue is primarily generated from product sales. Based on recent company disclosures, the mix can be summarized as follows:
- Breast implants and tissue expanders: approximately 85% to 90% of revenue. This includes Motiva implants and related reconstructive products, which remain the core of the business.
- Aesthetics and procedure-related complementary products: approximately 10% to 15% of revenue. This includes items such as surgical support products and other tools used in breast procedures.
- Geographic mix: the large majority of revenue has historically come from markets outside the United States, with Latin America, Europe, the Middle East, and Asia playing important roles. The U.S. contribution is still in an earlier phase but has become strategically important following regulatory progress.
The financial flow over the last several years shows a business with solid gross profit generation but heavy operating expenses, especially selling and administrative costs. Revenue improved meaningfully in 2025, and losses narrowed, but the company still spends aggressively to support commercial expansion and market development.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Medical Devices | |
| Market Cap ⓘ | $1.72B | |
| Beta ⓘ | 1.06 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 24.79 |
| P/B Ratio ⓘ | 85.54 | 3.08 |
| FCF Yield ⓘ | -2.44% | 3.15% |
| Dividend Yield ⓘ | N/A | 1.94% |
| EBIT / EV ⓘ | -0.90% | 0.57% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 31.70% | 7.45% |
| RPS Growth (5Y CAGR) ⓘ | 7.76% | 8.61% |
| EPS Growth (5Y CAGR) ⓘ | -30.38% | -17.81% |
| BVPS Growth (5Y CAGR) ⓘ | -21.72% | 3.72% |
| Margin Growth (5Y Trend) ⓘ | N/A | -0.62% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 1.04% |
| DPS Growth (5Y CAGR) ⓘ | -39.50% | 6.77% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | -5.57% | 3.24% |
| ROA (Latest) ⓘ | -11.26% | 3.01% |
| ROIC (5Y Median) ⓘ | -21.02% | 4.60% |
| ROA (5Y Median) ⓘ | -27.80% | 1.89% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.34 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.84 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 1.00 |
| Net Debt / Assets ⓘ | 54.70% | 5.45% |
| EBITDA / Interest ⓘ | N/A | 9.64 |
| Operating Margin (Latest) ⓘ | -8.10% | 9.27% |
| Operating Margin (5Y Median) ⓘ | -37.76% | 7.38% |
| Debt to Equity (Latest) ⓘ | 1220.32% | 28.58% |
| Profit Margin (Latest) ⓘ | -15.82% | 3.59% |
| Free Cash Flow (Latest) ⓘ | -$42.06M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +56.17% | +42.80% |
| 12M Return (excl. last month) ⓘ | +94.03% | +18.50% |
| 6M Return ⓘ | -7.88% | +7.57% |
| Price vs. 200-Day MA ⓘ | -15.57% | +5.12% |
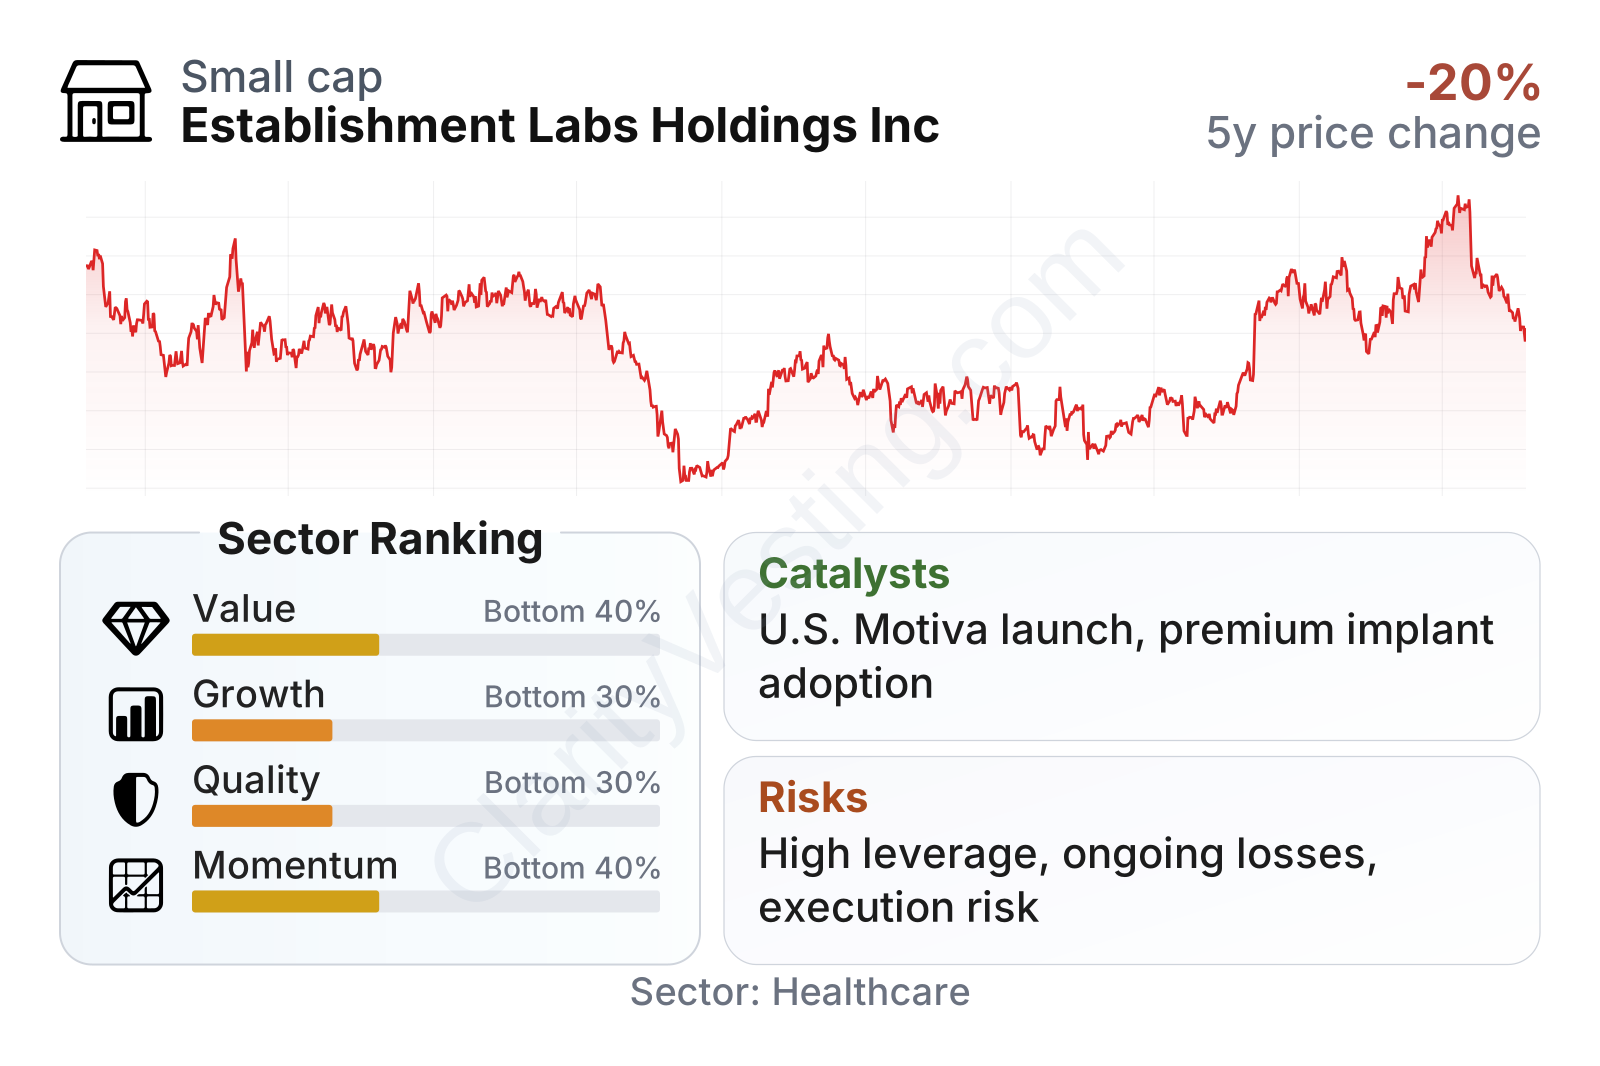
Establishment Labs is a mid-sized healthcare company with a share price history that has been highly volatile. The stock has rebounded strongly over the last year, but the longer pattern still reflects a business moving through uneven execution, regulatory milestones, and shifting market expectations.
The factor profile is mixed. Growth in recent revenue has clearly accelerated and sits well above the sector median, but quality and value metrics remain weak because profitability is still negative, free cash flow is still below zero, and leverage is unusually high. The market is assigning a very rich price-to-book multiple, which usually signals that investors are looking far beyond the current balance sheet and are instead pricing in future commercialization potential.
Growth
The company operates in a healthcare niche that benefits from several favorable long-term drivers: rising global demand for aesthetic procedures, expanding acceptance of premium implants, surgeon interest in differentiated products, and continued growth in reconstructive procedures. These trends do not make the industry immune to economic cycles, but they do support a larger addressable market over time.
Establishment Labs’ strategy is coherent for that backdrop. It is not simply trying to sell implants in as many countries as possible; it is trying to build a branded platform around premium breast aesthetics. That can matter because surgeons often value product consistency, clinical data, training, and patient positioning. If the company strengthens surgeon loyalty, pricing can become more resilient than in a commodity-like device business.
Recent revenue momentum is one of the strongest parts of the case. After a difficult period in 2023 and early 2024, growth reaccelerated sharply, with year-over-year gains moving back into clearly positive territory and then climbing into the 30% to 45% range in several recent periods. That is far above the healthcare sector median and suggests that commercial traction improved materially.
A major catalyst has been the company’s progress in the United States. Establishment Labs received FDA approval for Motiva SmoothSilk Round breast implants and related tissue expanders in 2024, opening the world’s largest profit pool in breast aesthetics. That approval matters not only because it adds a new market, but because success in the U.S. can also strengthen brand credibility globally. Management has since highlighted the U.S. launch, surgeon training, and initial commercial rollout as central priorities.
Another catalyst is the broader product pipeline built around the breast aesthetics ecosystem. The company has discussed Motiva Flora, a minimally invasive tissue expander, and Preservé, a less invasive breast augmentation approach, as part of its effort to expand beyond traditional implant sales. If these products gain adoption, they could increase revenue per procedure and deepen relationships with surgeons.
Cash generation is improving but remains an important watch point. Free cash flow is still negative, yet the trend has become less severe than in prior years. That suggests operating leverage may be starting to appear as sales rise, although the business has not yet reached a self-funding stage.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


