Stock Analysis · Element Solutions Inc (ESI)
Overview
Element Solutions Inc is a specialty chemicals company that sells high-value formulations and process technologies used in manufacturing. Rather than producing commodity chemicals, it focuses on products that help customers improve performance, reliability, and production efficiency in electronics, industrial equipment, and surface treatment applications. Its products are often embedded in customer processes, which can make relationships sticky once a formulation is qualified for use.
The business is organized around two main segments. Electronics is the larger one and serves semiconductor packaging and assembly, printed circuit boards, and other electronic hardware manufacturing. Industrial & Specialty serves surface treatment, graphics, and energy-related applications. Based on the company’s recent annual reporting, revenue is roughly distributed as follows:
- Electronics: about 60% to 65% of revenue. This includes chemistry and materials used in semiconductor and electronics manufacturing, such as assembly solutions and circuitry solutions.
- Industrial & Specialty: about 35% to 40% of revenue. This includes surface treatment products, graphic solutions, and energy-related chemistries used in industrial processes.
This mix matters because the Electronics segment is more closely tied to long-term themes like semiconductor complexity, advanced packaging, data infrastructure, and vehicle electrification, while Industrial & Specialty adds diversification across end markets.
The company’s profit structure has been somewhat uneven in recent years. Revenue has recovered after a softer 2023, and gross profit has remained relatively resilient, but operating income has moved around more sharply as expenses and mix shifted. That pattern suggests a business with good underlying product value, but not one that is fully insulated from cycles in industrial demand and electronics production.
The business has shown an ability to protect gross profit better than operating profit, which usually means pricing power and specialized products are real strengths, but overhead, acquisition integration, or changing end-market demand can still create earnings volatility.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Specialty Chemicals | |
| Market Cap ⓘ | $8.92B | |
| Beta ⓘ | 1.26 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 49.44 | 16.90 |
| P/B Ratio ⓘ | 3.13 | 1.65 |
| FCF Yield ⓘ | 1.48% | 5.76% |
| Dividend Yield ⓘ | 0.86% | 2.13% |
| EBIT / EV ⓘ | 2.05% | 6.30% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 56.40% | 11.10% |
| RPS Growth (5Y CAGR) ⓘ | 2.11% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | -11.82% | -13.47% |
| BVPS Growth (5Y CAGR) ⓘ | 2.54% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | -6.34% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | -5.02% | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | 6.48% | 6.08% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 6.27% | 9.26% |
| ROA (Latest) ⓘ | 3.30% | 4.91% |
| ROIC (5Y Median) ⓘ | 6.12% | 7.70% |
| ROA (5Y Median) ⓘ | 3.83% | 3.86% |
| Net Debt / EBIT (Latest) ⓘ | 8.90 | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | 5.26 | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | 5.08 | 0.95 |
| Net Debt / Assets ⓘ | 33.36% | 13.69% |
| EBITDA / Interest ⓘ | 5.30 | 12.34 |
| Operating Margin (Latest) ⓘ | 6.88% | 13.20% |
| Operating Margin (5Y Median) ⓘ | 12.98% | 11.80% |
| Debt to Equity (Latest) ⓘ | 75.35% | 40.56% |
| Profit Margin (Latest) ⓘ | 5.67% | 6.43% |
| Free Cash Flow (Latest) ⓘ | $131.60M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +95.64% | +68.89% |
| 12M Return (excl. last month) ⓘ | +23.24% | +30.21% |
| 6M Return ⓘ | -5.71% | -4.16% |
| Price vs. 200-Day MA ⓘ | -1.27% | -1.27% |
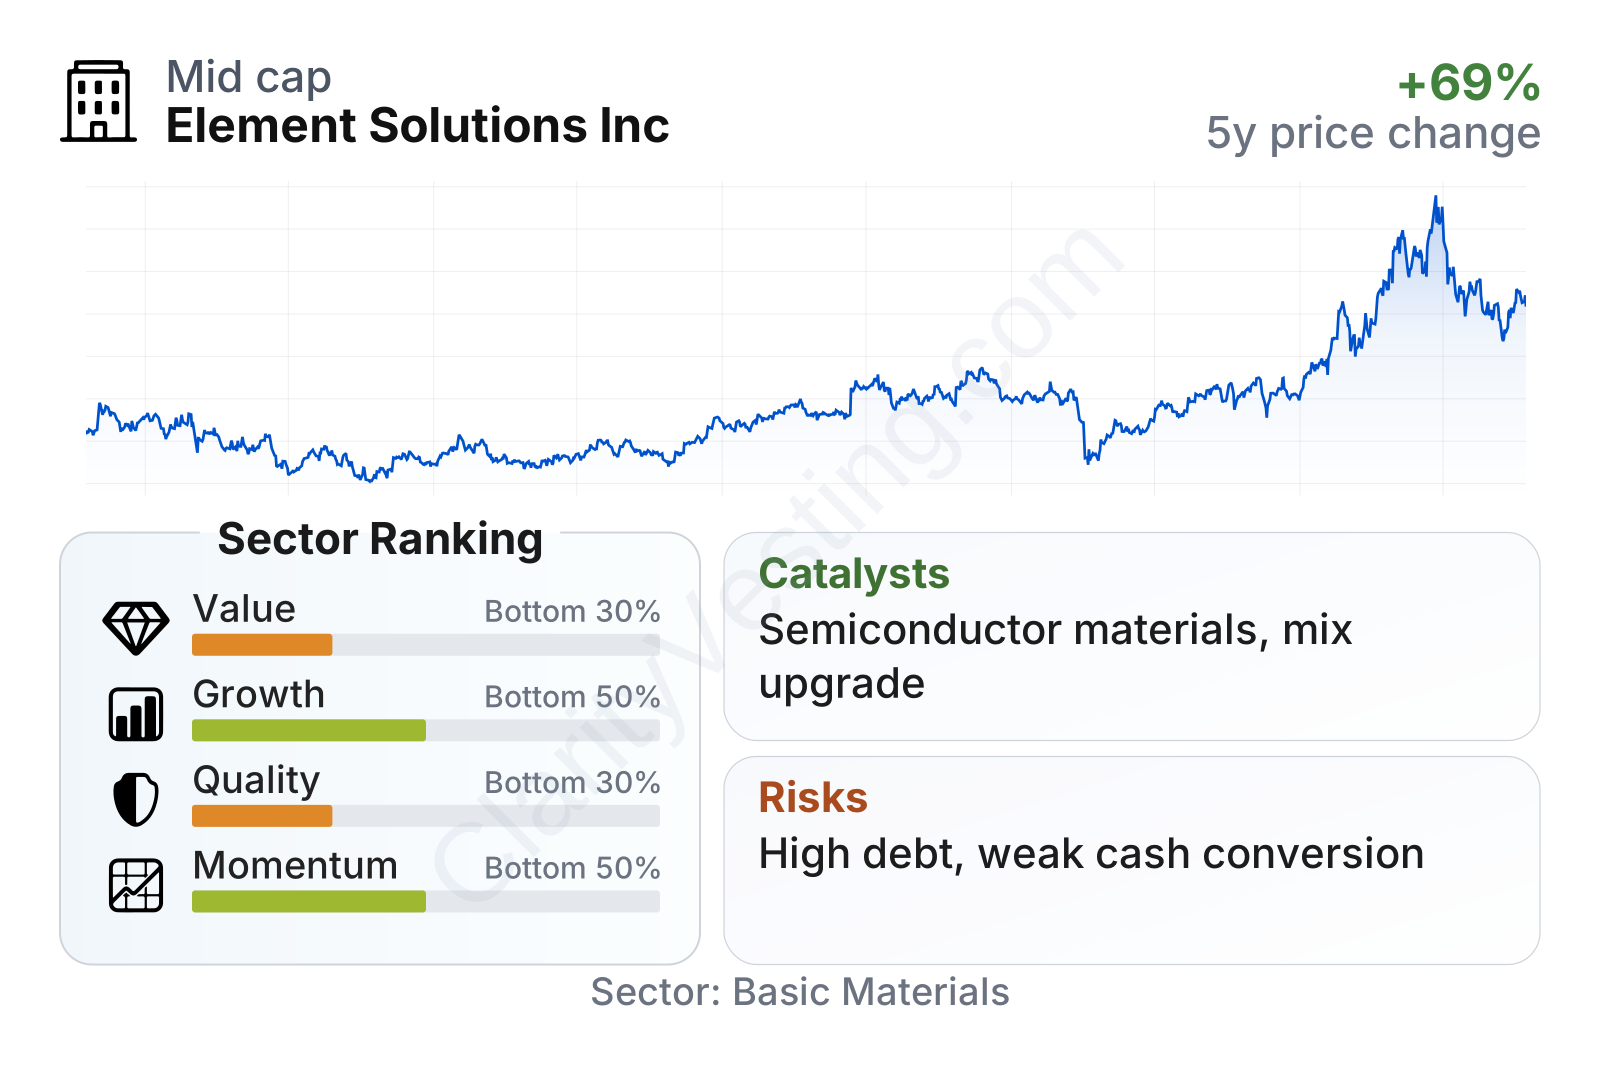
Element Solutions is a mid-to-large specialty chemicals company with a market value in the several-billion-dollar range. The stock has delivered a strong multiyear price advance, especially from 2024 into 2026, but the fundamental scorecard is less flattering than the share-price trajectory. Relative to the broader Basic Materials sector, current valuation metrics sit in the weaker part of the range, while quality and growth measures also rank below average overall. In simple terms, the market is assigning a richer price to a business whose profitability, balance-sheet strength, and cash generation do not currently stand out as best-in-class.
The main tension in the numbers is clear: the stock has been strong, but free cash flow yield is modest, earnings multiples are elevated, and leverage remains meaningfully above sector norms. That does not invalidate the business case, but it does raise the bar for future execution.
Growth
Element Solutions operates in areas that benefit from durable manufacturing trends. Electronics miniaturization, higher semiconductor content in cars and industrial equipment, artificial intelligence infrastructure, and more advanced chip packaging all tend to increase the need for specialized materials and process chemistry. In that sense, the company participates in a growing part of industrial technology rather than a stagnant chemicals niche.
Its strategy also makes industrial sense. The company focuses on formulations that become part of a customer’s qualified production process, which can create recurring demand and switching friction. In electronics manufacturing especially, once a material is approved for a specific use, customers are often reluctant to change unless there is a strong reason. That can support stable share and gradual pricing improvement over time.
Recent revenue growth has accelerated sharply after a flat-to-recovering period. That rebound stands out versus the sector and likely reflects a combination of easier comparisons, electronics recovery, and portfolio changes. The key question for long-term analysis is whether this is the beginning of a higher-growth phase or partly a temporary boost. The company’s longer-term growth record is more moderate than the latest year-over-year surge suggests, so consistency still needs to be demonstrated.
Cash generation is the main area where growth enthusiasm needs to be tempered. Free cash flow was materially stronger in earlier periods than it is now, which means recent top-line momentum has not flowed cleanly into cash. For a company with acquisition history and meaningful debt, that conversion matters a lot. Stronger sales are helpful, but over time the business needs to translate growth into sustained cash after capital spending and working capital needs.
A notable recent catalyst is the company’s push toward higher-value electronics exposure, including semiconductor and advanced packaging applications. If those categories keep expanding faster than traditional industrial activity, the company’s mix could improve. That would matter not just for revenue growth, but also for margin resilience and market perception.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


