Stock Analysis · EagleRock Land LLC (EROK)
Overview
EagleRock Land LLC operates in the energy industry, with activities tied to oil and gas equipment and services. Based on its public reporting profile and sector classification, the company appears to be connected to land, infrastructure, and service-related assets that support upstream energy activity rather than functioning as a large integrated oil producer. For long-term readers, the important point is that EagleRock Land is exposed to energy development spending, which can create meaningful upside when drilling and production activity are strong, but can also make results more cyclical than those of more diversified businesses.
The latest available financial mix suggests revenue is still concentrated in a relatively small number of operating streams, although the public detail available on exact segment breakdowns is limited. What stands out most is the very sharp increase in total revenue between 2024 and 2025, which indicates either a major expansion of activity, a change in business mix, or the scaling of a newer operating platform.
With limited segment disclosure available in the materials reviewed, the revenue picture can be summarized cautiously as follows:
- Core operating revenue: the large majority of sales appears to come from the company’s main energy-related land and service activities.
- Other ancillary revenue sources: any remaining contribution likely comes from related operational or contractual activities, but a reliable percentage split is not clearly disclosed in the public materials reviewed.
The broad financial flow shows a business that expanded dramatically in 2025: revenue rose from about $18 million in 2024 to about $141 million in 2025. Gross profit also increased strongly, but operating expenses grew almost as quickly, which left only a modest operating profit and a very thin net income margin. That pattern points to scale, but not yet to consistently strong efficiency.
The visual summary highlights the company’s biggest recent shift: far higher sales were accompanied by a major jump in operating costs, especially overhead and administrative spending. Interest expense fell sharply year over year, which helped earnings, but the business still converted only a small portion of revenue into net profit.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Energy | |
| Industry | Oil & Gas Equipment & Services | |
| Market Cap ⓘ | $2.69B | |
| Beta ⓘ | N/A | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 7.90 | 15.44 |
| P/B Ratio ⓘ | 1.74 | 1.73 |
| FCF Yield ⓘ | 0.32% | 8.20% |
| Dividend Yield ⓘ | N/A | 3.59% |
| EBIT / EV ⓘ | -16.57% | 7.46% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 74.00% | 26.90% |
| RPS Growth (5Y CAGR) ⓘ | N/A | 6.90% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -15.73% |
| BVPS Growth (5Y CAGR) ⓘ | N/A | 6.07% |
| Margin Growth (5Y Trend) ⓘ | N/A | 0.58% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 1.86% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 16.79% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 11.40% |
| ROA (Latest) ⓘ | N/A | 6.06% |
| ROIC (5Y Median) ⓘ | N/A | 10.30% |
| ROA (5Y Median) ⓘ | N/A | 5.42% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.64 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.83 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 1.08 |
| Net Debt / Assets ⓘ | -3.36% | 17.29% |
| EBITDA / Interest ⓘ | N/A | 9.64 |
| Operating Margin (Latest) ⓘ | -90.57% | 16.27% |
| Operating Margin (5Y Median) ⓘ | N/A | 20.39% |
| Debt to Equity (Latest) ⓘ | 0.45% | 54.76% |
| Profit Margin (Latest) ⓘ | -2.93% | 8.82% |
| Free Cash Flow (Latest) ⓘ | $8.65M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | N/A | +67.38% |
| 12M Return (excl. last month) ⓘ | N/A | +49.19% |
| 6M Return ⓘ | N/A | +7.07% |
| Price vs. 200-Day MA ⓘ | N/A | +9.56% |
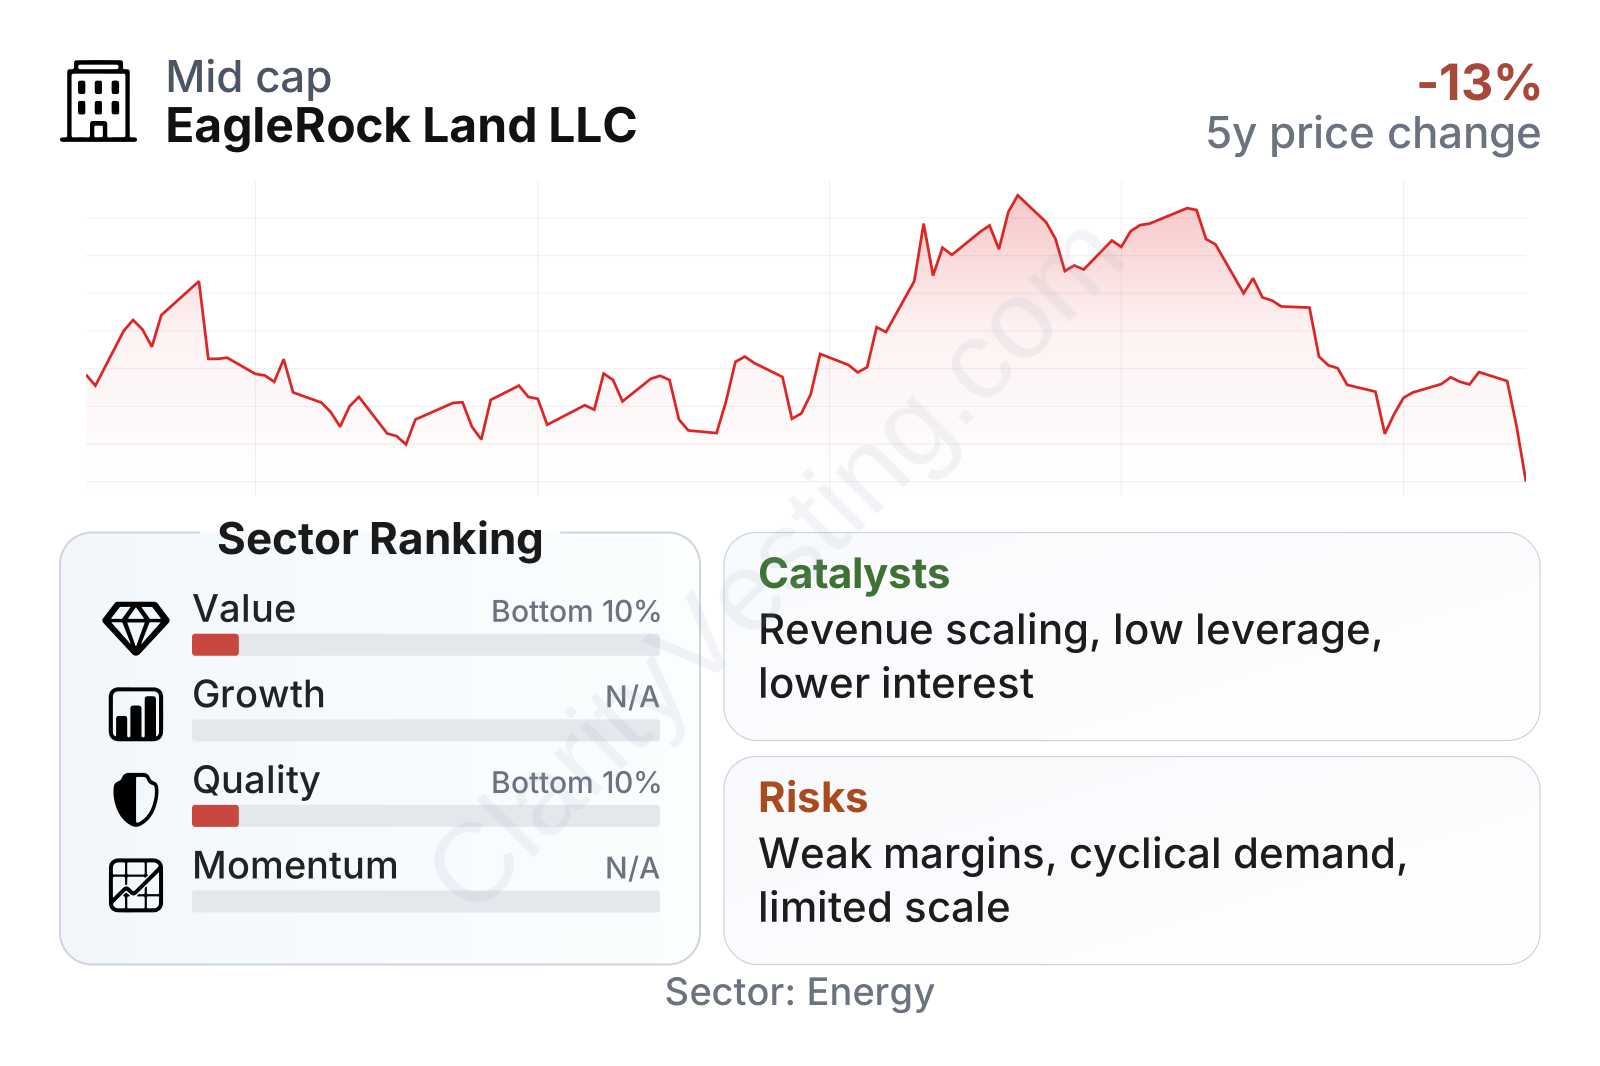
The market currently values EagleRock Land as a mid-sized small-cap energy company. The stock has moved higher in recent months, which suggests improving sentiment, likely linked to its rapid revenue expansion. On valuation, the headline P/E ratio looks low compared with the sector median, but that needs to be read carefully because profitability remains weak and free cash flow yield is far below typical industry levels.
The table also shows an unusual combination of traits. Growth is very strong on a recent year-over-year basis, with revenue rising far faster than the sector median. At the same time, quality metrics are weak: margins are negative or far below peers on a trailing basis, and the company ranks near the bottom of the sector on several profitability measures. One clear strength is balance sheet conservatism. Debt-to-equity is close to zero, and net debt relative to assets is actually negative, which indicates cash exceeds debt.
Growth
EagleRock Land operates in a part of the energy economy that can benefit from long-duration demand for oilfield development, land access, infrastructure support, and related services. This is not a structurally disappearing market. Even with the long-term rise of renewables, North American oil and gas production still requires land coordination, field services, and operating support. That creates room for niche operators that can secure strong local positions or specialized capabilities.
The strongest growth signal is the company’s recent revenue trajectory. A year-over-year increase of roughly 74% materially exceeds the sector median. That kind of expansion usually means the company is either winning more business, broadening its footprint, or benefiting from an important step-change in operations. If that higher revenue base proves sustainable, future results could improve meaningfully because the balance sheet does not appear heavily burdened by debt.
Another positive element is the drop in interest expense from 2024 to 2025. Lower financing costs can make future earnings more resilient, especially for a business that is still trying to translate scale into stronger bottom-line performance. The company’s low leverage also gives it more flexibility than many peers if it wants to invest in growth, acquire assets, or absorb periods of industry volatility.
At the sector level, one possible catalyst is continued strength in U.S. energy production and related field activity. If operators remain active and capital spending stays healthy, demand for land-linked services and infrastructure support can remain firm. For EagleRock Land specifically, the key opportunity is not only growing revenue, but improving cost discipline so that more of that revenue reaches operating income and free cash flow.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


