Stock Analysis · ERAMET S.A (ERMAF)
Overview
ERAMET S.A. is a French mining and metals group active in manganese, mineral sands, and nickel, with additional exposure to lithium development. In simple terms, the company extracts and processes raw materials that are used in steelmaking, alloys, aerospace, pigments, electronics, and batteries. Its business is tied closely to global industrial demand and to commodity prices, which makes results more cyclical than those of many ordinary industrial companies.
The company’s revenue base is diversified across a few large mining activities, although manganese remains the core earnings driver in most years. Based on recent annual disclosures, the business mix is approximately as follows:
- Manganese: about 55% to 65% of revenue. This includes manganese ore mining and manganese alloys, mainly used in carbon steel production.
- Mineral sands: about 20% to 30% of revenue. This activity includes ilmenite, zircon, rutile, and related products used in pigments, ceramics, foundry applications, and specialty industrial markets.
- Nickel: about 10% to 20% of revenue. This mainly reflects ferronickel operations in New Caledonia, a business that has faced persistent profitability pressure.
- Other activities: generally below 10%. This includes smaller operations, development projects, and corporate items, notably lithium projects that are more important strategically than they are in current revenue.
What matters for a long-term view is that ERAMET is not a pure battery materials company yet, even if that theme often attracts attention. Today, its economics still depend mainly on established bulk materials, especially manganese. The longer-term case is therefore a mix of mature mining cash generation and the possibility of future growth from energy-transition materials.
The multi-year profit flow shows a sharp swing from exceptionally strong conditions in 2022 to much weaker profitability by 2025. Revenue has trended down from the peak, while operating profit and net income compressed much faster, highlighting how sensitive the group is to commodity prices, costs, and financing pressure.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Other Industrial Metals & Mining | |
| Market Cap ⓘ | $1.22B | |
| Beta ⓘ | 0.95 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 16.90 |
| P/B Ratio ⓘ | 3.40 | 1.65 |
| FCF Yield ⓘ | -96.40% | 5.76% |
| Dividend Yield ⓘ | N/A | 2.13% |
| EBIT / EV ⓘ | N/A | 6.30% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 15.70% | 11.10% |
| RPS Growth (5Y CAGR) ⓘ | -7.13% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | -47.28% | -13.47% |
| BVPS Growth (5Y CAGR) ⓘ | -8.16% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | -28.81% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | 81.20% | 6.08% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 4.65% | 9.26% |
| ROA (Latest) ⓘ | -9.53% | 4.91% |
| ROIC (5Y Median) ⓘ | 9.95% | 7.70% |
| ROA (5Y Median) ⓘ | 1.61% | 3.86% |
| Net Debt / EBIT (Latest) ⓘ | 9.78 | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | 1.48 | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | 2.27 | 0.95 |
| Net Debt / Assets ⓘ | 29.17% | 13.69% |
| EBITDA / Interest ⓘ | 2.00 | 12.34 |
| Operating Margin (Latest) ⓘ | 3.38% | 13.20% |
| Operating Margin (5Y Median) ⓘ | 7.88% | 11.80% |
| Debt to Equity (Latest) ⓘ | 707.26% | 40.56% |
| Profit Margin (Latest) ⓘ | -17.30% | 6.43% |
| Free Cash Flow (Latest) ⓘ | -$1.18B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | -38.06% | +68.89% |
| 12M Return (excl. last month) ⓘ | -11.31% | +30.21% |
| 6M Return ⓘ | -22.99% | -4.16% |
| Price vs. 200-Day MA ⓘ | -25.71% | -1.27% |
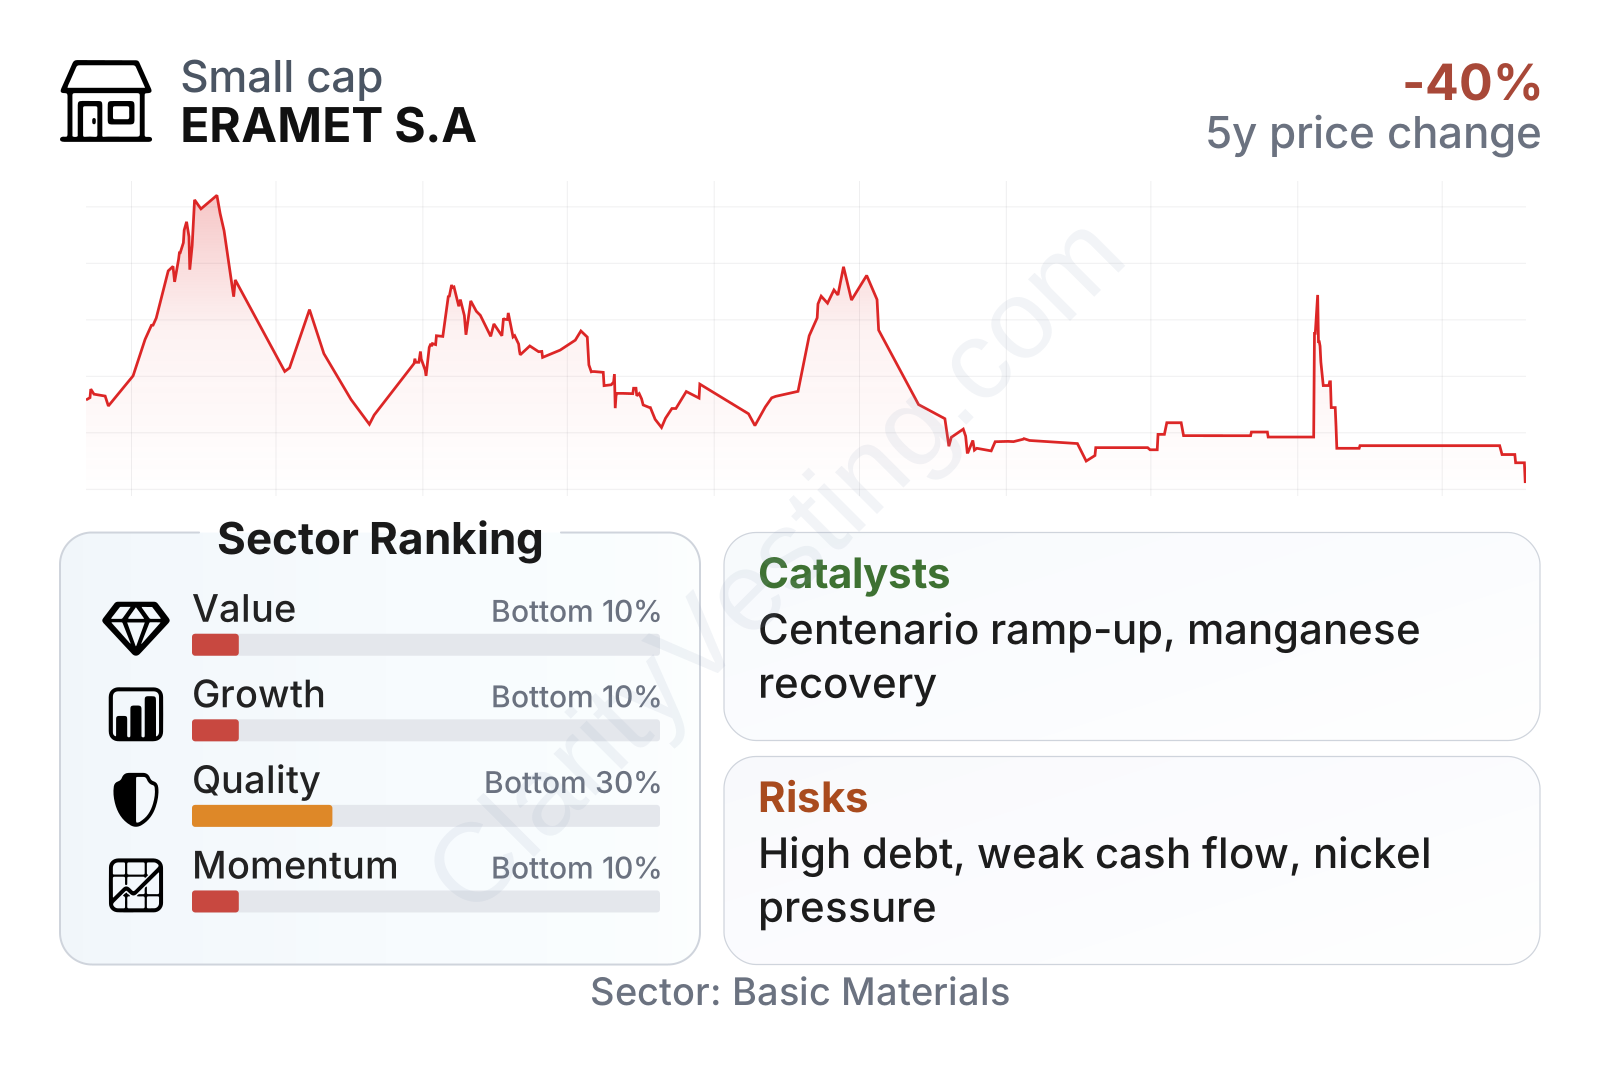
ERAMET currently sits in the lower end of its sector on value, growth, quality, and momentum measures. Recent revenue growth was positive at roughly 16%, which shows the business can still rebound in shorter periods, but the longer record is much less favorable: five-year revenue per share, earnings, book value per share, and margin trends are all weak versus the sector median.
Balance-sheet pressure is one of the clearest points in the table. Net debt relative to EBITDA is above 3x, debt to equity is very high, and interest coverage is thin at around 1.5x. Profitability is also under strain, with operating margin near break-even and net margin clearly negative over the latest trailing period. Free cash flow is deeply negative, which helps explain why the market is not giving the company a strong valuation profile despite its mid-sized market capitalization and beta close to 1.
The stock-price history also reflects this backdrop. After trading above 100 in 2023, the shares reset sharply and have since moved in a much lower range around the mid-50s. That pattern is consistent with a business that moved from a commodity upcycle into a period of weaker sentiment and lower earnings visibility.
Growth
ERAMET operates in sectors that can offer long-term demand support, but the growth picture is uneven depending on the commodity. Manganese has a stable structural role because it remains essential for steel production. Mineral sands demand is supported by broad industrial uses rather than one single trend. The most interesting long-term growth angle is lithium, where battery demand from electric vehicles and energy storage can create a much larger future market than the company’s legacy businesses.
The company’s strategy broadly makes industrial sense: keep extracting value from established mining assets while building exposure to materials linked to electrification. That is especially relevant because ERAMET already has operational know-how in large-scale mining, logistics, and processing. If management can convert this experience into profitable lithium production, the group could become more visible in faster-growing end markets instead of relying so heavily on older and more cyclical products.
A key catalyst is the development ramp-up of the Centenario lithium project in Argentina, which has been one of the company’s most important strategic initiatives. If commissioning and production targets are met, this could gradually change how the market views ERAMET by adding a cleaner growth leg to the portfolio. Another possible support is any recovery in manganese prices or alloy demand, because even moderate commodity improvement can have a strong effect on earnings in mining companies.
There is also a geopolitical and industrial-policy angle that may help over time. Europe has been trying to strengthen access to strategic raw materials, and ERAMET is one of the few European-rooted groups with meaningful mining capabilities in several minerals. That does not remove execution risk, but it can improve the company’s strategic relevance in supply-chain discussions.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


