Stock Analysis · Equinox Gold Corp (EQX)
Overview
Equinox Gold Corp is a gold mining company. It explores for gold deposits, develops new mines, and operates producing mines, mainly in the Americas. In simple terms, the business model is straightforward: the company spends capital to find and build mines, extracts ore, processes it into gold, and sells that gold into the market. Its results therefore depend mostly on how much gold it produces, what it costs to produce it, and the market price of gold.
The company’s revenue comes overwhelmingly from gold sales. Based on recent annual reporting, the business is still largely a single-commodity company, with only limited contribution from other metals or by-products where applicable.
- Gold sales: approximately 95% to 100% of total revenue. This includes ounces sold from the company’s operating mines and is the core economic driver of the group.
- Silver and other by-product revenue: approximately 0% to 5% of total revenue when present. These amounts can come from metals produced alongside gold at certain sites, but they are not the main focus of the business.
Geographically, revenue is also diversified by mine rather than by a broad range of end-markets. That offers some operating spread across jurisdictions, but it does not reduce exposure to gold prices. Over the last few years, the income profile has also become larger in scale as new assets were added and production ramped up, although results have been uneven from year to year because mining is operationally volatile and heavily influenced by one-time accounting items, taxes, and project timing.
The most important high-level point is that Equinox Gold is not a diversified materials group. It is primarily a gold producer with a portfolio of mines and development projects. That gives it direct exposure to a strong gold market, but it also means company performance can swing sharply when a mine underperforms or construction costs rise.
The business has grown meaningfully in revenue since 2022, and profitability improved sharply after a weak period. The main visible trend is that sales expanded faster than overhead, while margins recovered from the losses seen in 2022. At the same time, interest expense also became heavier, which matters because new mine construction and acquisitions can make growth more expensive.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Gold | |
| Market Cap ⓘ | $13.31B | |
| Beta ⓘ | 2.49 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 17.54 | 17.61 |
| P/B Ratio ⓘ | 1.45 | 1.77 |
| FCF Yield ⓘ | 0.46% | 5.87% |
| Dividend Yield ⓘ | 0.27% | 2.06% |
| EBIT / EV ⓘ | 6.34% | 6.43% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 169.30% | 11.30% |
| RPS Growth (5Y CAGR) ⓘ | -2.48% | 4.46% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -13.11% |
| BVPS Growth (5Y CAGR) ⓘ | 4.33% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | -36.18% | -1.57% |
| FCF Growth (5Y CAGR) ⓘ | -26.90% | 0.55% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.02% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 6.33% | 9.31% |
| ROA (Latest) ⓘ | 8.14% | 4.94% |
| ROIC (5Y Median) ⓘ | 4.48% | 7.91% |
| ROA (5Y Median) ⓘ | 2.62% | 3.93% |
| Net Debt / EBIT (Latest) ⓘ | 0.29 | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | 2.62 | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | 0.18 | 0.91 |
| Net Debt / Assets ⓘ | 2.71% | 13.69% |
| EBITDA / Interest ⓘ | 11.17 | 11.93 |
| Operating Margin (Latest) ⓘ | 34.97% | 13.07% |
| Operating Margin (5Y Median) ⓘ | 17.10% | 11.86% |
| Debt to Equity (Latest) ⓘ | 9.15% | 40.43% |
| Profit Margin (Latest) ⓘ | 28.09% | 6.57% |
| Free Cash Flow (Latest) ⓘ | $61.01M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +163.73% | +65.06% |
| 12M Return (excl. last month) ⓘ | +47.41% | +36.05% |
| 6M Return ⓘ | -22.92% | +1.89% |
| Price vs. 200-Day MA ⓘ | -15.31% | +1.03% |
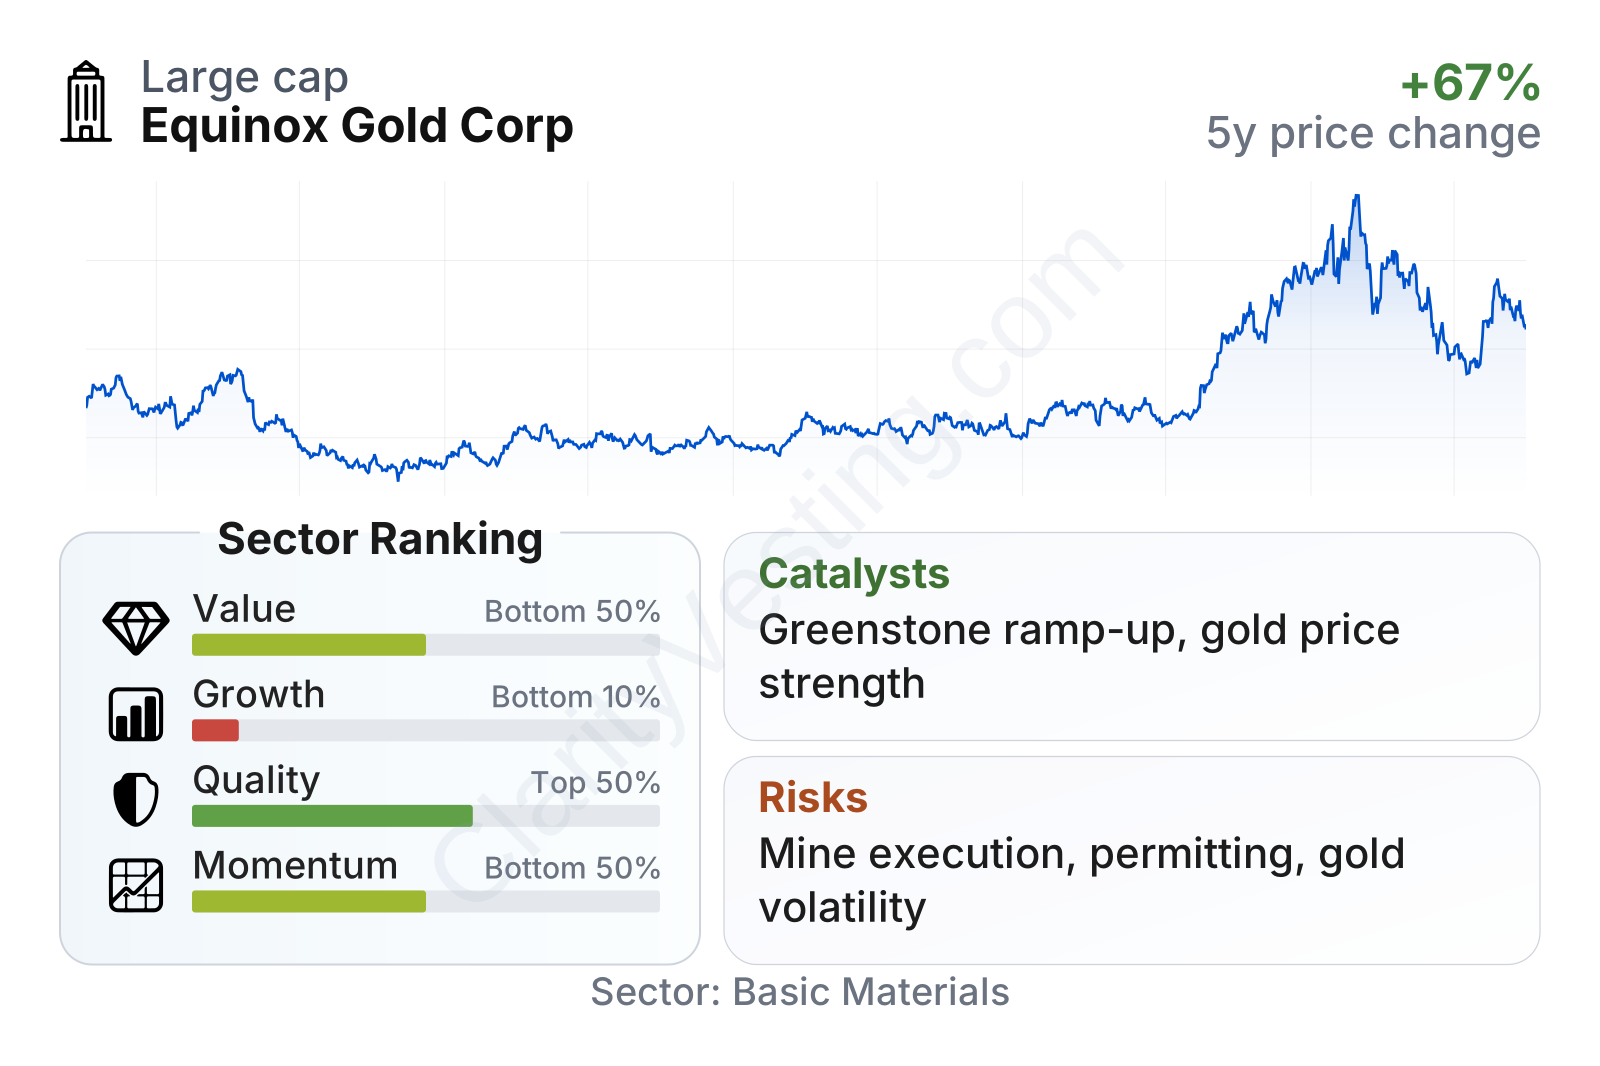
Equinox Gold sits in the larger end of the gold-mining space and has a high share-price volatility profile, as shown by its elevated beta. The valuation picture looks mixed rather than obviously cheap: earnings and asset-based multiples are close to or slightly below sector norms, but cash flow yield is still weak. Quality is better than many peers on current profitability and balance-sheet leverage, while growth metrics are dragged down by a weak five-year record despite very strong recent revenue expansion. Momentum has cooled after a powerful multi-year share-price rise, which fits a stock that has already rerated on stronger gold conditions and improving operations.
Growth
Gold mining is part of a sector with long-term support from central-bank buying, demand for portfolio hedges during periods of inflation or geopolitical stress, and limited large-scale new supply. That does not make it a steady growth industry in the way software or semiconductors can be, but it does mean well-positioned producers can benefit significantly when gold prices stay high and new mines come online at the right time.
Equinox Gold’s strategy is built around scale and pipeline depth. It combines producing mines with development assets, which can increase output over time without relying entirely on acquisitions. That approach makes strategic sense if management can bring projects into production close to budget and schedule. For a miner, the strongest catalyst is often not a marketing initiative or a product launch, but a mine reaching commercial production, improving recoveries, or extending mine life through new reserves.
Recent revenue growth has been exceptionally strong relative to most of the sector. That kind of acceleration usually reflects a mix of higher gold prices, stronger production, and portfolio changes. However, the longer-term growth picture is less clean because per-share growth over five years has been weak, meaning expansion has not translated into a consistently better result for each share outstanding.
Free cash flow is an important checkpoint for miners because accounting profits can look healthy while construction spending absorbs the cash. Here, the direction has improved: free cash flow moved from deeply negative territory to positive territory more recently. That is encouraging because it suggests the company may be moving from a heavy investment phase toward a period where projects start contributing cash rather than consuming it.
A major growth catalyst for Equinox Gold is its project pipeline, especially large development assets that could materially lift annual output once completed. The company has also highlighted production growth targets and portfolio optimization in its public materials. In a strong gold-price environment, even moderate operating improvements can have an outsized impact on earnings and cash flow because much of the cost base is fixed once a mine is running.
Another relevant recent development is the company’s reintroduction of a dividend, albeit at a very small level. On its own, that does not transform the investment case, but it can signal management confidence that the balance sheet and operating base are stabilizing after a more capital-intensive stretch.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


