Stock Analysis · Enersys (ENS)
Overview
EnerSys is a manufacturer of industrial energy storage and power systems. In simple terms, it makes batteries and related equipment that help businesses keep equipment moving, telecommunications networks running, and critical facilities powered when the main electricity supply is interrupted. Its products are used in forklifts and warehouse equipment, data centers, telecom towers, utilities, aerospace and defense applications, and other industrial settings where reliability matters.
The company reports its business through three main segments. Based on its latest fiscal year filings for the year ended March 31, 2026, revenue is spread across these activities in a fairly balanced way, with motive power still the largest contributor.
- Motive Power – about 40%: batteries, chargers, power management equipment, and related services used mainly in electric forklifts, automated guided vehicles, and warehouse fleets.
- Energy Systems – about 33%: reserve power systems, chargers, cabinets, enclosures, and integrated solutions for telecom, broadband, utilities, and data center backup applications.
- Specialty – about 27%: batteries and power solutions for aerospace, defense, rail, and other specialized industrial uses where performance and durability are critical.
Geographically, EnerSys is broadly diversified, with meaningful exposure to the Americas, Europe, and Asia. That helps reduce dependence on any one end market, although industrial demand cycles still have a strong influence on results. Over the last several years, the business has also become more profitable, with higher gross profit and operating income even while revenue growth has remained moderate. That suggests pricing discipline, operational improvements, and a richer product mix have mattered as much as pure volume growth.
The business mix shows a company that is not driven by one single niche. Revenue has climbed gradually over time, while profitability improved more sharply than sales, indicating that recent performance has come from better execution as well as demand support.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Electrical Equipment & Parts | |
| Market Cap ⓘ | $6.15B | |
| Beta ⓘ | 1.19 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 18.27 | 22.29 |
| P/B Ratio ⓘ | 3.39 | 1.98 |
| FCF Yield ⓘ | 11.66% | 6.26% |
| Dividend Yield ⓘ | 0.62% | 1.92% |
| EBIT / EV ⓘ | 6.68% | 4.83% |
| PEG ⓘ | 0.95 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 4.80% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | 5.81% | 7.76% |
| EPS Growth (5Y CAGR) ⓘ | -10.27% | -13.17% |
| BVPS Growth (5Y CAGR) ⓘ | 9.47% | 6.13% |
| Margin Growth (5Y Trend) ⓘ | 4.30% | 0.74% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 10.79% |
| DPS Growth (5Y CAGR) ⓘ | 9.88% | 9.41% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 12.97% | 10.75% |
| ROA (Latest) ⓘ | 8.78% | 5.41% |
| ROIC (5Y Median) ⓘ | 11.13% | 9.37% |
| ROA (5Y Median) ⓘ | 7.36% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | 1.09 | 2.04 |
| Net Debt / EBIT (5Y Median) ⓘ | 1.89 | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | 0.87 | 1.39 |
| Net Debt / Assets ⓘ | 12.85% | 19.27% |
| EBITDA / Interest ⓘ | 11.09 | 9.58 |
| Operating Margin (Latest) ⓘ | 12.30% | 10.49% |
| Operating Margin (5Y Median) ⓘ | 9.55% | 10.30% |
| Debt to Equity (Latest) ⓘ | 52.74% | 64.82% |
| Profit Margin (Latest) ⓘ | 9.29% | 6.67% |
| Free Cash Flow (Latest) ⓘ | $717.31M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +103.82% | +67.77% |
| 12M Return (excl. last month) ⓘ | +63.37% | +12.05% |
| 6M Return ⓘ | -10.72% | 0.00% |
| Price vs. 200-Day MA ⓘ | -7.42% | +0.67% |
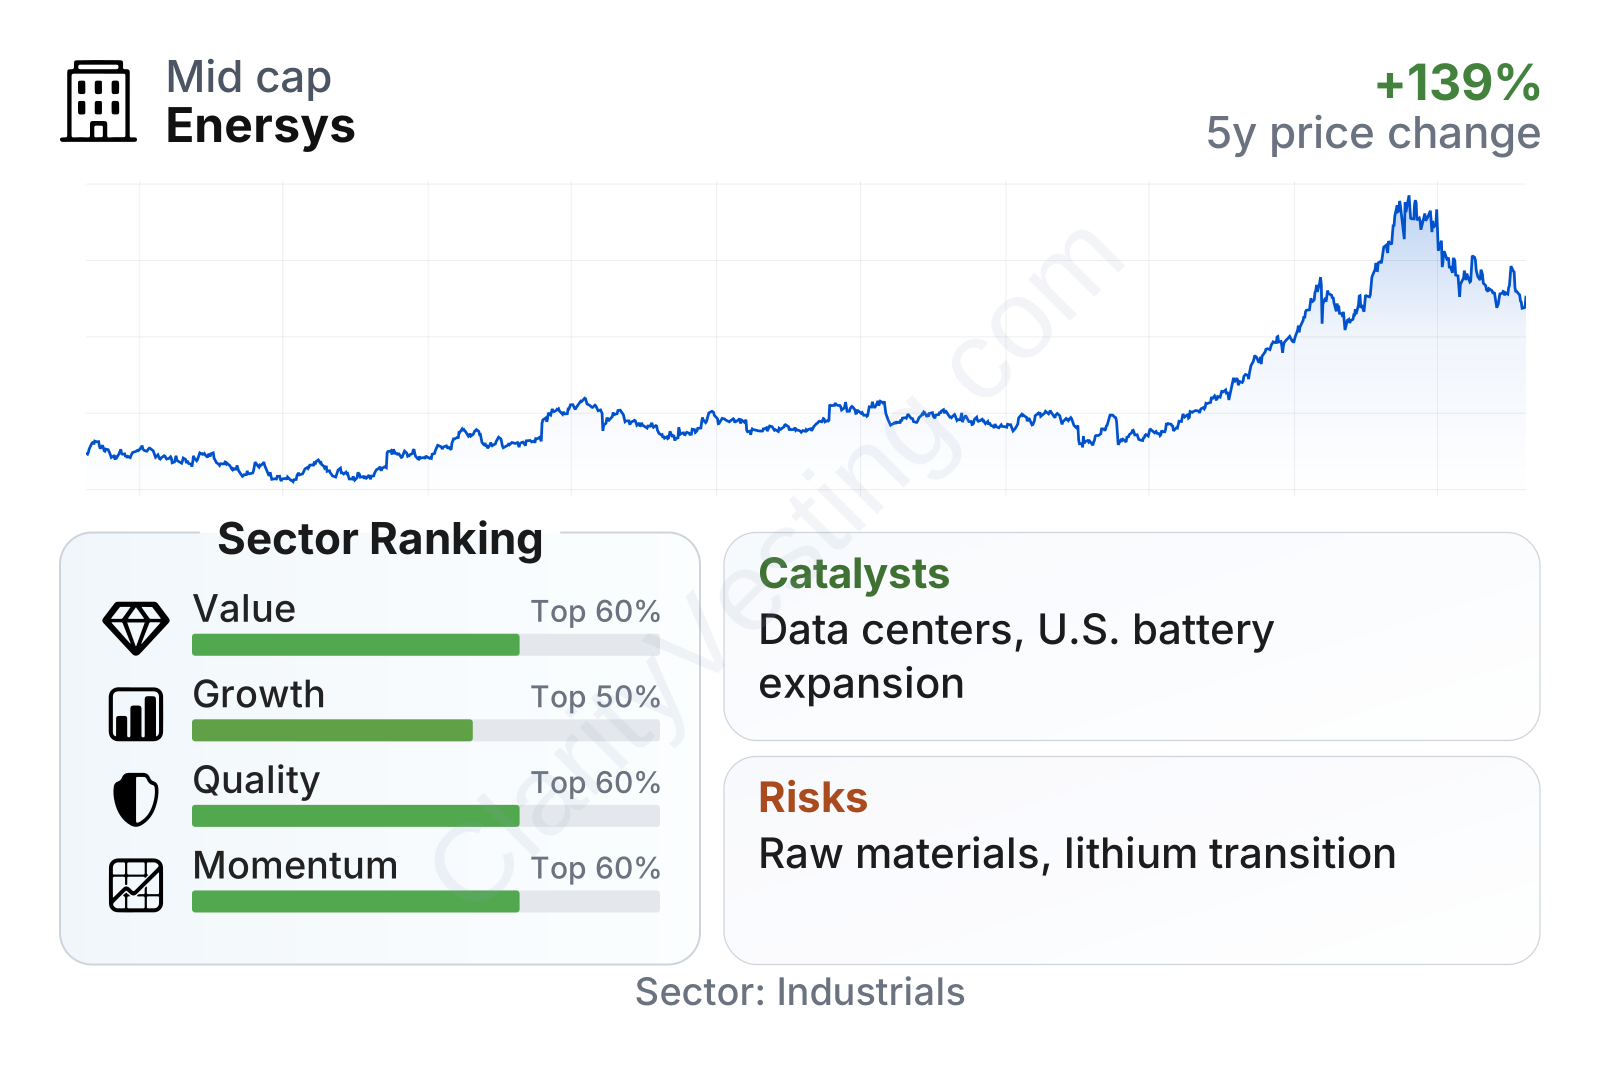
EnerSys is a mid-sized industrial company with a stock that has been volatile but strong over the last three years. The recent market performance has been well ahead of the sector, although the shares have moved in large swings. On fundamentals, the profile is mixed in a constructive way: growth is not exceptional, but profitability, returns on capital, and cash generation look solid. Relative to the broader industrial sector, the company stands out more for efficiency and cash flow than for rapid top-line expansion.
Growth
EnerSys operates in parts of the market that have favorable long-term demand drivers. Warehouses are becoming more automated, logistics fleets are increasingly electrified, telecom and broadband infrastructure still needs resilient backup power, and data center power systems are becoming more important as digital infrastructure expands. These are not short-lived themes, and they fit directly with the company’s core capabilities in industrial batteries, chargers, and integrated power systems.
The strategy also makes sense. EnerSys is not only selling batteries; it has been pushing further into higher-value systems, software-enabled fleet management, charging solutions, and maintenance services. That approach can deepen customer relationships and reduce the risk of being treated as a simple commodity supplier. In motive power especially, the ability to provide a broader package around battery performance, charging, monitoring, and service can improve customer retention.
Revenue growth has not been smooth. After a strong period in 2022 and early 2023, sales growth turned negative for several quarters before recovering back into positive territory. The recent pattern points to a company emerging from a softer patch rather than one delivering uninterrupted expansion. The latest yearly growth rate is still below the sector median, so the growth case rests more on steady execution and end-market positioning than on breakout sales momentum.
Cash flow is one of the more encouraging parts of the picture. Free cash flow moved from negative territory several years ago to a much stronger level more recently, even if the path has been uneven. That matters because industrial businesses often need capital for working capital, factories, and inventory. Stronger cash generation gives EnerSys more flexibility for debt reduction, acquisitions, buybacks, and internal investment.
A notable catalyst is the company’s push into U.S. battery manufacturing and energy storage expansion supported by federal incentives and domestic supply chain priorities. EnerSys has also highlighted data center demand, broadband infrastructure, and defense-related applications as areas of opportunity. These are attractive because they often require high reliability and can support better margins than more standardized battery markets.
Recent company updates have also pointed to continued interest in lithium, fast charging, and integrated power solutions. Even though lead-acid remains important today, the broader direction of industrial electrification gives EnerSys room to participate in both established and newer chemistries rather than relying on one technology alone.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


