Stock Analysis · EMS-CHEMIE HOLDING AG (EMSHF)
Overview
EMS-CHEMIE HOLDING AG is a Swiss specialty chemicals company focused on high-performance polymers and specialty chemicals. In practice, it develops and manufactures engineered materials that help customers make products lighter, stronger, more heat-resistant, and easier to manufacture. Its materials are used in demanding applications such as automotive components, electrical and electronics parts, consumer goods, industrial equipment, and specialty packaging.
The group is organized around two main business areas, with the large majority of revenue coming from the higher-value polymer business.
- High Performance Polymers: approximately 85% to 90% of revenue in recent years. This division includes polyamide specialties, high-temperature plastics, compounds, and application engineering services. It is the core earnings engine of the company and is especially exposed to automotive lightweighting, metal replacement, and more complex technical parts.
- Specialty Chemicals: approximately 10% to 15% of revenue. This segment includes products such as performance chemicals, fibers, adhesives-related intermediates, and other niche chemical solutions used in industrial and consumer applications.
Geographically, EMS-CHEMIE sells globally, with Europe and Asia typically representing the largest markets, followed by the Americas. A key feature of the business model is that the company does not compete mainly on commodity volume. Instead, it focuses on custom formulations, close technical cooperation with customers, and applications where material performance matters more than raw material cost alone.
Looking at the business flow over the last several years, revenue peaked in 2022 and has since softened, but profitability stayed unusually strong. That suggests the company has been able to protect margins through pricing discipline, product mix, and operational efficiency rather than chasing volume at any cost.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Specialty Chemicals | |
| Market Cap ⓘ | $18.16B | |
| Beta ⓘ | 0.76 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 30.39 | 16.92 |
| P/B Ratio ⓘ | 11.28 | 1.66 |
| FCF Yield ⓘ | 5.47% | 5.83% |
| Dividend Yield ⓘ | 1.89% | 2.07% |
| EBIT / EV ⓘ | N/A | 6.38% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | -0.90% | 11.25% |
| RPS Growth (5Y CAGR) ⓘ | -3.54% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | -31.56% | -15.24% |
| BVPS Growth (5Y CAGR) ⓘ | 0.73% | 5.49% |
| Margin Growth (5Y Trend) ⓘ | -0.13% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | 3.82% | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | 0.38% | 5.91% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 47.94% | 9.59% |
| ROA (Latest) ⓘ | 38.97% | 4.92% |
| ROIC (5Y Median) ⓘ | 27.80% | 7.91% |
| ROA (5Y Median) ⓘ | 20.98% | 3.92% |
| Net Debt / EBIT (Latest) ⓘ | -0.66 | 1.36 |
| Net Debt / EBIT (5Y Median) ⓘ | -0.66 | 1.69 |
| Net Debt / EBITDA (Latest) ⓘ | -0.60 | 0.93 |
| Net Debt / Assets ⓘ | -29.02% | 13.69% |
| EBITDA / Interest ⓘ | 257.65 | 12.38 |
| Operating Margin (Latest) ⓘ | 28.74% | 13.24% |
| Operating Margin (5Y Median) ⓘ | 26.57% | 11.82% |
| Debt to Equity (Latest) ⓘ | 1.52% | 40.30% |
| Profit Margin (Latest) ⓘ | 24.45% | 6.38% |
| Free Cash Flow (Latest) ⓘ | $993.78M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +63.83% | +73.47% |
| 12M Return (excl. last month) ⓘ | +35.88% | +27.59% |
| 6M Return ⓘ | +26.45% | -4.02% |
| Price vs. 200-Day MA ⓘ | N/A | -0.65% |
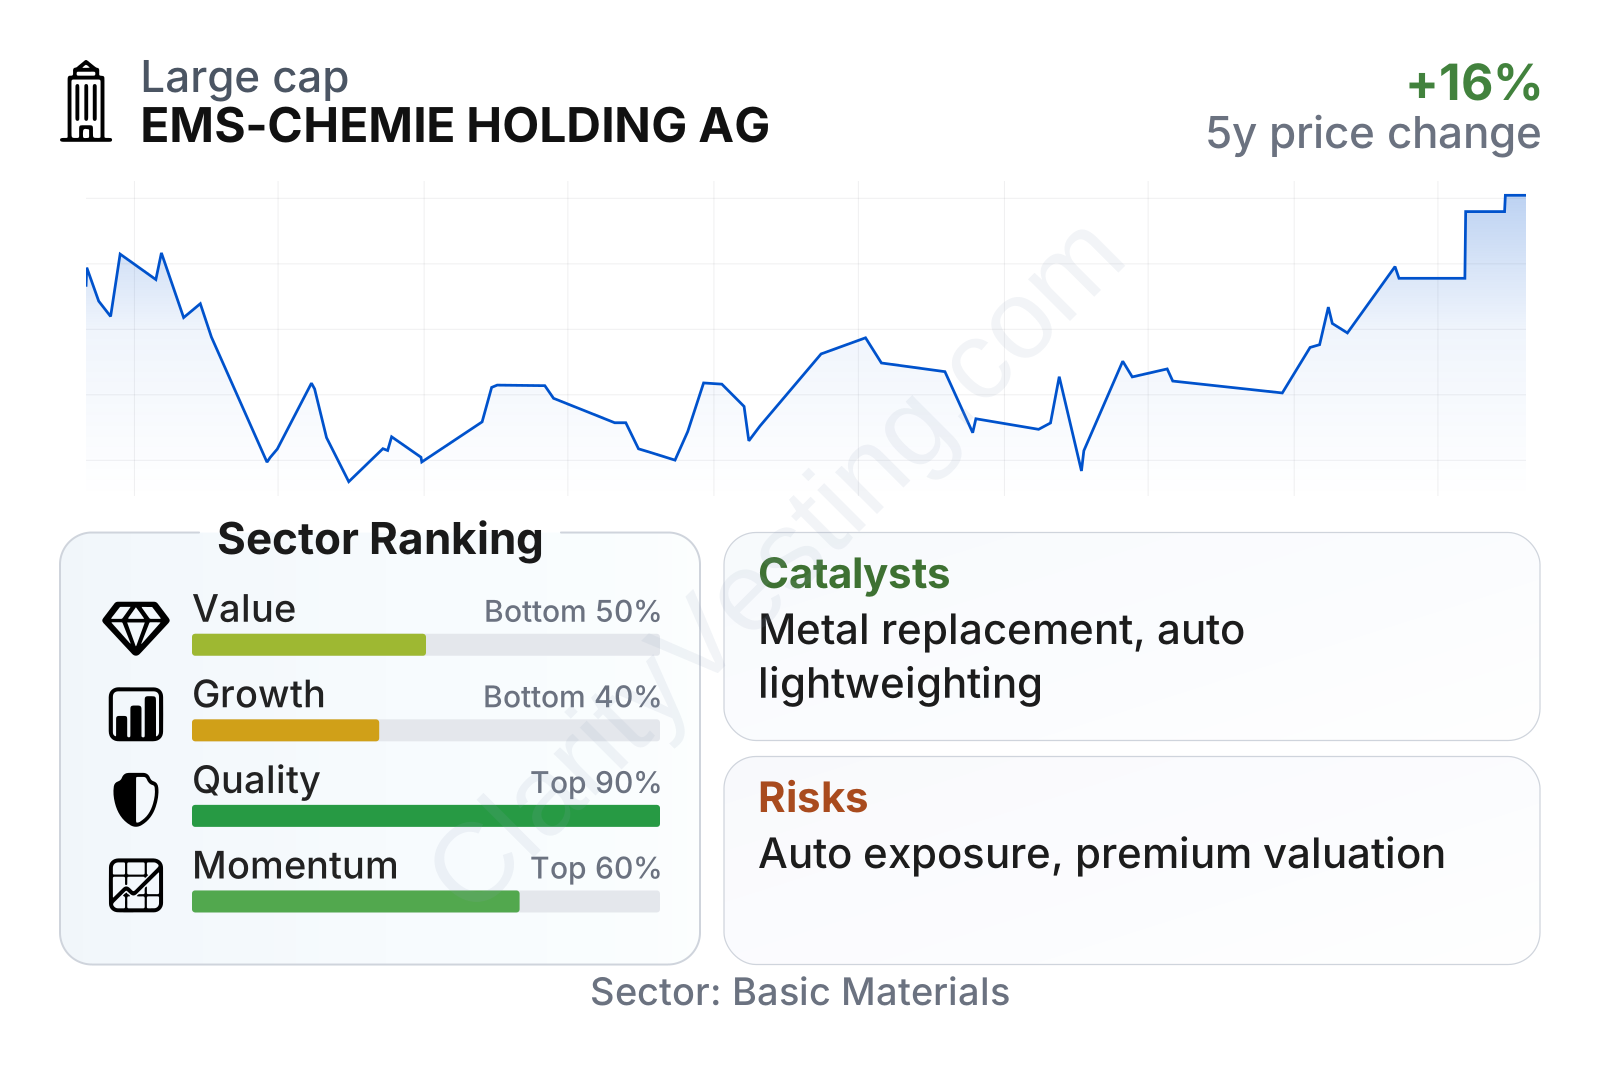
EMS-CHEMIE stands out more for business quality than for conventional cheapness or fast top-line growth. The company ranks near the top of its sector on return on invested capital, return on assets, margin strength, and balance-sheet conservatism. Debt is extremely low, and net cash metrics are better than most peers. On the other hand, valuation multiples are clearly above sector medians, while recent growth measures are weaker than the broader specialty chemicals group. In short, the profile is that of a very profitable, financially strong company whose market valuation already reflects part of that strength.
Growth
Specialty chemicals remains an attractive long-term industry because customers increasingly need lighter materials, better heat resistance, more design flexibility, and more efficient manufacturing. Those trends are especially relevant in automotive, electronics, and industrial applications. EMS-CHEMIE is positioned in the part of the market where technical know-how and application support matter, which is generally more resilient than commodity chemicals.
The company’s strategy is logically aligned with those trends. EMS-CHEMIE focuses on replacing heavier materials such as metal with advanced polymers, helping customers reduce weight, integrate parts, and simplify production. That is particularly relevant in vehicles, where efficiency, emissions, and electrification all favor advanced lightweight materials. It also matters in electronics, where miniaturization and heat management create demand for more specialized polymers.
That said, recent growth has been uneven. Revenue has been slightly down on the latest year-over-year reading, and the five-year record on revenue per share and earnings is softer than the sector median. This does not necessarily mean the business model is weakening; it reflects a mix of cyclical demand pressure, weaker industrial volumes, and the company’s willingness to prioritize profitability over aggressive volume expansion.
Cash generation remains a more encouraging signal. Free cash flow is strong in absolute terms and has compounded better than many sector peers over the last five years. This matters because it gives EMS-CHEMIE flexibility to invest in capacity, process improvements, customer development, and shareholder distributions without relying heavily on debt financing.
A practical catalyst for future expansion is the continued substitution of metal and heavier plastics by engineered polymers in automotive and industrial parts. Another is the company’s deep integration with customer design cycles: once a material is qualified in a technical component, switching costs can be meaningful. If global industrial demand improves, EMS-CHEMIE could benefit from both recovering volumes and its already high margin base.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


