Stock Analysis · Elementis plc (EMNSF)
Overview
Elementis plc is a specialty chemicals company that makes performance-enhancing ingredients used in everyday industrial and consumer products. Its additives are designed to improve texture, stability, flow, durability, and overall formulation performance. End markets include coatings, construction materials, personal care products, and certain industrial applications. The business is not built around commodity chemicals sold only on price; it focuses more on formulation know-how, application support, and niche product performance.
Based on the company’s recent annual reporting, revenue is mainly generated from three operating segments:
- Performance Specialties: about 70% to 75% of revenue. This is the largest segment and includes additives used in coatings, inks, construction, and other industrial applications where rheology control and formulation performance matter.
- Personal Care: about 20% to 25% of revenue. This segment supplies specialty ingredients used in skin care, hair care, antiperspirants, and cosmetics, where texture, feel, suspension, and product stability are important.
- Talc: about 5% to 10% of revenue. This business supplies talc products for industrial uses, including plastics, coatings, and certain technical applications.
Geographically, Elementis is diversified across North America, Europe, and Asia-Pacific, which helps reduce dependence on any one national economy, although it still remains exposed to global manufacturing activity and consumer demand cycles.
The business mix has also been gradually reshaped over the past few years toward higher-value specialties and tighter cost control. That matters because long-term value in specialty chemicals usually comes from pricing power, customer formulation dependency, and steady cash generation rather than from simple volume growth.
The profit flow over recent years shows a business that has been uneven at the net income line but has improved its underlying operating structure. Revenue has moved within a fairly narrow band, while gross profit and operating profitability have been more sensitive to cost swings, restructuring, and one-off items. A notable positive is that operating income rebounded strongly after earlier disruptions, suggesting the company’s margin improvement efforts have had real impact even if reported earnings remained noisy.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Specialty Chemicals | |
| Market Cap ⓘ | $1.27B | |
| Beta ⓘ | 0.91 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 18.67 | 16.90 |
| P/B Ratio ⓘ | 2.07 | 1.65 |
| FCF Yield ⓘ | 8.25% | 5.76% |
| Dividend Yield ⓘ | 1.92% | 2.13% |
| EBIT / EV ⓘ | 10.43% | 6.30% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 9.40% | 11.10% |
| RPS Growth (5Y CAGR) ⓘ | -3.46% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | -29.17% | -13.47% |
| BVPS Growth (5Y CAGR) ⓘ | -7.82% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | 7.25% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | 41.21% | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | -10.07% | 6.08% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 12.38% | 9.26% |
| ROA (Latest) ⓘ | -0.16% | 4.91% |
| ROIC (5Y Median) ⓘ | 3.68% | 7.70% |
| ROA (5Y Median) ⓘ | -2.95% | 3.86% |
| Net Debt / EBIT (Latest) ⓘ | 1.12 | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | 3.92 | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | 0.78 | 0.95 |
| Net Debt / Assets ⓘ | 15.71% | 13.69% |
| EBITDA / Interest ⓘ | 6.73 | 12.34 |
| Operating Margin (Latest) ⓘ | 12.64% | 13.20% |
| Operating Margin (5Y Median) ⓘ | 8.40% | 11.80% |
| Debt to Equity (Latest) ⓘ | 39.91% | 40.56% |
| Profit Margin (Latest) ⓘ | 11.86% | 6.43% |
| Free Cash Flow (Latest) ⓘ | $104.47M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +85.90% | +68.89% |
| 12M Return (excl. last month) ⓘ | +23.32% | +30.21% |
| 6M Return ⓘ | +12.36% | -4.16% |
| Price vs. 200-Day MA ⓘ | +29.85% | -1.27% |
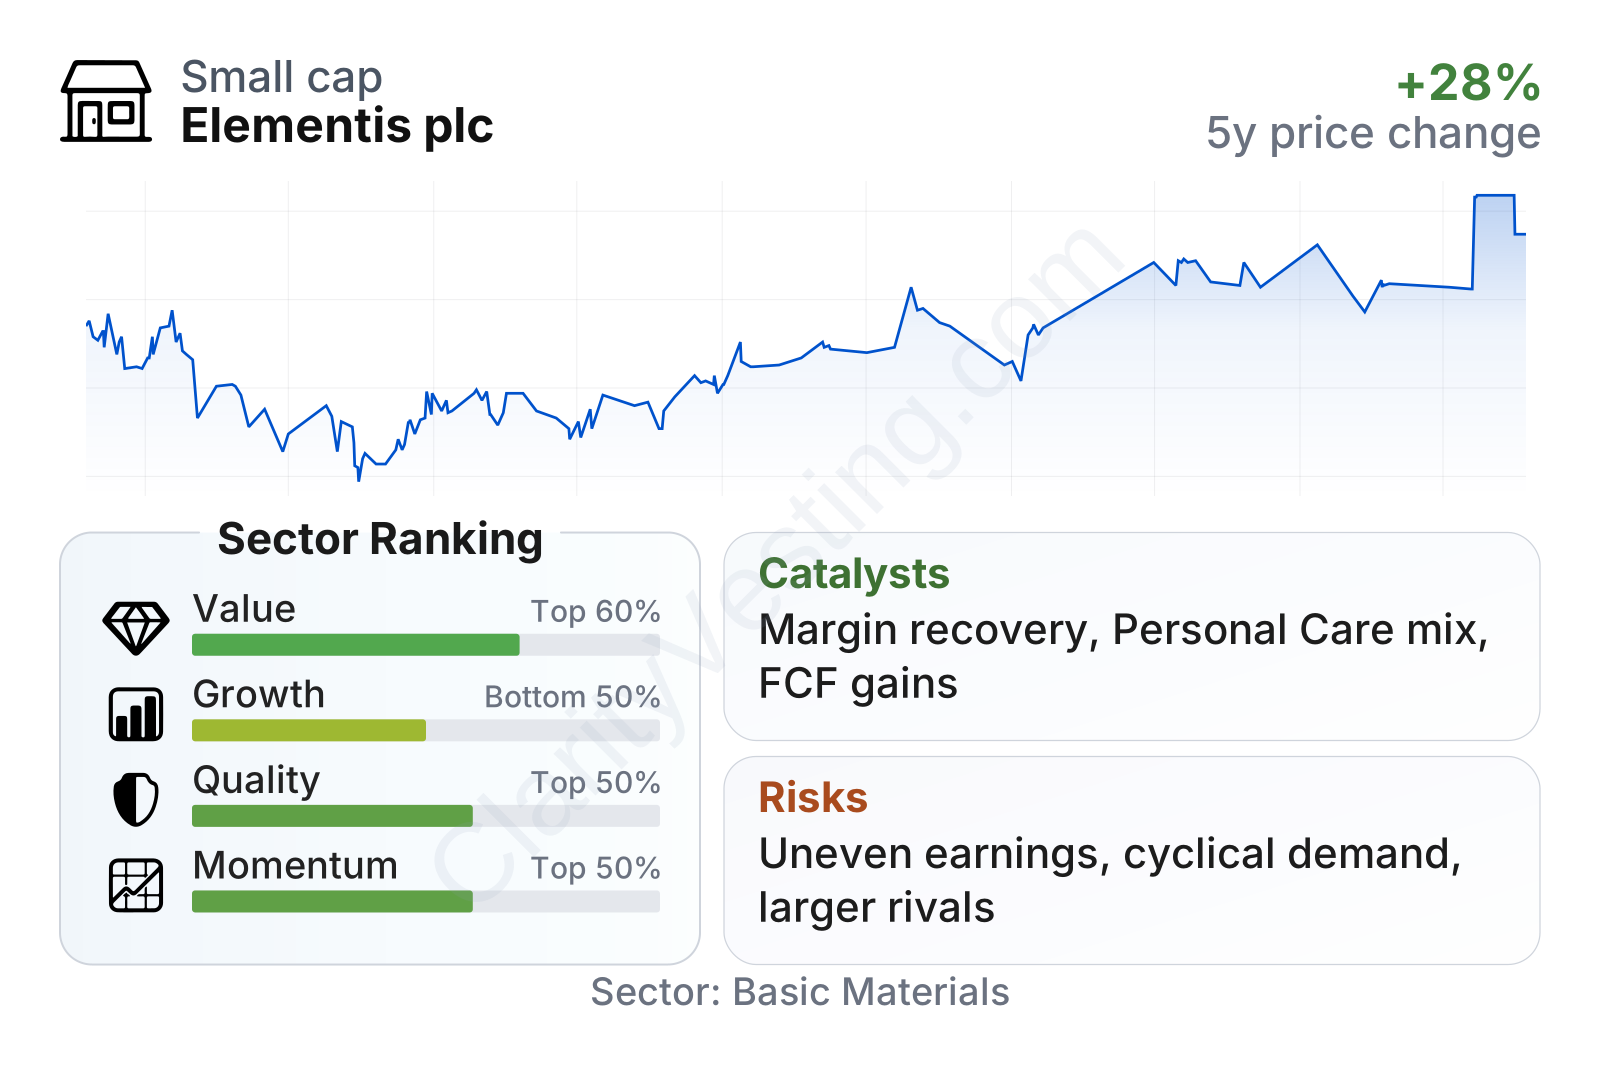
Elementis is a mid-sized specialty chemicals company with a share price history that has been volatile but improving over the longer stretch shown. The stock fell sharply in the earlier part of the period, then recovered and now stands well above those lows. That pattern fits a company moving from a more stressed phase toward operational stabilization, although the path has not been smooth.
The current metrics point to a mixed but improving profile. On valuation, Elementis does not look deeply discounted on traditional earnings or book value multiples, but its cash-based measures are more favorable than the sector median. Free cash flow yield and EBIT relative to enterprise value look comparatively solid, which suggests the market is giving some credit for better cash conversion but is not placing it among the cheapest names in the group.
Quality indicators are also mixed. Recent returns on invested capital are above the sector median, and leverage is moderate rather than excessive, with net debt below many peers on an EBITDA basis. Profit margin is stronger than the sector median as well. At the same time, interest coverage is not especially high, and longer-term profitability measures still show the effect of weaker years.
Growth is where the picture is less impressive. Recent year-over-year revenue growth has been positive, but five-year trends in revenue per share, earnings per share, and book value per share remain weak versus the broader sector. The main offset is very strong free cash flow growth over the same period, which suggests the company has been getting more disciplined about capital use and working capital management even without strong top-line expansion.
Growth
Elementis operates in specialty chemicals, a sector with durable long-term demand because its products are tied to formulation performance in coatings, personal care, construction, and industrial applications. That is generally a healthier place to be than bulk chemicals because customers often care more about consistency and product behavior than about the lowest possible input cost. Still, it is not a fast-growth industry across the board. Growth usually comes from innovation, share gains in specific niches, premium product mix, and expansion in attractive end markets rather than from broad economic acceleration alone.
The company’s strategy appears sensible for that environment. Management has emphasized simplification, productivity, portfolio focus, and margin improvement. For a business like Elementis, that can be more important than chasing volume. If the company can keep improving mix and cost efficiency while holding pricing discipline, even modest sales growth can translate into stronger cash generation.
Personal Care is one of the more interesting areas for future development because it gives Elementis exposure to consumer-oriented categories with formulation complexity and higher value-added ingredients. Performance Specialties also offers room for gains if coatings and construction activity remain stable and customers continue to favor additives that improve performance while reducing formulation problems.
A meaningful catalyst is the evidence of operational recovery already visible in margins and free cash flow. Operating margin has improved materially from its five-year median, and free cash flow generation has become a clearer strength. In specialty chemicals, that kind of improvement can matter more than headline revenue growth because it shows the company is extracting more value from its existing business base.
Another positive factor is that recent market performance has been better over the last six months than the sector median, and the shares trade well above the long-term moving average. That does not change the business itself, but it often reflects improving confidence that restructuring actions and profit recovery are becoming more credible.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


