Stock Analysis · Elementis PLC (ELMTY)
Overview
Elementis PLC is a specialty chemicals company. In simple terms, it makes performance-enhancing ingredients that are added to other companies’ products to improve how they feel, spread, thicken, protect, suspend particles, or perform under demanding conditions. Its materials are used in everyday categories such as personal care, coatings, construction products, and certain industrial applications.
The business is not a commodity chemicals producer in the pure sense. It focuses more on formulation-critical additives, where customers often care about consistency, regulatory compliance, performance, and technical support rather than just the lowest price. That generally creates better margins than basic chemical products, although demand can still move with industrial cycles.
Based on company reporting in recent annual materials, Elementis’ revenue mix is centered on three main areas:
- Performance Specialties: approximately 70% to 75% of revenue. This includes rheology modifiers and specialty additives used in coatings, construction, adhesives, and certain industrial formulations.
- Personal Care: approximately 20% to 25% of revenue. These ingredients are used in skin care, color cosmetics, sun care, hair care, and other beauty and personal care products.
- Talc: approximately 5% to 10% of revenue. This segment serves industrial uses and remains much smaller than the core specialties operations.
Geographically, Elementis sells globally, with exposure across the Americas, Europe, and Asia-Pacific. That broad footprint helps diversify end markets, but it also means earnings can be influenced by regional manufacturing conditions, foreign exchange swings, and different customer demand cycles.
Looking at the business flow over recent years, revenue has been fairly stable overall, while profitability has moved around more sharply. Gross profit improved meaningfully from 2021 to 2024 as product mix and pricing helped, but bottom-line results were more volatile because of restructuring, impairment, and other below-the-operating-line items. That pattern matters for long-term analysis: the underlying operating engine appears steadier than headline net income.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Specialty Chemicals | |
| Market Cap ⓘ | $1.27B | |
| Beta ⓘ | 0.91 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 18.37 | 16.90 |
| P/B Ratio ⓘ | 2.05 | 1.65 |
| FCF Yield ⓘ | 8.34% | 5.76% |
| Dividend Yield ⓘ | 1.97% | 2.13% |
| EBIT / EV ⓘ | 10.44% | 6.30% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 9.40% | 11.10% |
| RPS Growth (5Y CAGR) ⓘ | -3.93% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | -7.50% | -13.47% |
| BVPS Growth (5Y CAGR) ⓘ | -7.85% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | 15.10% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | 40.52% | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | -10.36% | 6.08% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 12.40% | 9.26% |
| ROA (Latest) ⓘ | -0.13% | 4.91% |
| ROIC (5Y Median) ⓘ | 3.59% | 7.70% |
| ROA (5Y Median) ⓘ | -2.95% | 3.86% |
| Net Debt / EBIT (Latest) ⓘ | 1.12 | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | 4.32 | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | 0.81 | 0.95 |
| Net Debt / Assets ⓘ | 15.71% | 13.69% |
| EBITDA / Interest ⓘ | 6.49 | 12.34 |
| Operating Margin (Latest) ⓘ | 12.53% | 13.20% |
| Operating Margin (5Y Median) ⓘ | 8.20% | 11.80% |
| Debt to Equity (Latest) ⓘ | 39.91% | 40.56% |
| Profit Margin (Latest) ⓘ | 11.86% | 6.43% |
| Free Cash Flow (Latest) ⓘ | $105.95M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +70.05% | +68.89% |
| 12M Return (excl. last month) ⓘ | +12.54% | +30.21% |
| 6M Return ⓘ | +11.17% | -4.16% |
| Price vs. 200-Day MA ⓘ | +35.49% | -1.27% |
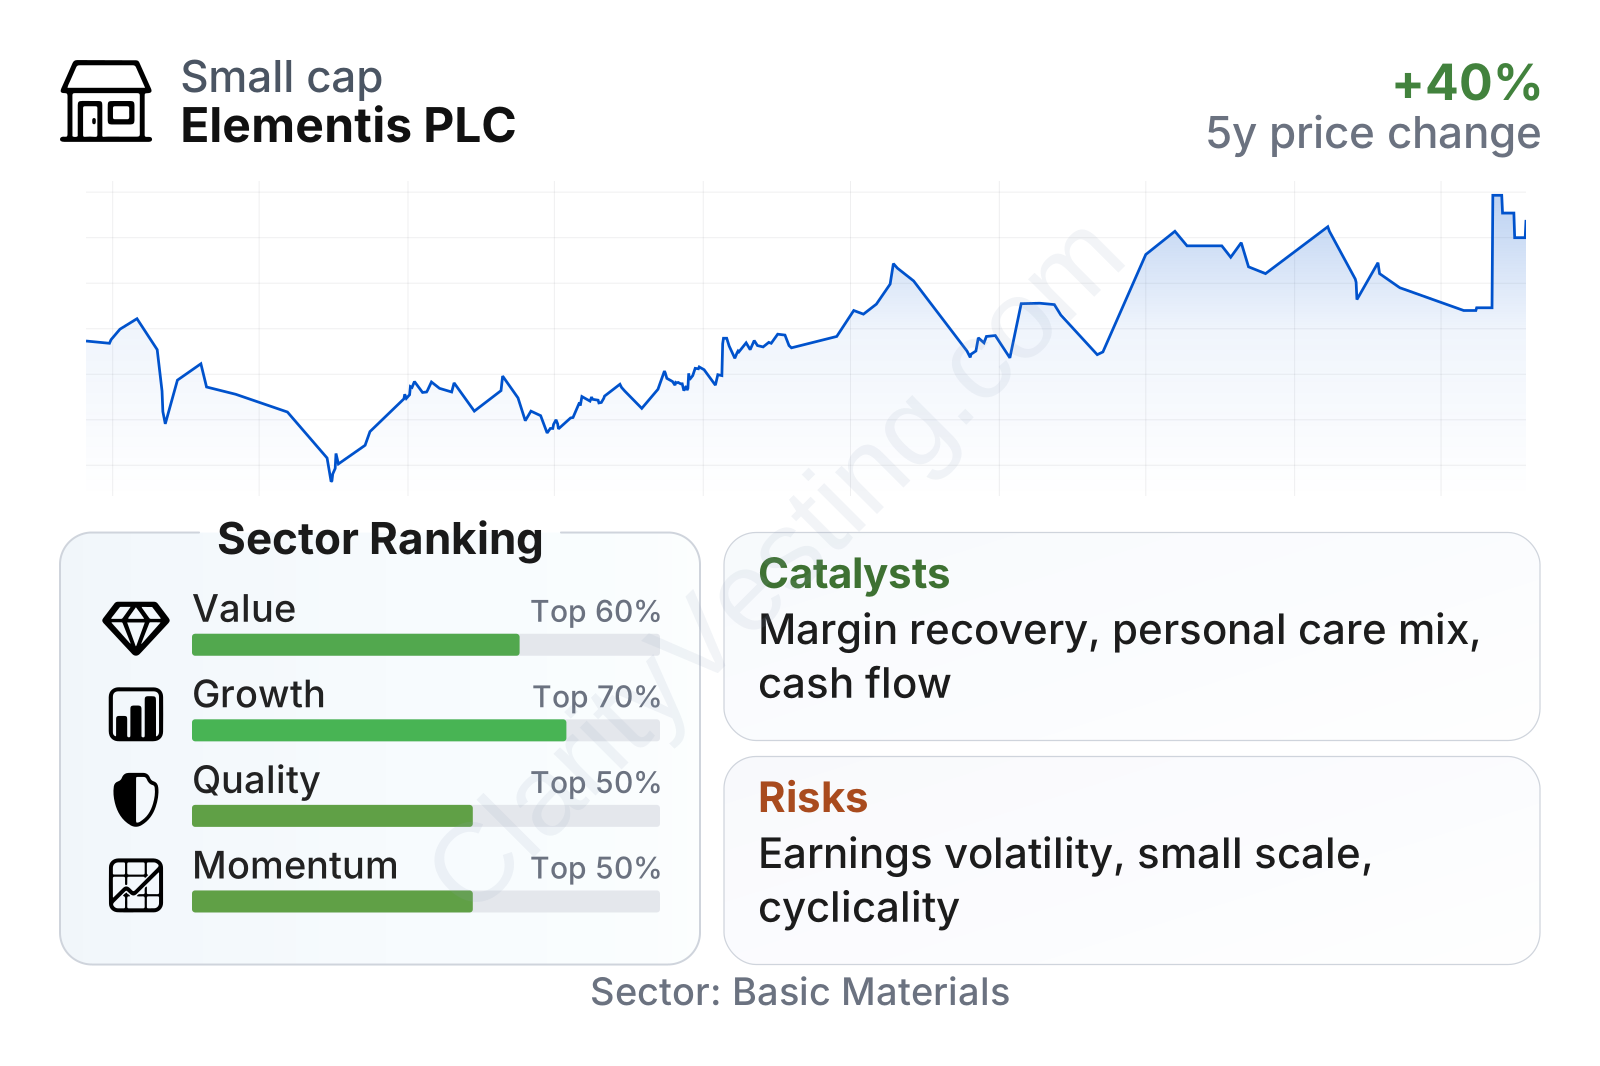
Elementis is a mid-sized specialty chemicals company with a share price that has recovered from 2023 levels and is now above its longer-term average trend, even after weaker performance over the last 12 months compared with much of the sector. The financial profile looks mixed but improving: valuation is not stretched on cash generation, recent profitability is solid relative to many peers, and leverage is currently moderate. At the same time, the longer five-year record remains less impressive on revenue per share, book value per share, and asset returns, which shows that the turnaround is still newer than fully proven.
One encouraging point is cash generation. Free cash flow yield stands above the sector median, and free cash flow has expanded strongly over the last five years from a low base. Another is current operating efficiency: return on invested capital and profit margin are ahead of sector medians, while net debt relative to EBIT and EBITDA is below the median, suggesting balance sheet pressure is lower than it used to be.
Growth
Elementis operates in parts of the chemicals market that tend to grow with consumer product innovation, coatings demand, infrastructure repair, and higher-value formulations. That is not a high-growth industry in the way software or semiconductors can be, but specialty additives can still benefit from attractive long-term trends. Personal care ingredients can grow through premiumization, new textures, and cleaner-label formulations. Coatings and construction additives can benefit from lightweighting, durability needs, waterborne systems, and stricter performance requirements.
The company’s strategy appears sensible for this kind of market. Management has spent recent years emphasizing portfolio simplification, operational improvement, and focusing capital on categories where Elementis has stronger technical differentiation. For a business of this size, that matters: competing broadly against much larger chemical groups is difficult, while concentrating on narrower application niches can support better pricing and customer retention.
There are also signs that the underlying business has been improving in quality even if reported earnings have looked uneven. Operating margin trends over five years have improved substantially, and current operating margins are roughly in line with the sector median despite a weaker historical base. That suggests restructuring and cost actions may be having an effect.
A potential catalyst is the combination of margin recovery and cash conversion. If the company can maintain stronger operating income while avoiding the one-off charges that hurt reported net income in some recent periods, the market may pay more attention to the strength of the core business rather than the noise in statutory earnings. Another possible support is the personal care segment, where formulation-led products typically carry better margins and are less tied to heavy industrial cycles than some other chemical end markets.
Recent company updates have also pointed to continued focus on productivity, simplification, and disciplined capital allocation. For long-term analysis, the important question is not whether a single quarter is strong, but whether Elementis can steadily convert its narrower portfolio into more consistent returns. That path is plausible, though not yet beyond doubt.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


