Stock Analysis · ELF Beauty Inc (ELF)
Overview
e.l.f. Beauty is a U.S. cosmetics company focused on accessible-priced beauty and personal care products. Its brands are sold through large retailers, specialty beauty stores, e-commerce, and international distribution partners. The group is best known for the e.l.f. Cosmetics and e.l.f. SKIN brands, and in recent years it has expanded through acquisitions, including Naturium, to strengthen its presence in skincare.
The business is still largely driven by cosmetics, but skincare has become a more meaningful contributor as the company has broadened its brand portfolio. Based on recent company disclosures, revenue is concentrated in the following areas:
- Cosmetics and beauty tools: approximately 70% to 80% of revenue. This includes face, eye, lip, brush, and accessory products sold mainly under the e.l.f. brand.
- Skincare: approximately 20% to 30% of revenue. This includes e.l.f. SKIN and Naturium products such as cleansers, serums, moisturizers, and sun care.
- Other beauty and personal care activities: a small remainder. This can include adjacent products and channel-related items that are not broken out in detail.
Geographically, the company remains heavily tied to the United States, which accounts for the large majority of sales, while international business is growing from a smaller base. Distribution is also concentrated in retail partners and digital channels rather than company-owned stores, which keeps the operating model relatively asset-light.
Over the last several years, the company has scaled quickly. Revenue rose from about $392 million in fiscal 2022 to about $1.64 billion in fiscal 2026, while gross profit expanded even faster in dollar terms. The main change more recently is that operating costs have climbed sharply as the company invests in marketing, distribution, brand building, and integration of acquired assets. That helps explain why sales are still rising strongly while net income has become more pressured.
The overall picture is a company that has built a large beauty platform around affordable pricing, fast product launches, and strong social-media-driven brand awareness, but which is now balancing rapid expansion with heavier expense levels.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Consumer Defensive | |
| Industry | Household & Personal Products | |
| Market Cap ⓘ | $6.45B | |
| Beta ⓘ | 1.60 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 111.52 | 17.88 |
| P/B Ratio ⓘ | 5.53 | 1.29 |
| FCF Yield ⓘ | 4.34% | 12.39% |
| Dividend Yield ⓘ | N/A | 2.85% |
| EBIT / EV ⓘ | 1.98% | 6.43% |
| PEG ⓘ | 1.37 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 35.50% | 4.10% |
| RPS Growth (5Y CAGR) ⓘ | 39.37% | 6.18% |
| EPS Growth (5Y CAGR) ⓘ | -3.06% | -13.59% |
| BVPS Growth (5Y CAGR) ⓘ | 34.49% | 3.20% |
| Margin Growth (5Y Trend) ⓘ | -2.06% | -0.15% |
| FCF Growth (5Y CAGR) ⓘ | 89.64% | 4.10% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.79% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 4.53% | 12.34% |
| ROA (Latest) ⓘ | 2.49% | 6.30% |
| ROIC (5Y Median) ⓘ | 13.00% | 10.49% |
| ROA (5Y Median) ⓘ | 9.43% | 5.44% |
| Net Debt / EBIT (Latest) ⓘ | 4.46 | 1.96 |
| Net Debt / EBIT (5Y Median) ⓘ | 1.20 | 2.35 |
| Net Debt / EBITDA (Latest) ⓘ | 2.60 | 1.38 |
| Net Debt / Assets ⓘ | 23.47% | 21.51% |
| EBITDA / Interest ⓘ | 4.83 | 9.46 |
| Operating Margin (Latest) ⓘ | 7.36% | 8.87% |
| Operating Margin (5Y Median) ⓘ | 11.70% | 9.53% |
| Debt to Equity (Latest) ⓘ | 78.85% | 72.35% |
| Profit Margin (Latest) ⓘ | 3.38% | 5.40% |
| Free Cash Flow (Latest) ⓘ | $280.16M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +6.68% | +20.92% |
| 12M Return (excl. last month) ⓘ | -28.33% | +2.13% |
| 6M Return ⓘ | +64.83% | +1.26% |
| Price vs. 200-Day MA ⓘ | +36.50% | +1.39% |
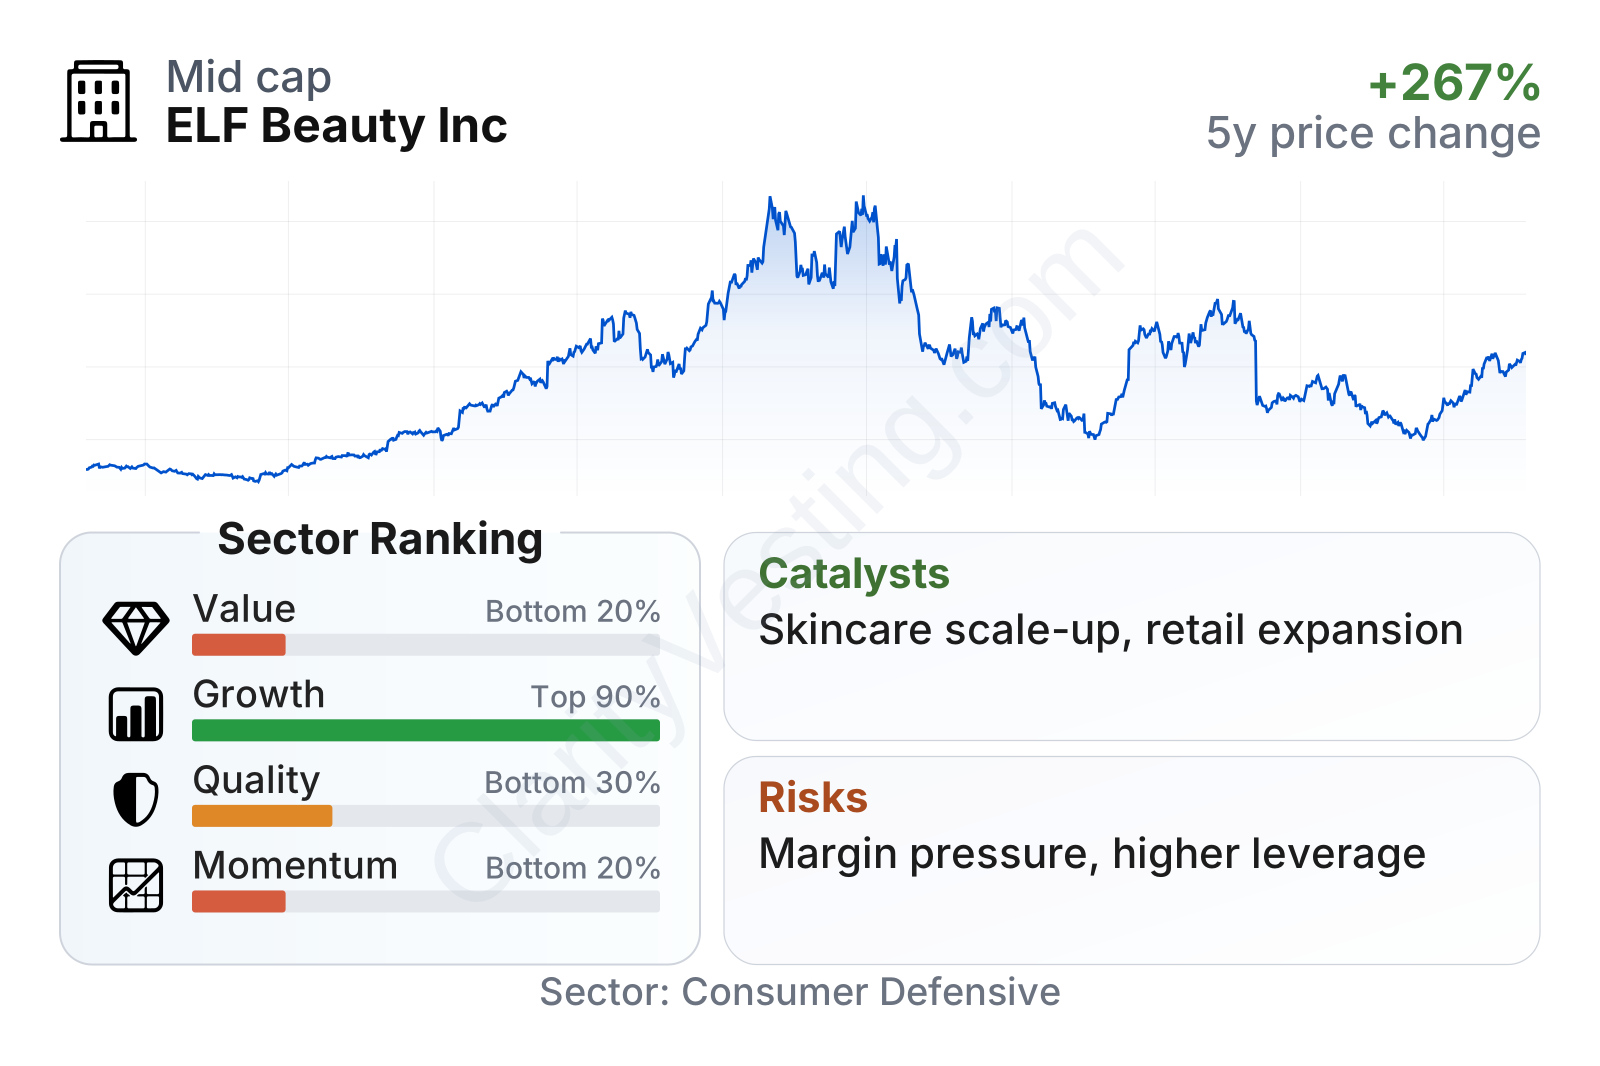
The company stands out for growth rather than traditional value or income characteristics. It ranks near the top of its sector on growth metrics, with revenue growth far above the sector median and a very strong multi-year expansion in revenue per share and free cash flow. By contrast, valuation multiples are elevated, profitability measures are currently below many sector peers, and share-price behavior has been volatile, which is consistent with a business the market still prices on future potential more than present-day stability.
At a broad level, e.l.f. Beauty is now a mid-sized public company with above-average stock volatility. It does not pay a dividend, so the investment profile depends mostly on business execution, margin recovery, and the market’s willingness to keep assigning a premium multiple.
Growth
The beauty category is generally attractive for long-term growth because it benefits from repeat purchases, brand loyalty, product innovation, and strong digital influence. Within that broader market, e.l.f. Beauty operates in one of the more dynamic corners: affordable prestige-like beauty, where consumers look for trend-driven products at lower price points. That positioning can work well in both strong and soft consumer environments, since customers may trade into beauty trends while still staying price-conscious.
The company’s strategy is coherent. It relies on frequent product launches, strong marketing on social platforms, wide retail distribution, and a price architecture that is usually well below premium beauty brands. It has also expanded into skincare, which adds another category with recurring demand and helps reduce reliance on color cosmetics alone. The Naturium acquisition is especially important because it broadens the company into a faster-growing skincare segment and gives it exposure to a somewhat different consumer base.
Revenue growth has been exceptional compared with the rest of the household and personal products sector. Growth rates have cooled from the extremely high levels seen during the earlier breakout phase, but recent year-over-year expansion is still around the mid-30% range, which remains unusually strong for a consumer staples-related business. That suggests e.l.f. is still gaining market share rather than simply benefiting from temporary demand.
Cash generation has also improved meaningfully over time. Free cash flow has moved from a modest level a few years ago to well above $100 million, and the latest trailing figure is around $280 million. That matters because it shows the company’s expansion is not purely accounting-driven; the business is producing real cash even while funding marketing and growth initiatives.
A key catalyst in the current setup is distribution expansion. e.l.f. has repeatedly widened shelf space and retailer relationships in the U.S., while international markets still represent a smaller base with room to grow. Another catalyst is category mix: skincare and acquired brands can add incremental growth if they scale well inside the company’s broader retail and digital network. Product innovation is another lever, since the brand has shown an ability to react quickly to trends and launch items that resonate with younger consumers.
Recent company communications have also pointed to continued category expansion, brand-building investment, and broader omnichannel reach. For a long-term assessment, the main positive signal is that growth has stayed strong even after the business passed the $1 billion revenue mark, which is usually the point where many fast-growing consumer brands begin to slow more sharply.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


