Stock Analysis · Elanco Animal Health (ELAN)
Overview
Elanco Animal Health is a global animal health company focused on medicines, vaccines, parasite treatments, and other products used in pets and livestock. Its business sits at the intersection of veterinary care, food production, and companion animal spending. In simple terms, Elanco sells products that help keep dogs and cats healthier and products that help farmers raise cattle, poultry, swine, and other animals more efficiently and safely.
The company’s revenue comes from two large operating groups: Pet Health and Farm Animal. Based on recent annual reporting, Pet Health has become the larger business, while Farm Animal remains a major contributor with a broad international footprint. Within those groups, Elanco is exposed to both recurring demand such as flea, tick, and deworming treatments, and more cyclical demand tied to livestock economics.
The business mix can be summarized this way:
- Pet Health: about 55% to 60% of revenue. This includes products for dogs and cats such as parasiticides, vaccines, dermatology, pain products, and treatments sold through veterinarians and retail channels.
- Farm Animal: about 40% to 45% of revenue. This includes products for cattle, poultry, swine, and aquaculture, including vaccines, anti-infectives, parasiticides, and productivity-related treatments.
- By geography, international markets represent a large share of sales alongside the U.S., giving Elanco broader diversification than a purely domestic animal health company.
Elanco’s scale is meaningful, but its profile differs from the most profitable animal health leaders. Revenue has been relatively stable over the last few years, while earnings have been more volatile because of restructuring costs, integration work after acquisitions, amortization and impairment charges, and a still-elevated debt load. At the same time, the company has maintained a broad product portfolio and solid cash generation, which are important features for a business in a defensive healthcare niche.
The multi-year picture shows a business with fairly steady sales around the mid-$4 billion range, but profits have moved much more sharply. Gross profit has remained substantial, while selling and administrative costs have stayed heavy. Interest expense has also taken a meaningful share of earnings, which helps explain why cash generation has looked better than bottom-line profit.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Drug Manufacturers - Specialty & Generic | |
| Market Cap ⓘ | $11.26B | |
| Beta ⓘ | 1.71 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 25.42 |
| P/B Ratio ⓘ | 1.74 | 3.08 |
| FCF Yield ⓘ | 3.37% | 3.12% |
| Dividend Yield ⓘ | N/A | 1.85% |
| EBIT / EV ⓘ | 0.55% | 0.56% |
| PEG ⓘ | 4.04 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 10.20% | 7.50% |
| RPS Growth (5Y CAGR) ⓘ | -0.72% | 8.60% |
| EPS Growth (5Y CAGR) ⓘ | -10.25% | -17.73% |
| BVPS Growth (5Y CAGR) ⓘ | -3.82% | 3.72% |
| Margin Growth (5Y Trend) ⓘ | N/A | -0.57% |
| FCF Growth (5Y CAGR) ⓘ | -0.18% | 0.96% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.69% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 0.61% | 3.17% |
| ROA (Latest) ⓘ | -1.47% | 2.98% |
| ROIC (5Y Median) ⓘ | -0.03% | 4.56% |
| ROA (5Y Median) ⓘ | -1.79% | 1.87% |
| Net Debt / EBIT (Latest) ⓘ | 41.83 | 1.34 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.86 |
| Net Debt / EBITDA (Latest) ⓘ | 4.38 | 1.00 |
| Net Debt / Assets ⓘ | 24.98% | 5.06% |
| EBITDA / Interest ⓘ | 2.99 | 9.55 |
| Operating Margin (Latest) ⓘ | 1.61% | 9.25% |
| Operating Margin (5Y Median) ⓘ | -0.08% | 7.33% |
| Debt to Equity (Latest) ⓘ | 59.47% | 26.68% |
| Profit Margin (Latest) ⓘ | -3.96% | 3.34% |
| Free Cash Flow (Latest) ⓘ | $379.00M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +149.34% | +51.61% |
| 12M Return (excl. last month) ⓘ | +20.49% | +19.90% |
| 6M Return ⓘ | +1.02% | +10.10% |
| Price vs. 200-Day MA ⓘ | -4.74% | +6.44% |
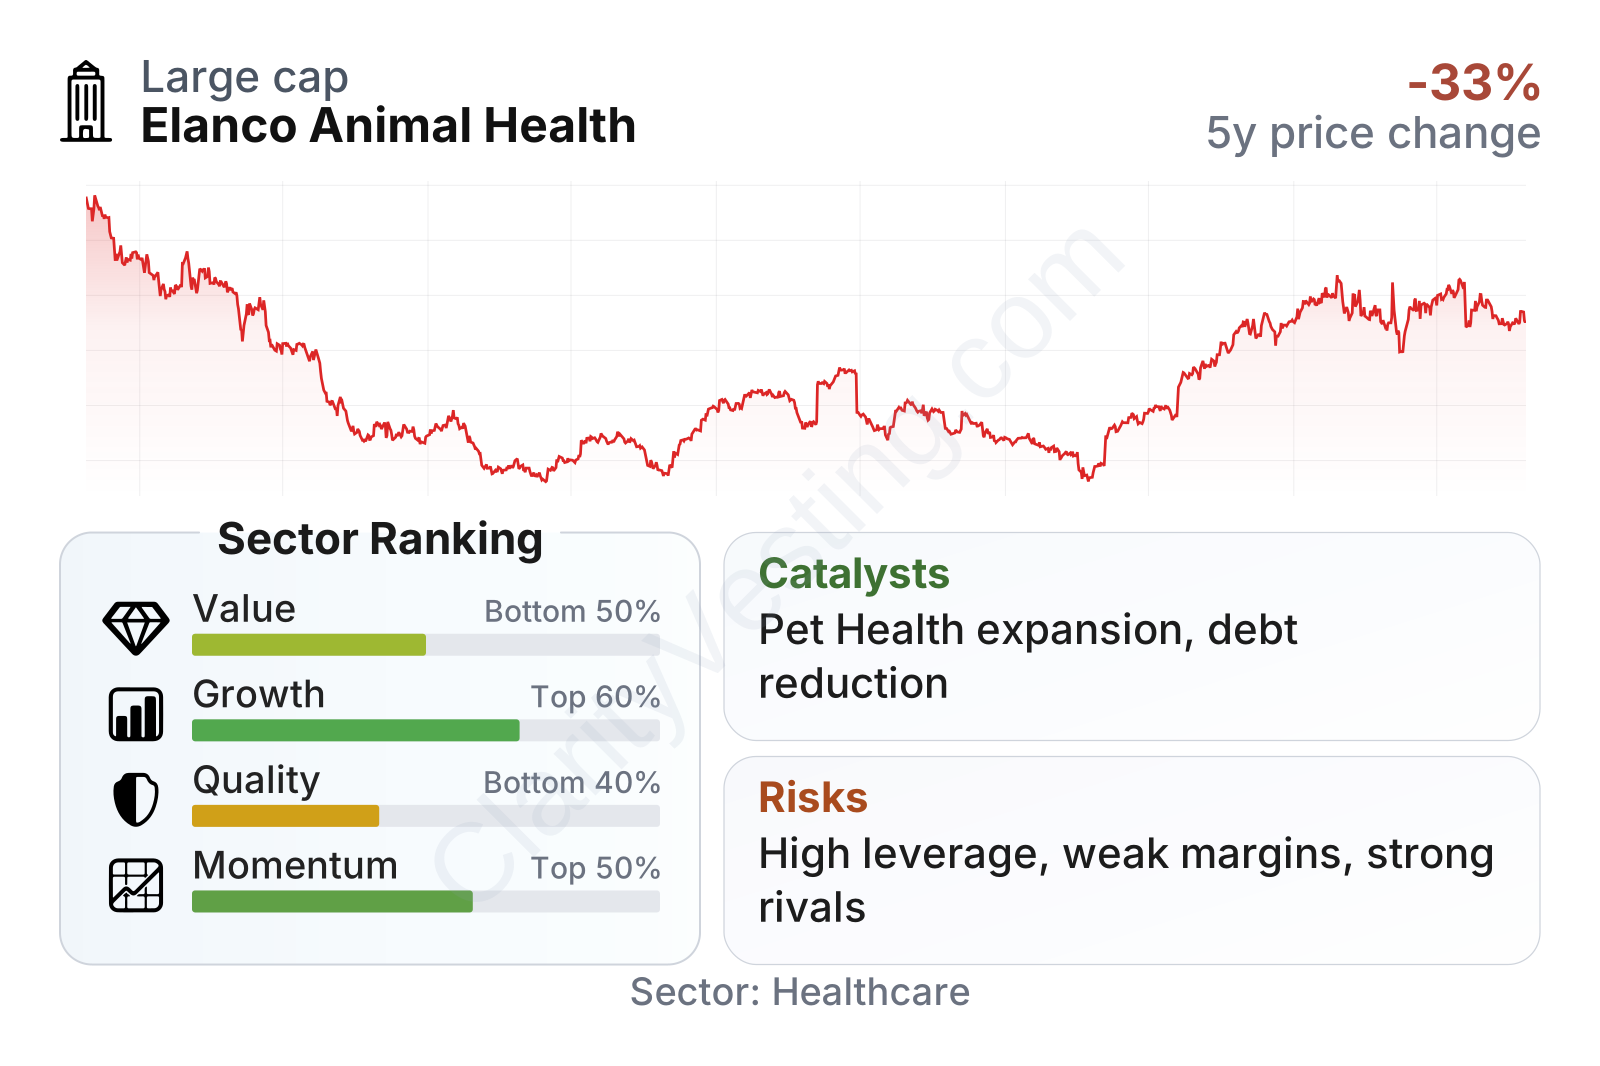
Elanco stands out as a mid-sized healthcare company with above-average share price volatility. The factor breakdown points to a mixed profile: growth has recently improved versus much of the sector, but quality remains weaker because returns on capital are low, margins are thin, and leverage is still high. On valuation, the picture is not obviously stretched on book value or free cash flow yield, but it also does not look clearly cheap when profitability and earnings consistency are taken into account.
The share price history reflects that uneven operating backdrop. After a deep decline from 2021 into 2023, the stock has staged a strong recovery into 2026. That rebound suggests the market has become more constructive on restructuring progress, debt reduction, and improving sales trends, but it also means the easy part of the rerating may already be behind it.
Growth
The animal health market has attractive long-term characteristics. Pet care tends to benefit from rising spending on companion animals, expansion of preventive care, and growing demand for treatments that improve quality of life for pets. Livestock health benefits from rising protein consumption in many regions and from producers’ need to improve herd health, productivity, and disease management. These are generally durable trends rather than short-lived fashions.
For Elanco specifically, the strategic logic is clear. The company has been shifting its emphasis toward higher-value pet health products while still using its large farm-animal platform to generate scale and cash flow. That mix can support growth if newer products gain traction and if management continues simplifying the portfolio. Elanco has also highlighted innovation in parasiticides and other differentiated products, which matters because branded animal health products can maintain demand for long periods when they earn veterinarian trust.
Recent sales momentum has improved. Year-over-year growth turned positive again after a weak period and has recently been running around low double digits, which is ahead of the broader sector median. That does not erase the slower five-year trend, but it does suggest the business has regained some traction after a difficult stretch.
Cash generation has been more resilient than reported earnings. Free cash flow has stayed positive and has trended in the few-hundred-million-dollar range, even as accounting profits moved around sharply. For a company in turnaround mode, that matters because cash can be used for debt reduction, product investment, and operational restructuring. One of the more important catalysts is therefore not just revenue growth itself, but whether higher sales can translate into steadier cash conversion and better margins.
Recent company updates have also pointed to execution priorities that could support future results: continued focus on key pet health brands, productivity programs, and debt management. For Elanco, a significant opportunity would come from proving that recent revenue acceleration is not temporary and that earnings can normalize without relying on one-time items.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


