Stock Analysis · Encompass Health Corp (EHC)
Overview
Encompass Health is a U.S. healthcare provider focused on rehabilitation after serious illness or injury. Its main business is inpatient rehabilitation, where patients stay in a specialized hospital to recover after events such as strokes, brain injuries, spinal cord injuries, hip fractures, and other major medical conditions. The company operates a nationwide network of inpatient rehabilitation hospitals and also offers home-based care through its home health and hospice operations, although the corporate focus has become increasingly centered on rehabilitation hospitals.
This is a fairly specialized part of healthcare. Encompass Health works in a setting between acute-care hospitals and the patient’s return home, aiming to improve functional recovery and reduce complications. Demand is closely tied to aging demographics, hospital discharge patterns, and the need for post-acute care that is less intensive than a general hospital but more advanced than a nursing facility.
Based on the company’s recent structure, revenue is overwhelmingly generated by inpatient rehabilitation services, with a smaller contribution from home health and hospice activities where applicable in the reporting period. A practical breakdown is:
- Inpatient rehabilitation hospitals: approximately 85% to 90% of revenue. This includes room, nursing, therapy, pharmacy, and other hospital-based rehabilitation services.
- Home health and hospice / other care-related activities: approximately 10% to 15% of revenue, depending on the reporting period and business mix.
The business model is relatively straightforward: revenue comes mainly from treating patients, and profitability depends on occupancy, discharge volumes, reimbursement rates, labor efficiency, and maintaining strong clinical outcomes that support referrals from acute-care hospitals and physicians.
Over the last several years, the company’s revenue and operating income have trended upward, while interest expense has moved lower. That combination suggests the business has been scaling while gradually improving financial flexibility, although 2025 line items appear less comparable in the visual breakdown and should be read mainly as directional rather than perfectly consistent with prior years.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 04, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Medical Care Facilities | |
| Market Cap ⓘ | $11.82B | |
| Beta ⓘ | 0.61 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 20.00 | 24.06 |
| P/B Ratio ⓘ | 6.91 | 3.08 |
| FCF Yield ⓘ | 3.50% | 3.08% |
| Dividend Yield ⓘ | 0.64% | 2.05% |
| EBIT / EV ⓘ | 7.80% | 0.63% |
| PEG ⓘ | 0.41 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 9.60% | 7.50% |
| RPS Growth (5Y CAGR) ⓘ | 9.72% | 8.70% |
| EPS Growth (5Y CAGR) ⓘ | -2.09% | -18.20% |
| BVPS Growth (5Y CAGR) ⓘ | 1.72% | 3.95% |
| Margin Growth (5Y Trend) ⓘ | 1.46% | -0.58% |
| FCF Growth (5Y CAGR) ⓘ | 27.81% | 0.88% |
| DPS Growth (5Y CAGR) ⓘ | -11.26% | 6.80% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 18.29% | 3.29% |
| ROA (Latest) ⓘ | 8.67% | 3.02% |
| ROIC (5Y Median) ⓘ | 13.57% | 4.75% |
| ROA (5Y Median) ⓘ | 6.19% | 1.93% |
| Net Debt / EBIT (Latest) ⓘ | 2.37 | 1.33 |
| Net Debt / EBIT (5Y Median) ⓘ | 3.87 | 1.83 |
| Net Debt / EBITDA (Latest) ⓘ | 1.82 | 0.99 |
| Net Debt / Assets ⓘ | 36.67% | 5.33% |
| EBITDA / Interest ⓘ | 11.94 | 9.63 |
| Operating Margin (Latest) ⓘ | 18.59% | 9.25% |
| Operating Margin (5Y Median) ⓘ | 16.51% | 7.80% |
| Debt to Equity (Latest) ⓘ | 109.42% | 28.99% |
| Profit Margin (Latest) ⓘ | 10.01% | 3.60% |
| Free Cash Flow (Latest) ⓘ | $413.40M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +85.70% | +36.74% |
| 12M Return (excl. last month) ⓘ | -1.34% | +20.89% |
| 6M Return ⓘ | +23.46% | +9.73% |
| Price vs. 200-Day MA ⓘ | +11.15% | +4.69% |
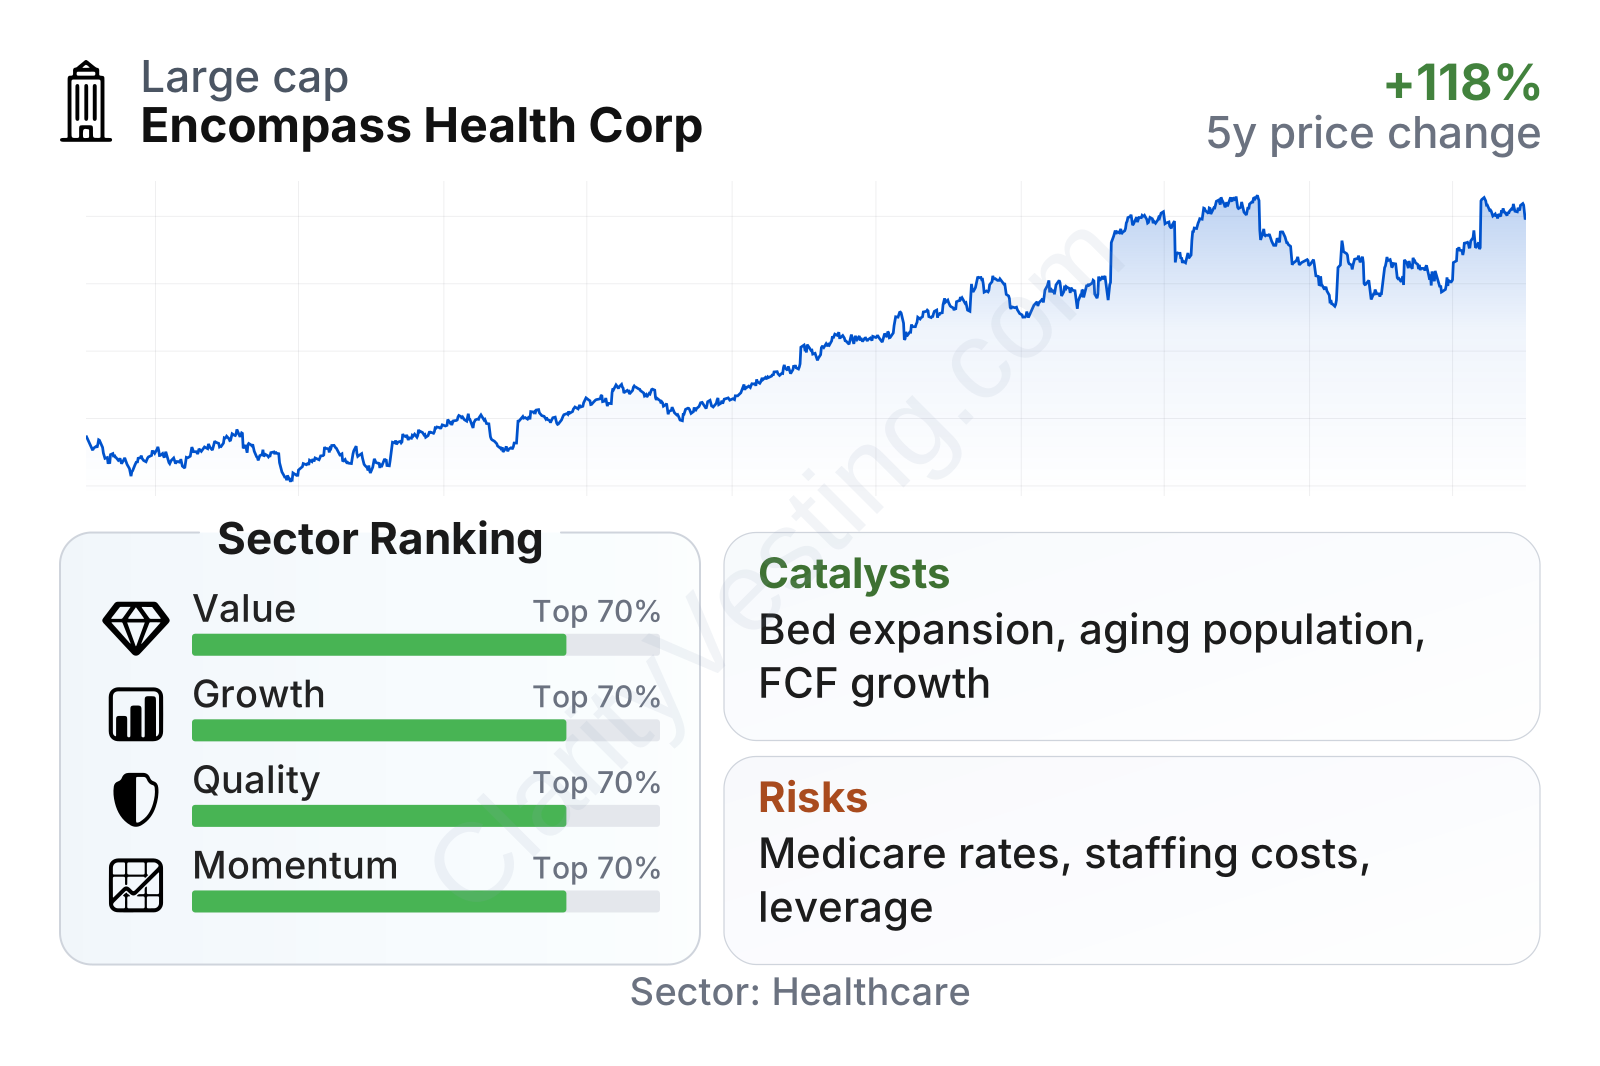
Encompass Health stands out as a mid-to-large healthcare operator with relatively low share-price volatility, as reflected by a beta well below 1. Across value, growth, and quality measures, it ranks in the upper part of its sector rather than at the very top, but the underlying mix is notable: profitability and returns on capital are clearly stronger than the sector median, revenue growth is modestly better than the sector median, and cash generation has improved meaningfully. The weaker points are a high price-to-book ratio and above-sector leverage, which matter because healthcare facilities are capital-intensive businesses. Recent share performance has been strong over three years, though the last 12 months have been less exceptional than the longer-term trend.
Growth
Encompass Health operates in a part of healthcare that has durable long-term demand drivers. The most important one is demographics: as the U.S. population ages, more patients are likely to need rehabilitation after surgeries, strokes, cardiac events, and other serious conditions. That does not guarantee uninterrupted growth, but it does provide a favorable backdrop for companies with the right clinical footprint and referral relationships.
The company’s strategy also looks coherent for this environment. It has been expanding bed capacity, adding hospitals through joint ventures and de novo development, and emphasizing a clinically specialized model that can attract referrals from acute-care systems. In rehabilitation, local density and reputation matter. A larger network can improve contracting, referrals, staffing, and brand recognition with physicians and hospital systems.
Revenue growth has been notably steady in the recent period, running around the high-single-digit to low-double-digit range. That consistency matters because it suggests the company is not relying on a one-time rebound. It points instead to a combination of volume growth, pricing or reimbursement support, and incremental capacity additions.
Cash generation has also moved in a favorable direction. Free cash flow has increased sharply over the last several years, rising from roughly the low hundreds of millions to well above $400 million on a trailing basis. For a hospital operator, that is important because cash can support new facilities, debt reduction, and shareholder returns without depending entirely on external financing.
A meaningful catalyst is continued capacity expansion in inpatient rehabilitation hospitals. Encompass Health has regularly announced new hospitals, bed additions, and partnerships with health systems through its investor relations communications. That expansion is relevant because new beds are one of the clearest ways for the company to increase revenue in a business where demand is often constrained by available specialized capacity rather than only by patient need. Another favorable factor is Medicare reimbursement updates, which can support revenue when rate increases keep pace with labor and supply cost pressure.
Recent company updates have also pointed to ongoing operating discipline, including labor management and occupancy improvement. In healthcare services, margin expansion often depends less on breakthrough innovation and more on execution. Encompass Health’s recent pattern suggests that execution has been one of the company’s stronger attributes.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


