Stock Analysis · Eldorado Gold Corp (EGO)
Overview
Eldorado Gold Corp is a mid-sized gold mining company that explores for, develops, and operates mines. Its business is straightforward: it produces gold, sells that gold into the market, and also earns smaller amounts from by-product metals that come out of the same ore. The company’s operating base is spread across Canada, Türkiye, and Greece, with producing mines that give it more diversification than a single-asset miner, but still far less scale than the largest global gold groups.
The company’s revenue is overwhelmingly tied to metal sales, especially gold. Based on recent annual reporting, Eldorado’s revenue mix is approximately:
- Gold sales: about 90% to 93% of revenue. This is the core of the business and comes from production at Kisladag and Efemcukuru in Türkiye, Lamaque in Canada, and Olympias in Greece.
- Silver sales: about 4% to 7% of revenue. Silver is mainly a by-product from polymetallic operations, especially Olympias.
- Lead and zinc concentrates: about 2% to 4% of revenue. These are mostly linked to Olympias, where the ore body contains multiple metals.
That mix matters because Eldorado is still, in practical terms, a gold company first. Its results are driven mainly by three things: the gold price, how many ounces it produces, and the cost of getting those ounces out of the ground. Over the last few years, the business has become much more profitable at the operating level, helped by stronger gold prices and improving mine performance. Revenue has risen from just under $1.0 billion in 2023 to well above $1.3 billion in 2024, and then moved materially higher again in 2025. At the same time, interest expense has come down and net income has improved sharply, showing a much stronger earnings profile than in 2021 and 2022.
The broad trend is encouraging: sales have expanded meaningfully, operating profit has widened, and the company moved from losses earlier in the cycle to solid profitability. The main tradeoff is that cash generation can still swing because mine development spending remains heavy.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Gold | |
| Market Cap ⓘ | $10.15B | |
| Beta ⓘ | 1.51 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 13.75 | 17.61 |
| P/B Ratio ⓘ | 1.43 | 1.77 |
| FCF Yield ⓘ | -6.15% | 5.87% |
| Dividend Yield ⓘ | 0.38% | 2.06% |
| EBIT / EV ⓘ | 6.49% | 6.43% |
| PEG ⓘ | 5.96 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 7.90% | 11.30% |
| RPS Growth (5Y CAGR) ⓘ | 14.55% | 4.46% |
| EPS Growth (5Y CAGR) ⓘ | 118.20% | -13.11% |
| BVPS Growth (5Y CAGR) ⓘ | 1.21% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | 7.58% | -1.57% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 0.55% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.02% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 9.88% | 9.31% |
| ROA (Latest) ⓘ | 7.23% | 4.94% |
| ROIC (5Y Median) ⓘ | 3.20% | 7.91% |
| ROA (5Y Median) ⓘ | 2.22% | 3.93% |
| Net Debt / EBIT (Latest) ⓘ | 1.50 | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | 0.61 | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | 1.15 | 0.91 |
| Net Debt / Assets ⓘ | 11.79% | 13.69% |
| EBITDA / Interest ⓘ | 36.72 | 11.93 |
| Operating Margin (Latest) ⓘ | 39.83% | 13.07% |
| Operating Margin (5Y Median) ⓘ | 23.87% | 11.86% |
| Debt to Equity (Latest) ⓘ | 25.70% | 40.43% |
| Profit Margin (Latest) ⓘ | 29.83% | 6.57% |
| Free Cash Flow (Latest) ⓘ | -$624.42M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +334.40% | +65.06% |
| 12M Return (excl. last month) ⓘ | +81.66% | +36.05% |
| 6M Return ⓘ | +12.56% | +1.89% |
| Price vs. 200-Day MA ⓘ | +4.47% | +1.03% |
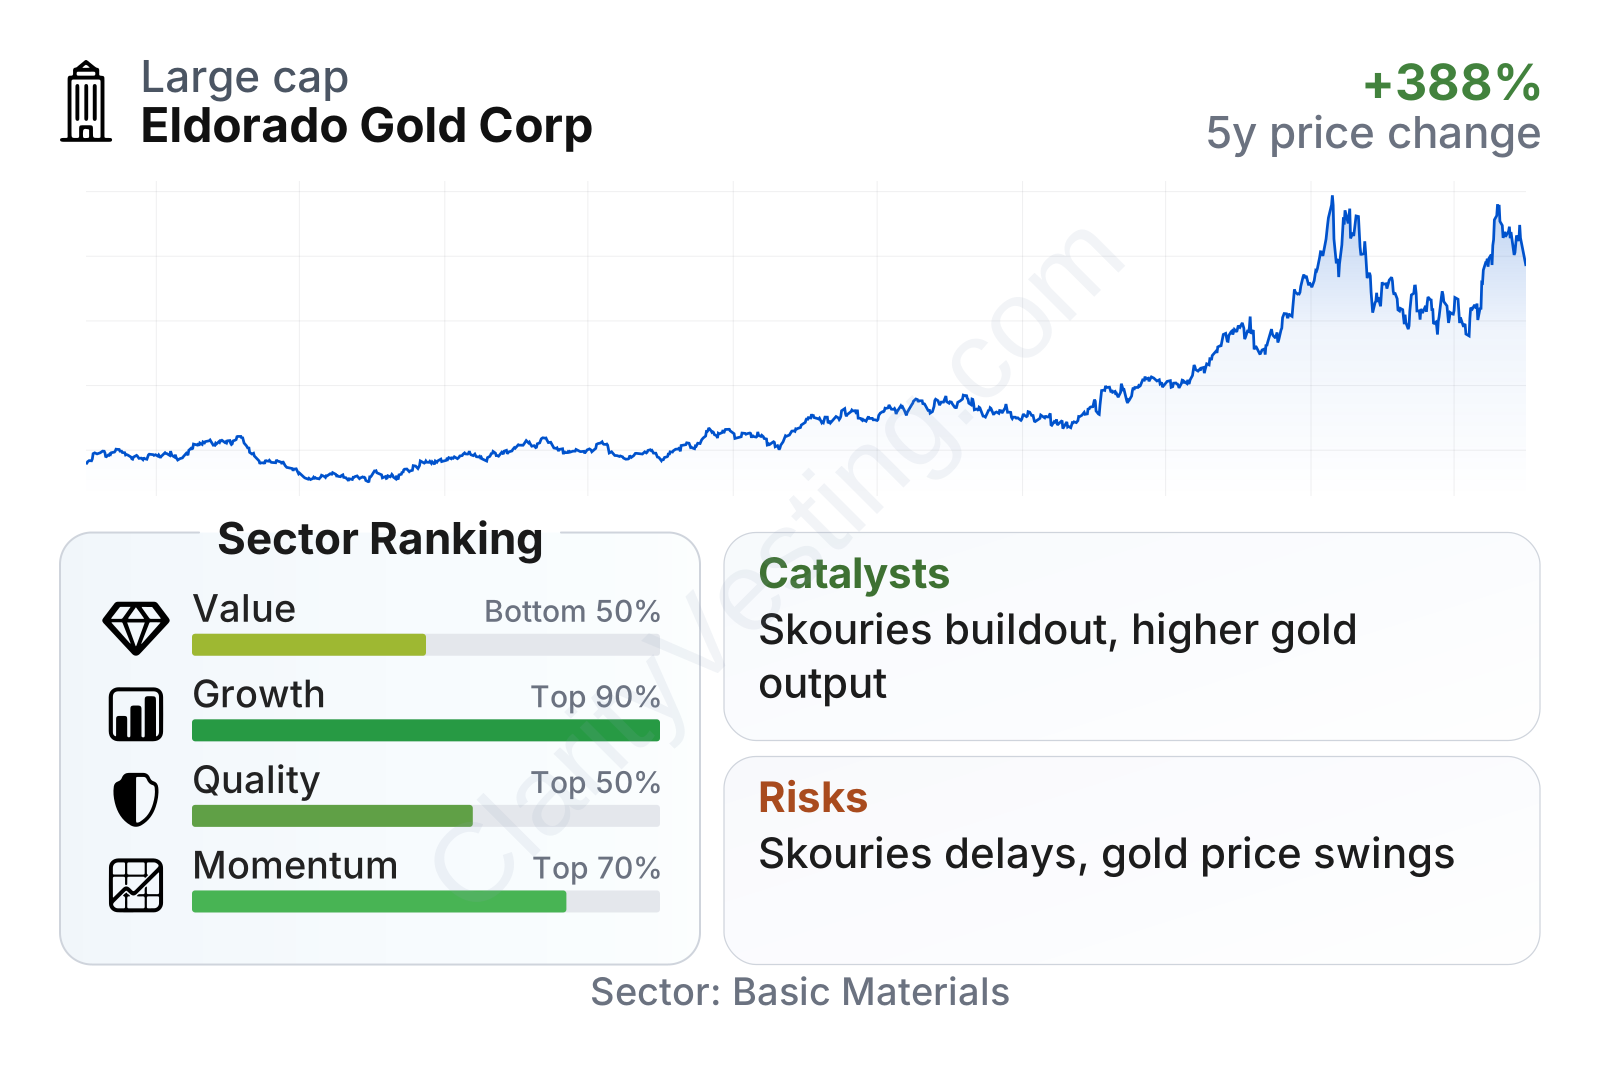
Eldorado stands out for strong growth and solid current profitability, while valuation multiples look mixed rather than clearly cheap. The quality profile is better than many peers on margins and returns, and leverage remains moderate for a miner. The weaker point is free cash flow, which is currently negative, so the business looks stronger on accounting earnings than on near-term cash conversion. The stock has also been more volatile than the market overall, which fits the nature of a gold producer with active development projects.
Growth
Gold mining is not a high-growth industry in the same way as software or semiconductors, but it can still offer long-duration growth when a company has a pipeline of mine expansions and new projects. Eldorado operates in a sector supported by durable drivers: central bank gold buying, long-term inflation concerns, geopolitical uncertainty, and the difficulty of bringing new mines into production globally. Because new large gold deposits are hard to find and expensive to develop, existing producers with expansion opportunities can become more valuable over time.
Eldorado’s strategy is centered on increasing production from its existing asset base while advancing development projects that can lift output over several years. The most important long-term catalyst is Skouries in Greece, a major gold-copper project that management has positioned as a transformational asset for the company. If delivered close to plan, Skouries could diversify Eldorado further, add copper exposure, and materially increase production scale. That matters because larger miners often get more flexibility in funding, operations, and regional risk management.
Revenue growth has been strong through most of the recent period, with several quarters showing very high year-over-year expansion before moderating more recently. That pattern suggests Eldorado has already captured a major benefit from stronger production and higher realized gold prices, so future growth will likely depend more on execution than on easy comparisons.
Free cash flow has been uneven and recently negative, which is common when a miner is spending heavily on construction and development. In Eldorado’s case, that weakness is closely linked to capital spending rather than a collapse in profitability. For a long-term view, the key question is whether today’s spending translates into a larger and more cash-generative production base later on.
Recent company updates have continued to focus on construction progress, capital planning, and operating performance across the portfolio. In simple terms, the opportunity is clear: if Eldorado can keep its current mines performing well while bringing Skouries forward without a major cost or schedule setback, the company could move into a meaningfully larger earnings and cash flow bracket over time.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


