Stock Analysis · Eiffage SA (EFGSY)
Overview
Eiffage is a large French infrastructure and construction group active across the full project chain: building construction, civil engineering, transport infrastructure, energy systems, and long-term concessions. In simple terms, the company helps design, build, equip, and sometimes operate major assets such as offices, housing, industrial sites, roads, rail systems, public infrastructure, and electricity networks. That mix matters because it gives Eiffage exposure not only to one-off construction contracts, but also to recurring cash generation from concession assets.
The business is usually presented through four main activities. Based on the latest company reporting, revenue is broadly distributed as follows:
- Energy Systems: about 38% of revenue. This includes electrical engineering, industrial and digital systems, climate engineering, and services linked to energy efficiency and low-carbon infrastructure.
- Construction: about 31% of revenue. This covers commercial buildings, housing, urban development, public facilities, and associated real estate-related construction work.
- Infrastructure: about 23% of revenue. This includes roads, rail, earthworks, civil engineering, metal construction, and other large transport or public works projects.
- Concessions: about 8% of revenue. This segment includes motorway and airport operations and other long-duration assets that can produce steadier earnings than pure contracting activities.
Geographically, France remains the core market, but Eiffage also has meaningful exposure to other European countries through energy, infrastructure, and specialized contracting operations. Its model is more diversified than a standard builder because it combines project execution with operating assets.
The long-term financial picture has been one of expanding revenue, with sales rising from roughly €19 billion in 2021 to more than €26 billion in 2025. Operating income also moved higher over that period, although net profit has been less smooth because financing costs and taxes can fluctuate more than project activity. That profile is typical for a capital-intensive contractor with concession exposure: scale and backlog can grow steadily while bottom-line conversion is more uneven.
Over the last several years, the business has clearly become larger, and operating profit has improved with it. At the same time, financing costs remain a meaningful item, which helps explain why revenue growth does not translate one-for-one into net income growth.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Engineering & Construction | |
| Market Cap ⓘ | $10.73B | |
| Beta ⓘ | 0.73 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 8.63 | 22.29 |
| P/B Ratio ⓘ | 1.73 | 1.98 |
| FCF Yield ⓘ | 50.83% | 6.26% |
| Dividend Yield ⓘ | 5.04% | 1.92% |
| EBIT / EV ⓘ | N/A | 4.83% |
| PEG ⓘ | 2.47 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 1.10% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | 9.62% | 7.76% |
| EPS Growth (5Y CAGR) ⓘ | 4.99% | -13.17% |
| BVPS Growth (5Y CAGR) ⓘ | 4.23% | 6.13% |
| Margin Growth (5Y Trend) ⓘ | -0.07% | 0.74% |
| FCF Growth (5Y CAGR) ⓘ | 12.41% | 10.79% |
| DPS Growth (5Y CAGR) ⓘ | -9.08% | 9.41% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 15.50% | 10.75% |
| ROA (Latest) ⓘ | 4.97% | 5.41% |
| ROIC (5Y Median) ⓘ | 7.36% | 9.37% |
| ROA (5Y Median) ⓘ | 2.56% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | 2.11 | 2.04 |
| Net Debt / EBIT (5Y Median) ⓘ | 4.67 | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | 1.31 | 1.39 |
| Net Debt / Assets ⓘ | 26.47% | 19.27% |
| EBITDA / Interest ⓘ | 9.73 | 9.58 |
| Operating Margin (Latest) ⓘ | 10.05% | 10.49% |
| Operating Margin (5Y Median) ⓘ | 10.25% | 10.30% |
| Debt to Equity (Latest) ⓘ | 201.99% | 64.82% |
| Profit Margin (Latest) ⓘ | 4.03% | 6.67% |
| Free Cash Flow (Latest) ⓘ | $5.45B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +38.75% | +67.77% |
| 12M Return (excl. last month) ⓘ | -1.94% | +12.05% |
| 6M Return ⓘ | -30.07% | 0.00% |
| Price vs. 200-Day MA ⓘ | -21.69% | +0.67% |
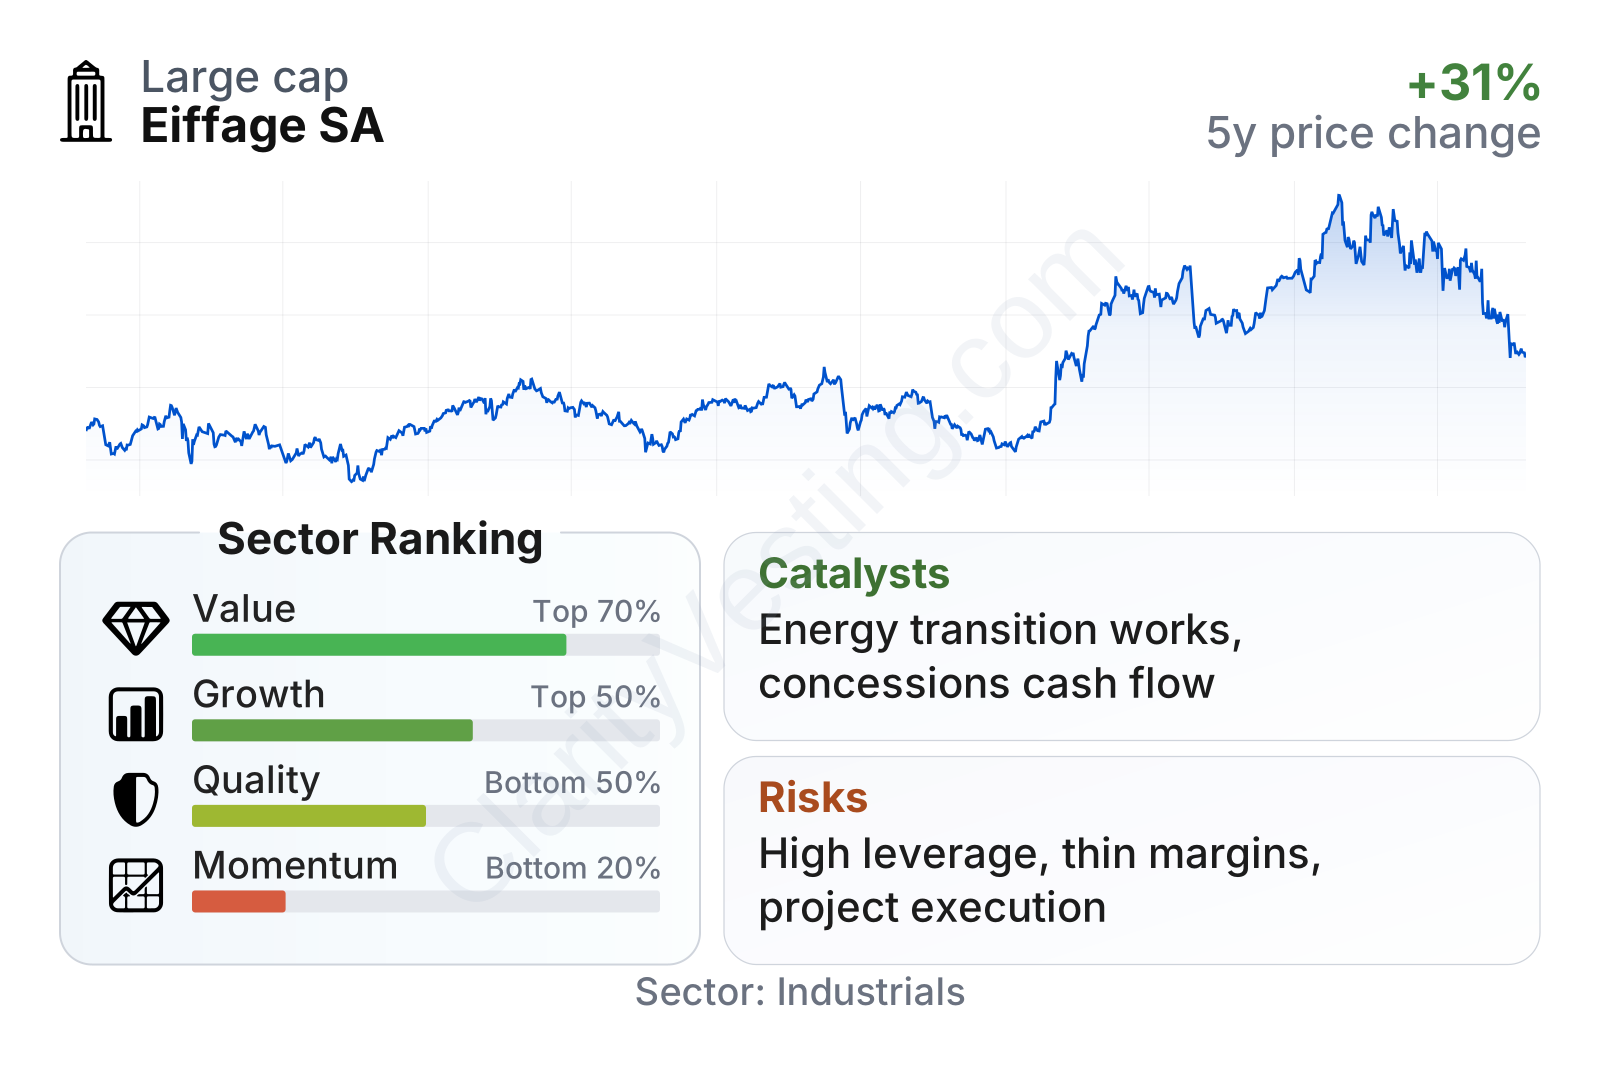
Eiffage screens as a large industrial company with a relatively low share-price volatility profile. On valuation measures, it sits below the sector median on earnings multiples while offering a higher dividend yield and unusually strong free cash flow generation. Growth indicators are more mixed: the long-term trend is solid, but recent year-over-year expansion has been slower than the broader sector. Quality metrics are uneven, with returns on invested capital looking respectable, while leverage and profit conversion remain weaker points.
Growth
Eiffage operates in markets that still have structural support: power grid upgrades, energy efficiency retrofits, transport infrastructure renewal, rail development, and public investment tied to decarbonization. These are not short-lived themes. Europe needs continued spending on electrification, building renovation, climate adaptation, and mobility infrastructure, and Eiffage is positioned in several of those categories at once.
Its strategy also makes industrial sense. The company is not dependent on a single niche. It combines construction and civil works with energy systems, which is important because many future projects require both physical infrastructure and technical equipment. A rail upgrade, logistics platform, hospital, or industrial site increasingly needs electrical systems, digital controls, efficiency improvements, and maintenance capabilities. That favors companies able to offer a broader solution set.
The concessions business adds another useful angle. Motorway and airport assets can provide recurring cash flows that are less cyclical than construction contracts. This can support overall resilience and gives the group an earnings base that many peers do not have to the same extent.
Recent top-line growth appears positive but not spectacular in the short term, while the longer five-year trend remains more convincing. Revenue per share has grown at a high-single-digit annual pace over five years, and free cash flow has expanded at a double-digit pace. That suggests the business has been building scale even if recent annual comparisons look more moderate.
A meaningful catalyst is Europe’s ongoing infrastructure modernization cycle, especially around energy transition and rail. Eiffage’s energy systems operations are particularly relevant here because grid reinforcement, industrial electrification, and efficient building equipment are areas with multiyear demand visibility. Large public works pipelines in France and neighboring countries also support the backdrop.
Another favorable element is backlog visibility. Engineering and construction groups with strong order books can often plan activity several quarters ahead, reducing near-term revenue uncertainty. For Eiffage, this is important because the company’s combination of public infrastructure, technical services, and concessions tends to create a broader pipeline than a pure residential or commercial builder would have.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


